
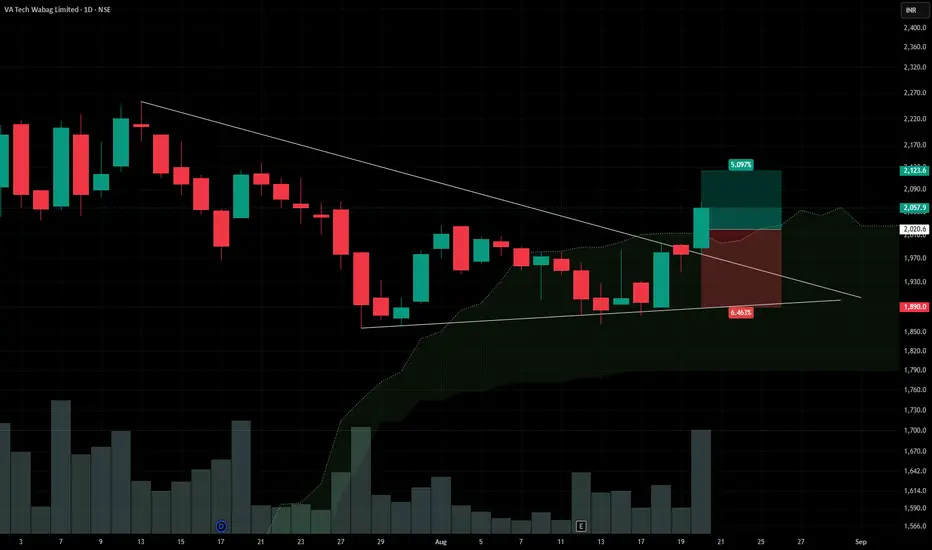
VA Tech Wabag Ltd. (CMP ₹2,057.00, NSE: WABAG)
The SmartWay Research Desk | 21 August 2026
A Chennai‑based multinational water technology company, incorporated in 1995. VA Tech Wabag is a global leader in water treatment, desalination, wastewater recycling, and industrial water solutions, with projects across India, the Middle East, Europe, and Africa.
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹6,842 Cr vs ₹6,012 Cr in FY25 (+13.8% YoY). → Good
Net Profit: FY26 PAT ₹612 Cr vs ₹512 Cr in FY25 (+19.5% YoY). → Good
Operating Margin: FY26 EBITDA ₹1,212 Cr, margin 17.7% vs 16.8% last year (+90 bps). → Good
Equity Capital: Stable, face value ₹2. → Good
Dividend Policy: Dividend ₹10.00/share declared for FY26. → Good
Asset Building: Investments in desalination plants, wastewater recycling, and industrial water solutions. → Good
Sales: Strong demand from municipal water projects and industrial clients. → Good
Expense: Raw material and infra costs remain volatile. → Neutral/Good
EPS: FY26 EPS ₹42.25 vs ₹35.40 last year (+19.3%). → Good
Institutional Interest & Ownership Trends (Mar 2026)
Promoter Holding: ~21.5% (no pledges)
FII Holding: ~28.2%
DII Holding: ~32.1%
Retail & Others: ~18.2%
Strategic Moves & Innovations
Expansion in desalination projects in Middle East & Africa.
Focus on wastewater recycling and zero‑liquid discharge solutions.
Partnerships with state governments for smart city water projects.
Diversification into industrial water treatment for power & pharma sectors.
Cash Flow & Balance Sheet Strength
Market cap ~₹12,800 Cr.
Debt‑to‑equity ratio ~0.36 (moderate leverage).
Book value per share ₹312.00; P/B ~6.6.
EPS (TTM) ₹42.25; P/E ~48.7.
Risk Factors
High P/E ratio ~48.7, valuations expensive.
Dependence on government contracts and infra spending cycles.
Exposure to execution risks in large overseas projects.
Competition from Ion Exchange, Thermax, and Larsen & Toubro Water.
Investor Takeaway
VA Tech Wabag has delivered robust FY26 performance, supported by desalination expansion, wastewater recycling, and industrial water demand. With strong institutional interest, dividend payouts, and leadership in water technology, Wabag remains a mid‑cap infra‑linked water solutions play. At CMP ₹2,057.00, valuations are expensive (P/E ~48.7, P/B ~6.6), reflecting growth expectations but also execution risks.

Sucrit.D.Patil
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.
Sucrit.D.Patil
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.