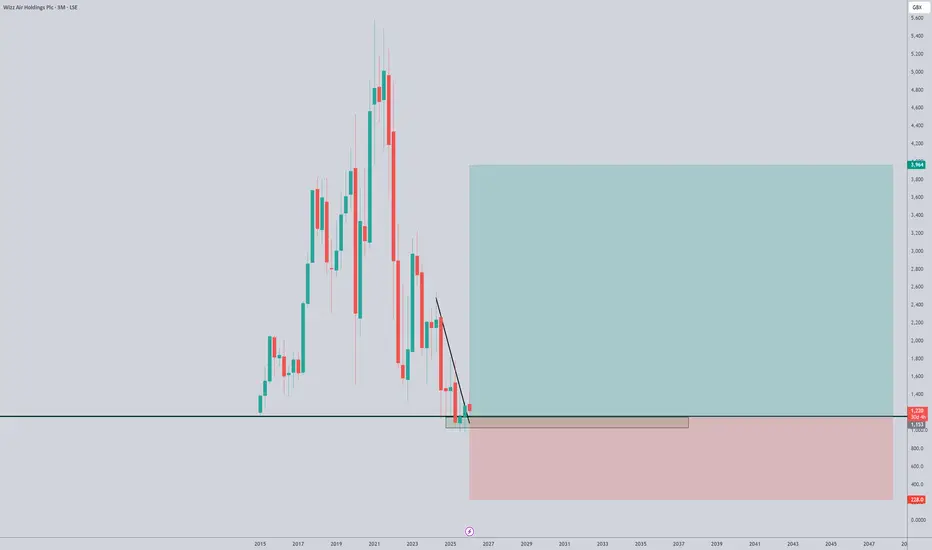
Wizz Air ( WIZZ) is currently facing a turbulent 2026. While the company maintains an impressive ROE of 46%, this is heavily skewed by its massive Debt/Equity ratio of 970%. The airline is struggling with the Pratt & Whitney engine crisis, leaving nearly 20% of its fleet grounded, which has capped revenue growth at a modest 10.2%—far below my 30% target. The Altman Z-Score of 0.73 puts the company in the 'Distress Zone,' highlighting significant solvency risks. Recent mass selling by major shareholder Indigo Partners (10M shares sold in Feb 2026) further dampens sentiment. Until the fleet is fully operational and the balance sheet is deleveraged, WIZZ remains a high-risk recovery play rather than a high-quality growth compounder.
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.