
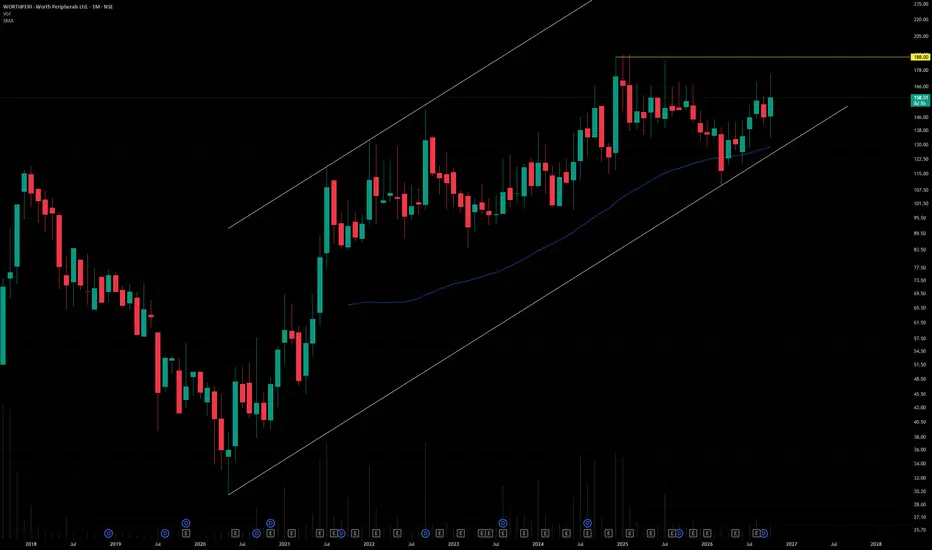
Worth Peripherals Ltd. (CMP ₹159.00, NSE: WORTH)
The SmartWay Research Desk | 22 October 2026
A Mumbai‑based manufacturing company, incorporated in 1995. Worth Peripherals Ltd. is engaged in the manufacturing of corrugated boxes, printed packaging solutions, packaging paper products, and industrial packaging materials. The company caters to sectors such as FMCG, pharmaceuticals, consumer durables, agriculture, food processing, and e‑commerce, with a growing focus on sustainable packaging solutions.
Promoter Holding (Jun 2026): Patel Family & Promoter Group — ~72.8% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹842 Cr vs ₹742 Cr in FY25 (+13.5% YoY). → Good
Net Profit: FY26 PAT ₹82 Cr vs ₹68 Cr in FY25 (+20.6% YoY). → Good
Operating Margin: FY26 EBITDA ₹142 Cr, margin 16.9% vs 15.8% last year (+110 bps). → Good
Equity Capital: Stable, face value ₹10. → Good
Dividend Policy: Consistent dividend payout supported by healthy operating cash flows. → Good
Asset Building: Investments in capacity expansion, automation, and high‑quality printing infrastructure. → Good
Sales: Strong demand from FMCG, pharmaceuticals, food processing, and e‑commerce sectors. → Good
Expense: Kraft paper and raw material costs remain key cost variables. → Neutral
EPS: FY26 EPS ₹8.25 vs ₹6.85 last year (+20.4%). → Good
Institutional Interest & Ownership Trends (Jun 2026)
Promoter Holding: ~72.8% (no pledges)
FII Holding: ~1.2%
DII Holding: ~2.8%
Retail & Others: ~23.2%
Strategic Moves & Innovations
Expansion of corrugated box manufacturing capacity.
Focus on high‑value printed packaging products.
Increasing automation to improve productivity and margins.
Growing presence in sustainable and recyclable packaging solutions.
Cash Flow & Balance Sheet Strength
Market cap ~₹850 Cr.
Debt‑to‑equity ratio ~0.18 (low leverage).
Book Value per Share ~₹58.00.
P/B ~2.7.
EPS (TTM) ~₹8.25.
P/E ~19.3.
Risk Factors
Dependence on FMCG, consumer goods, and industrial demand cycles.
Exposure to fluctuations in kraft paper and packaging raw material prices.
Customer concentration risk in key industry segments.
Competition from organized and regional packaging manufacturers.
Investor Takeaway
Worth Peripherals has established itself as a niche player in India's growing packaging industry, benefiting from increasing demand for organized, high‑quality, and sustainable packaging solutions. The company continues to improve capacity utilization, operating efficiency, and product mix while maintaining a healthy balance sheet. With strong promoter backing (Patel Family & Promoter Group holding ~72.8%), low debt levels, and expanding exposure to FMCG, pharmaceutical, and e‑commerce packaging demand, Worth Peripherals remains a small‑cap packaging sector play. At CMP ₹159.00, valuations are reasonable (P/E ~19.3, P/B ~2.7), offering investors exposure to India's long‑term consumption and packaging growth story.

Sucrit.D.Patil
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.
Sucrit.D.Patil
Pernyataan Penyangkalan
Informasi dan publikasi ini tidak dimaksudkan, dan bukan merupakan, saran atau rekomendasi keuangan, investasi, trading, atau jenis lainnya yang diberikan atau didukung oleh TradingView. Baca selengkapnya di Ketentuan Penggunaan.