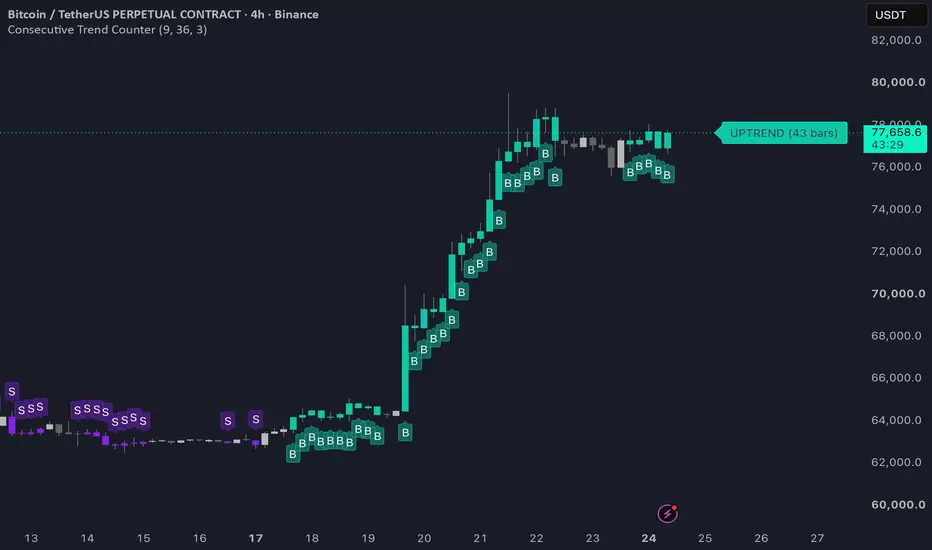
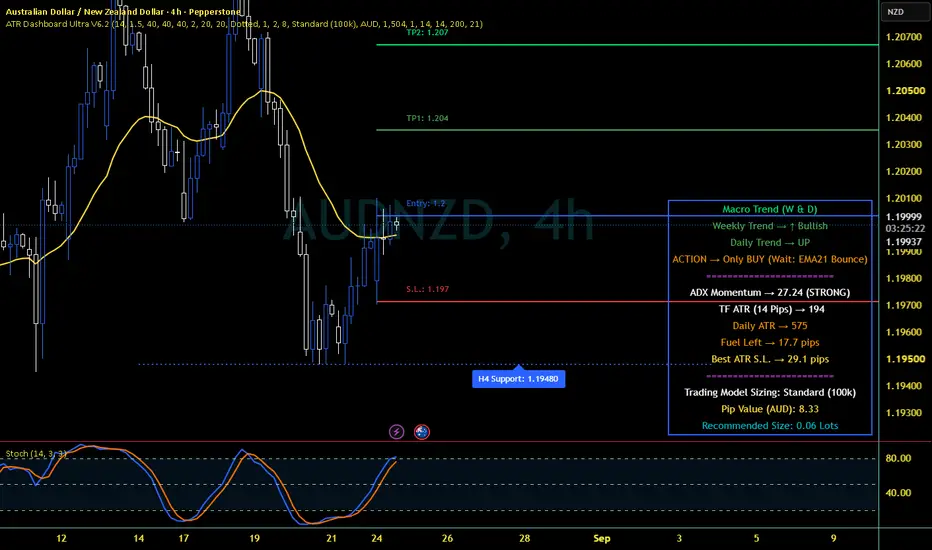
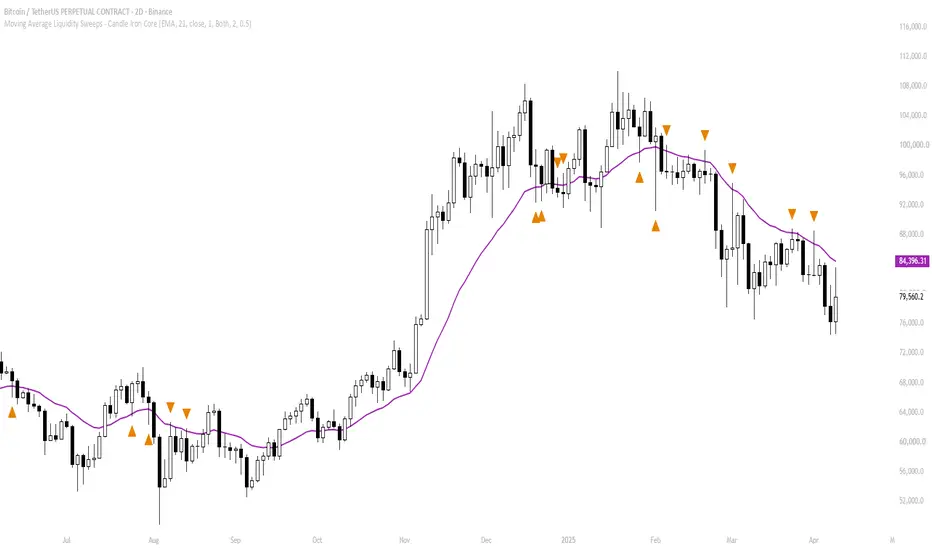
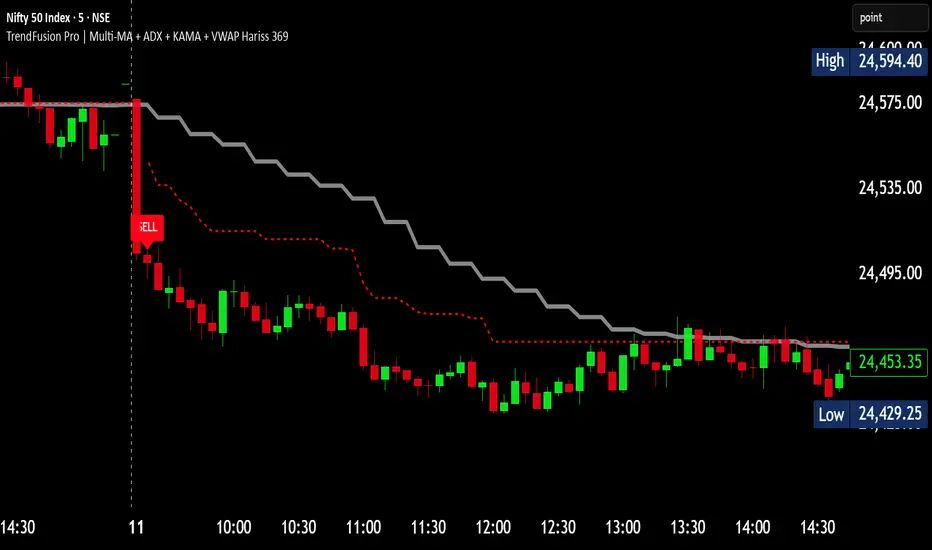
NRTR Adaptive Trailing Reverse [MarkitTick]💡 An adaptive trailing-stop and reversal system built around the Nick Rypock Trailing Reverse (NRTR) algorithm, extended with a configurable smoothing engine, ADX confluence filtering, automatic risk-based trade level projection, and a live position-sizing dashboard. Rather than applying NRTR to raw closing price, this tool lets the trailing calculation run on top of one of eight selectable smoothing methods, giving traders control over how reactive or how filtered the underlying trend estimate is before the trailing stop is derived from it.
✨ Originality and Utility
The classic NRTR trailing stop is normally computed directly from price. This script decouples the "source" the trailing calculation reacts to from raw price by routing it through a selectable adaptive filter stage first — SMA, EMA, RMA, Double WMA, Triple VWMA, HMA, a custom LLAMA slope-projection filter, or a Kalman filter. This means the trailing envelope itself can be smoothed, decoupled from tick-level noise, or shaped to lag less than a conventional moving average, without changing the core NRTR ratchet-and-flip mechanic.
Beyond the trailing engine, the script closes the loop between "signal" and "trade management," which most trailing-stop tools leave to the user. Once a trend flip is confirmed, it automatically derives a stop-loss from the NRTR level itself and projects three risk-multiple take-profit targets, tracks whether each has been hit, calculates a suggested position size from a risk percentage or fixed-dollar risk model, and optionally suppresses new signals for a cooldown period after a stop-out. An ADX confluence filter can additionally require a minimum trend strength reading before a flip is treated as valid. The combination is justified because each component consumes the output of the one before it: the adaptive filter conditions the source, the NRTR logic converts that source into a trailing stop and flip signal, the ADX filter validates the flip's context, and the risk/sizing engine turns the validated flip into an actionable, fully quantified trade plan — a single coherent pipeline rather than an arbitrary bundling of unrelated indicators.
🔬 Methodology and Concepts
• The Adaptive Source Filter
Before any trailing-stop math happens, closing price is optionally passed through one of these transformations, selected from the "Adapt Filter" input:
SMA / EMA / RMA — standard moving averages, included as familiar baselines.
Double WMA — a Weighted Moving Average applied twice in succession (a WMA of a WMA), which produces a lower-lag response than a single WMA of the same length.
Triple VWMA — a Volume Weighted Moving Average cascaded three times, folding volume-weighting into a lower-lag smoothing chain.
HMA — the Hull Moving Average, using weighted-moving-average differencing to reduce lag relative to standard smoothing.
LLAMA — a proprietary two-part filter that combines a simple moving average of the source with a linear slope term measured over the same lookback (the rate of change between the current source value and the value from `length` bars ago, divided by `length`). The slope is scaled by half the filter length and added to the SMA, producing a trend-projected estimate that leans ahead of a plain average in the direction of the recent slope.
Kalman Filter — a lightweight recursive estimator that updates a running estimate of the "true" price using a prediction/correction cycle. It maintains an internal error estimate and a gain term derived from the ratio of process noise (set by the inverse of the filter length) to measurement noise, blending each new price observation into the estimate proportionally to that gain.
None — the trailing logic operates directly on closing price.
When "None" is selected, the tool behaves as a standard price-based NRTR. Any other selection substitutes that smoothed series as the "source" for every downstream calculation.
• NRTR Trailing Calculation
The script offers two modes for sizing the trailing offset, chosen via "NRTR Mode":
Percent — the offset is a fixed percentage of the (lagged) adaptive source value.
ATR — the offset is a multiple of the Average True Range over a configurable lookback, scaling the trailing distance to current volatility rather than a fixed percentage.
In an uptrend, the script tracks the highest adaptive-source value reached since the last flip (the "extreme") and subtracts the offset from it to produce a trailing level that can only rise or stay flat — never fall — while the trend persists. In a downtrend, the mirror logic tracks the lowest extreme and adds the offset, producing a level that can only fall or stay flat. A trend flip occurs the moment the prior bar's adaptive source closes beyond the trailing level: closing below it in an uptrend flips the state to a downtrend (and vice versa), at which point the extreme and trailing level reset and begin tracking in the new direction. Because the ratchet only ever tightens toward price, this produces the classic NRTR "stair-step" trailing behavior rather than a smooth curve.
• Confirmation and Non-Repainting Behavior
The trend-state comparison that triggers a flip always references the previous bar's confirmed adaptive-source value, and every alert condition is additionally gated behind `barstate.isconfirmed`. This means a signal only fires once its triggering bar has fully closed — the trailing level and trend state do not repaint once a bar is confirmed, and alerts cannot fire prematurely intrabar.
• ADX Confluence Filter
When enabled, a flip is only accepted as a valid trading signal if the prior bar's ADX reading (calculated over the same configurable length for both DI and ADX smoothing) is at or above the threshold input. This is intended to suppress flips that occur while the market lacks directional strength, where trailing-stop whipsaws are most common.
• Cooldown Guard
When enabled, a stop-loss hit on one side of the market starts a bar-count cooldown during which a new signal in that same direction is suppressed, intended to reduce immediate re-entry into a level that has just failed.
• Trade Level Projection and Position Sizing
On a valid signal, the entry is taken at the current close, the stop-loss is set to the NRTR trailing level at that moment, and the initial risk distance (entry-to-stop) is multiplied by three independently configurable multiples to project TP1, TP2, and TP3. Each target and the stop are tracked bar-by-bar for whether price has traded through them, updating their on-chart labels accordingly. A suggested position size is calculated from either a percentage of a user-defined account size or a fixed dollar risk amount, divided by the entry-to-stop distance in price, giving a size that risks a consistent dollar or percentage amount regardless of current volatility.
🎨 Visual Guide
NRTR Line — a grey step-line plotting the current trailing-stop level.
Heatmap Candles — the chart's candles are recolored using the Bull/Bear color inputs (teal/red by default) to reflect the current trend state directly on price, rather than requiring a separate indicator pane.
Cooldown Background — a shaded background tint appears while a directional cooldown is active after a stop-out, using the Cooldown BG color.
Trade Level Lines and Labels (on signal) — a solid red Stop Loss line, a dashed blue Entry line, and three dashed green Take Profit lines (TP1 lightest, TP3 most opaque) extend from the signal bar. Each carries a right-aligned label showing its exact price; once a target or stop is touched, its label updates in place to show the hit and the resulting percentage gain or loss from entry.
Risk/Reward Shading — a light red fill shades the zone between Entry and Stop Loss (the risk side), and a light green fill shades the zone between Entry and TP3 (the full reward side), giving an immediate visual sense of the trade's risk-to-reward geometry.
Dashboard Table — a corner-anchored panel (position configurable) summarizing, in real time: current trend direction, Lock status, the live NRTR level, active entry/stop/TP1 prices, the current ADX reading (colored by pass/fail against the threshold), the active adaptive filter, cooldown status and remaining bars, the calculated risk amount, the suggested position size, and a filled bar-graph showing how close price currently sits to the trailing stop as a percentage of the total offset distance.
📖 How to Use
A flip from red to teal candles (and the NRTR line stepping below price) signals a potential long entry; the mirror flip signals a potential short.
Use the auto-drawn Entry, Stop Loss, and Take Profit lines as a starting risk/reward framework — the SL is anchored to the trailing level at the moment of the flip, not an arbitrary distance.
Enable the ADX Filter if you want flips confirmed only during periods of measurable trend strength, which reduces (but does not eliminate) signals generated in choppy, low-ADX conditions.
Enable Cooldown Guard if you want to avoid immediate re-entry into a direction that was just stopped out — useful in ranging conditions prone to repeated whipsaws.
Enable Lock Signal to freeze the currently displayed trade levels in place (rather than having them update to the latest signal), useful for reviewing a specific historical setup without it being overwritten by newer signals.
Watch the "Dist Trail" bar in the dashboard as a quick visual read of how far price currently sits from the trailing stop relative to the configured offset — a nearly full bar means price is close to triggering a flip.
The built-in alert payloads are formatted as JSON and include action, ticker, timeframe, direction, entry, stop, and target fields, making them usable directly as webhook bodies for external automation without additional parsing.
⚙️ Inputs and Settings
NRTR Mode — switches the trailing offset calculation between a fixed Percent of price and a volatility-adaptive ATR multiple.
NRTR % / ATR Len / ATR Mult — control the magnitude of the trailing offset in each respective mode; larger values produce a looser trail with fewer, later flips, smaller values produce a tighter trail with more frequent flips.
Use ADX Filter / ADX Len / ADX Thresh — toggle and configure the trend-strength confluence filter described above.
Adapt Filter / Adapt Len — select the smoothing method applied to price before the NRTR calculation, and its lookback length.
Cooldown Guard / Cooldown Bars — toggle and configure the post-stop-out re-entry suppression window.
Lock Signal — freezes the currently plotted trade levels rather than letting them advance to the newest signal.
Position Sizing / Sizing Mode / Risk % Trade / Fixed Risk $ / Account $ — configure whether suggested size is derived from a percentage of account equity or a fixed dollar risk figure, and the inputs feeding that calculation.
TP1/TP2/TP3 Mult — the risk multiples applied to the entry-to-stop distance to project each take-profit level.
Heatmap Candles / NRTR Line / Trade Levels — independently toggle each visual layer on or off.
Dash Pos / Show Dash — position and visibility of the dashboard table.
Alert Action fields (Long/Short/Close Long/Close Short) — customize the "action" string embedded in each webhook JSON payload, useful for matching the field names expected by a specific external automation system.
Color inputs — independently customize every plotted and dashboard color.
🔍 Deconstruction of the Underlying Scientific and Academic Framework
The NRTR mechanic itself belongs to a family of stop-and-reverse trailing systems related conceptually to Wilder's Parabolic SAR and to chandelier-style trailing stops: all three share the property that the trailing level is a one-directional ratchet — it can only move in the direction that tightens toward price — which is what mechanically prevents the trailing stop from ever "giving back" more than the configured offset once a trend is underway. Where NRTR differs is in decoupling the ratchet from a fixed acceleration curve (as in Parabolic SAR) and instead deriving it directly from a percentage or volatility-scaled offset off a tracked local extreme, which is closer in spirit to a Donchian- or Chandelier-style trailing construction.
The ATR-based offset mode draws on Welles Wilder's concept of using recent true-range volatility, rather than a fixed percentage, to size a trailing distance — the rationale being that a constant percentage offset is too tight in high-volatility regimes (generating premature stop-outs) and too loose in low-volatility regimes (giving back excess profit), while an ATR-scaled offset expands and contracts with the instrument's own recent behavior.
The Double WMA and Triple VWMA filters are cascaded-smoothing constructions in the same family as Hull's differencing approach: repeatedly passing a series through a weighted average and recombining the outputs is a general technique for pushing a smoothing filter's group delay down without simply shortening its lookback (which would otherwise increase noise sensitivity). The Kalman filter option applies a simplified, single-state version of the classic recursive Bayesian estimator from control theory, where each new observation is blended into a running estimate according to a gain term balancing assumed process noise against assumed measurement noise — conceptually the same estimation framework used in tracking and signal-processing applications outside of finance. The custom LLAMA filter combines a central-tendency estimate (a simple moving average) with a first-order trend term (a discrete slope measured over the same window), an approach related in principle to linear trend-projection and regression-based smoothing techniques that attempt to reduce lag by explicitly modeling the direction a series is moving rather than only its recent average level.
The ADX component derives from Wilder's Directional Movement System, in which ADX quantifies the strength (not direction) of a trend by smoothing the divergence between positive and negative directional movement — using it as a confluence filter reflects the broader technical-analysis principle that trend-following and trailing-stop methods perform better in the specific market regime (trending, directional) they are designed for, and using a strength filter is one common approach to distinguishing that regime from a ranging one.
⚠️ Disclaimer
All provided scripts and indicators are strictly for educational exploration and must not be interpreted as financial advice or a recommendation to execute trades. We expressly disclaim all liability for any financial losses or damages that may result, directly or indirectly, from the reliance on or application of these tools. Market participation carries inherent risk where past performance never guarantees future returns, leaving all investment decisions and due diligence solely at your own discretion. Indikator

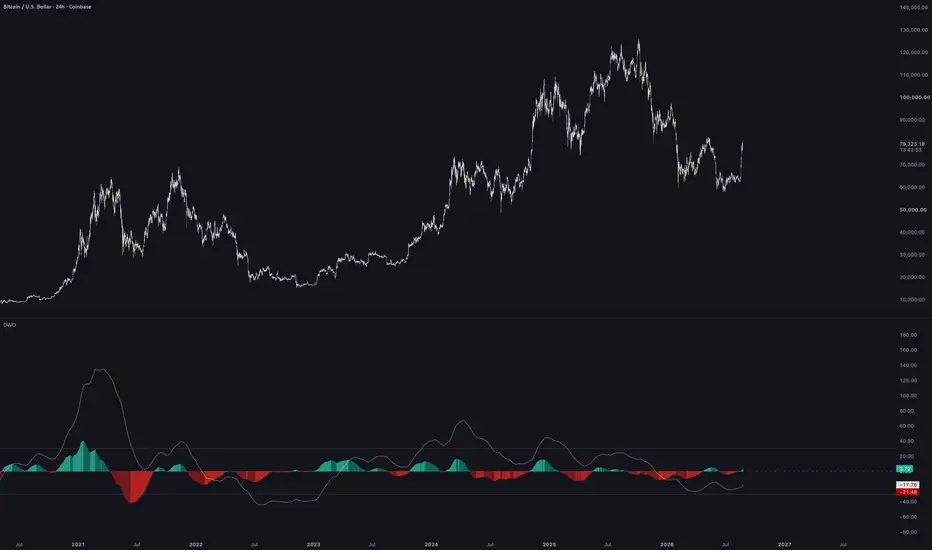
SHM 8.0 Dual-WMA Momentum Oscillator
SHM Dual-WMA Momentum Oscillator
Overview
The SHM Dual-WMA Momentum Oscillator (DWO) is an institutional-grade momentum indicator engineered to isolate structural trend direction, momentum acceleration, and high-probability reversal zones across custom timeframes.
By measuring the percentage distance between a Fast WMA and a Slow WMA, the DWO filters out market noise and locks calculation logic to a customizable higher timeframe wave—allowing you to project and track macro momentum seamlessly across every chart resolution.
Key Features & Architecture
Flexible Multi-Timeframe (MTF) Engine: Full control over your anchor timeframe (Anchor Momentum Timeframe). Choose your preferred momentum wave (e.g., 1H, 4H, Daily/24H, 3D, Weekly) and lock it to display consistently across all timeframes without repainting or distortion.
Universal Timeframe Visibility: Lock your preferred anchor to the 4-Hour wave, and that 4H momentum wave stays strictly visible whether you zoom down to a 15-minute execution chart or step up to inspect the Daily/Weekly macro chart.
Macro Trend Isolation: Eliminates transient intraday volatility, revealing where higher-timeframe capital flow is actually moving.
Triple Equilibrium Baselines: Features customizable numeric anchor points (+33, 0, -33) paired with dynamic 4-color momentum acceleration histograms to easily spot expansion, exhaustion, and mean-reversion zones.
Signal Tracking Line: Integrates a smoothed tracking curve for identifying momentum crossovers and zero-line baseline retests.
How to Use for Analysis
Selecting Your Anchor Timeframe:
Set the Anchor Momentum Timeframe in the settings input to your preferred cycle (e.g., 240 for 4H execution, 1440 for Daily macro, or 1W for high-tf positioning).
Determining Trend Bias:
DWO Line Above Zero Baseline: The selected anchor wave is structurally bullish. Intraday pullbacks act as buying liquidity.
DWO Line Below Zero Baseline: The selected anchor wave is structurally bearish. Intraday bounces act as counter-trend rallies.
Equilibrium Acceleration Histograms:
Green / Teal Histograms: Positive momentum acceleration relative to your selected anchor timeframe.
Red / Dark Red Histograms: Negative momentum acceleration relative to your selected anchor timeframe.
Inputs & Settings
Anchor Momentum Timeframe (Default: 24H / 1440): Selects the timeframe wave to project across all charts (supports 1m up to 1W).
Fast WMA Lookback (Default: 65): Controls the sensitivity of the primary signal curve.
Slow WMA Lookback (Default: 480): Establishes the baseline filter for long-term trend isolation.
Signal Smoothing Line (Default: 63): Adjusts the sensitivity of the signal tracking curve.
Triple Baseline Configuration: Sets the Y-axis levels for upper (+33), zero (0), and lower (-33) histograms.
Disclaimer
This script is designed for educational, informational, and analytical charting purposes only. It does not constitute financial or trading advice. Always perform independent analysis and practice strict risk management. Indikator

AlphaVault - Iron Turtle 1D v2.00Iron Turtle — scheduled spot accumulation, bear regimes only
BTC/USDT · Daily chart only · spot · buy-only, never sells
WHAT IT DOES
The Iron Turtle buys a fixed amount of BTC on a fixed schedule, but only while a
long-term downtrend is confirmed. When the downtrend ends it stops buying and tells you
so. It never sells, never uses leverage, and never tries to time a bottom.
It is not a trading strategy and does not pretend to be one. It is a rule that decides
when a recurring purchase should be switched on and off.
HOW IT WORKS
Two things, and that is the whole system.
1. THE REGIME TEST. On each daily close the script compares price against a 200-period
simple moving average of daily closes and a 20-period exponential moving average of
weekly closes, both taken from the last COMPLETED bar. Price below BOTH means the
bear regime is confirmed. Anything else means it is not.
2. THE SCHEDULE. While the bear regime is confirmed, the script marks a buy every N
days — 7 by default — for a fixed cash amount you set. It plots each one on the
chart and can fire an alert so you place the order yourself, or route it to a bot.
When price closes back above both filters for a set number of confirming days, the
script stops marking buys and fires a hand-off alert. That is the end of its job. What
you do with the accumulated position is entirely your decision; the script has no
opinion and no sell logic.
The regime test is deliberately the same one our other scripts use to stay OUT of the
market. Here it runs in reverse: what makes a timing strategy go flat is what makes
this one buy.
WHY IT IS OPEN SOURCE
Because there is nothing in it worth hiding, and pretending otherwise would be
dishonest. There are no optimised parameters — the moving average lengths are the
conventional ones, the schedule is a plain interval, and every rule was fixed before
any testing. You are reading the entire method above, and the code says the same thing.
A closed-source version of this would be asking you to trust a black box that has no
box.
HOW TO USE IT
- Set the chart to BTC/USDT on the Daily timeframe. The script blocks signals on any
other timeframe and shows a warning.
- Set your tranche size — the fixed cash amount per purchase.
- Set the interval in days.
- Right-click a buy marker to create an alert, or use the built-in alert for a bot.
- Add a second alert on the hand-off signal. That is the one that matters most and it
may be months away.
THE ONE THING THAT DECIDES WHETHER THIS WORKS FOR YOU
Budget for the whole bear before you start. A crypto bear market can run two years.
If you intend to buy weekly, size the tranche so you could keep buying for that long
without stopping — roughly tranche × 100 committed in total. Running out of money
halfway through is the single most common way scheduled accumulation fails, and it
converts a working plan into a realised loss at the worst possible moment.
LIMITATIONS AND SHORTCOMINGS — PLEASE READ
- It will be underwater for most of the time it is running. It buys into falling
prices by design, so an unrealised loss during accumulation is arithmetic, not
malfunction. If watching that for months is not something you can sit through,
this is the wrong tool and it is better to know now.
- No performance figures are shown here, and that is not modesty. An indicator
produces no strategy report on TradingView, so any number quoted would be
unverifiable. The rules are fully described above; test them yourself.
- It assumes bear markets eventually end. Every crypto bear so far has resolved into
a bull, but that is history, not a law, and nothing here guarantees it repeats.
- It never sells, so it gives you a position and no exit plan. That is deliberate,
and it means the hard decision is still yours.
- It does nothing at all in a bull market. Most of the time, the correct behaviour of
this script is to sit still.
- It cannot time a bottom and does not try. It will keep buying while price falls
further, and will stop buying only after the trend has already turned.
NO REPAINTING
The regime state and every buy marker use completed daily and weekly bars only,
requested without lookahead. A marker that appears on a closed bar will not move or
disappear afterwards. Indikator

Coil Breaker | RSI Range CompressionMost RSI strategies fire off static 30/70 thresholds. Coil Breaker does something different: it treats RSI itself as a volatility asset and watches for its own trading range to contract to a multi-month low — a "coil" — before trading the breakout when it releases.
How it works:
Measures RSI's high-minus-low range over the last N bars and ranks it against its own history using a percentile score
When that range compresses into the bottom percentile (default 20%), RSI is flagged as "coiled" — oscillating tightly around 50, momentum dormant
A dynamic Bollinger-style channel is plotted directly around RSI so you can visually watch the coil tighten before it fires
Once a squeeze has been active recently, a breakout above/below the established coil band (not the still-forming one) triggers an entry
Direction is set by an EMA slope filter — the coil tells you something's coming, the EMA tells you which way
Optional ADX filter keeps you out of truly dead, directionless chop
ATR-based stop, fixed R-multiple target, and equity-percent risk sizing so every trade risks a constant dollar amount
Important — read before trading:
This is a breakout/momentum system, not a mean-reversion one, and it behaves accordingly: expect a low win rate (often 30–40%) alongside a high average win/loss ratio. Most coil breakouts fail or chop — you're paying for early entry with more false signals. The edge comes from asymmetric payoff (2R+ winners vs. 1R losers), not from being right often. Judge this strategy on profit factor and expectancy, not win rate. If a 60%+ win rate is what you're looking for, this isn't that system.
Tips:
Backtest coilLen, pctLen, and the percentile threshold across your specific instrument/timeframe — coil dynamics vary a lot between assets
Watch the equity curve shape, not just the total return — make sure gains aren't carried by one or two outlier trades
Works best on instruments/timeframes with genuine volatility cycles (expansion/contraction), not ultra-choppy or illiquid markets
Pair with higher-timeframe context if you want to filter out counter-trend coil breaks
Strategi

Indikator

Adaptive T3 Hull [BackQuant]Adaptive T3 Hull
Overview
Adaptive T3 Hull is a configurable trend-following overlay that combines the lag-compensation structure of a Hull-style moving average with T3 smoothing and several optional mechanisms designed specifically to control overshoot, hooks and oscillating tails.
A conventional Hull construction gains responsiveness by comparing a faster and slower smoother, extrapolating their difference, and then smoothing the result again. This can produce a very responsive trend estimate, but the same lag compensation responsible for that responsiveness can also create exaggerated curvature around sharp reversals.
Adaptive T3 Hull makes that trade-off directly controllable.
The indicator replaces the traditional weighted-moving-average Hull stages with T3 smoothers and expands the basic Hull architecture with:
Adjustable fast/slow length relationships.
Adjustable Hull lag compensation.
Configurable final smoothing geometry.
Curvature-sensitive tail damping.
Optional asymmetric damping around turns.
An adaptive T3 volume factor.
An optional ATR-based velocity limiter.
Optional final lag compensation.
Trend-strength-dependent ribbon intensity.
Tail and curvature diagnostics in the Data Window.
The result is not intended to reproduce a standard HMA exactly. It is a generalized Hull-style framework in which the user can explicitly control the balance between responsiveness, smoothness and overshoot.
Core idea
Most trend smoothers face the same fundamental compromise:
More smoothing reduces noise but increases lag.
More lag compensation improves responsiveness but can create overshoot.
The Hull concept addresses lag by comparing a fast smoother with a slower smoother and projecting the difference forward.
A generalized form can be written as:
Hull Raw = Fast + Compensation × (Fast - Slow)
If Compensation is zero:
Hull Raw = Fast
No additional lag compensation is applied.
If Compensation is one:
Hull Raw = 2 × Fast - Slow
This reproduces the familiar compensation structure used in the standard Hull Moving Average.
Values between zero and one provide partial compensation.
Adaptive T3 Hull defaults to a substantially smaller compensation value. This is deliberate. It reduces the tendency for the projected line to extend beyond the fast smoother during sharp changes in direction.
The remaining responsiveness can then be controlled using the fast-length ratio, T3 characteristics and optional final generalization rather than relying entirely on aggressive Hull extrapolation.
Processing chain
The complete indicator can be understood as the following sequence:
Select the source and main Hull Length.
Derive a fast T3 length from the Fast Length Ratio.
Derive a final smoothing length from a configurable power-law relationship.
Calculate fast and slow T3 smoothers.
Measure velocity and curvature of the fast T3.
Normalize curvature using ATR.
Optionally reduce the active T3 Volume Factor during high curvature.
Recalculate the fast and slow T3 legs with the adaptive factor.
Measure the active curvature state.
Optionally reduce Hull compensation when curvature increases.
Construct the compensated fast-minus-slow T3 Hull.
Smooth that result through another T3 stage.
Optionally apply a final generalized lag-compensation stage.
Optionally limit extreme one-bar movement using ATR.
Determine trend from the final line slope.
Build a smoothed one-bar-offset ribbon around the result.
Each stage affects a different part of the lag-versus-overshoot problem.
T3 smoothing
The T3 is a multi-stage recursive smoother constructed from a sequence of exponential moving averages.
The script calculates six EMA stages:
E1 = EMA(Source)
E2 = EMA(E1)
E3 = EMA(E2)
E4 = EMA(E3)
E5 = EMA(E4)
E6 = EMA(E5)
Those stages are then combined using coefficients derived from the T3 Volume Factor.
The final T3 has the general form:
T3 = C1×E6 + C2×E5 + C3×E4 + C4×E3
where C1 through C4 change with the Volume Factor.
This construction allows T3 smoothing to maintain substantial smoothness while using coefficient-based compensation to reduce some of the lag created by repeated EMA filtering.
Important: T3 Volume Factor does not use trading volume
Despite its name, the T3 Volume Factor is not calculated from market volume.
It is a coefficient controlling the internal T3 response.
Changing it does not incorporate:
Exchange volume.
Volume profile.
OBV.
Money flow.
It changes how aggressively the internal EMA stages are combined.
Higher values generally increase compensation and responsiveness, but can also increase overshoot.
Lower values generally produce a more restrained and smoother response.
This relationship is particularly important in this indicator because Hull compensation and T3 compensation can interact.
An aggressive T3 followed by aggressive Hull extrapolation can produce substantially more tail behaviour than either technique alone.
Why combine T3 and Hull logic?
Hull-style smoothing and T3 smoothing approach lag reduction differently.
The Hull architecture uses:
A fast smoother.
A slow smoother.
The difference between them.
A final smoothing stage.
T3 uses:
Multiple recursive EMA stages.
A coefficient-controlled combination of those stages.
Adaptive T3 Hull combines both ideas.
Instead of:
Fast WMA.
Slow WMA.
Final WMA.
the indicator uses:
Fast T3.
Slow T3.
Compensated difference.
Final T3.
This produces a smoother underlying structure while retaining the ability to compensate for lag.
However, combining two lag-reduction mechanisms also makes overshoot control more important. Much of the indicator is therefore devoted to regulating that compensation dynamically.
Hull Length
Hull Length establishes the main smoothing horizon.
It is used to derive:
The slow T3 length.
The fast T3 length.
The final smoothing length.
Lower values:
React more quickly.
Track shorter trend changes.
Increase sensitivity to local curvature.
Can generate more frequent directional flips.
Higher values:
Produce broader trend estimates.
Reduce short-term variation.
Increase response delay.
Generally produce more persistent regimes.
Unlike a standard HMA, the relationship between these three smoothing stages is not fixed.
Fast Length Ratio
The fast T3 length is calculated as:
Fast Length = Hull Length × Fast Length Ratio
with the result rounded to a valid integer.
In a conventional Hull structure, the fast stage normally uses approximately half the main length.
Therefore:
Fast Length Ratio = 0.50
reproduces the familiar half-length relationship.
The default configuration uses a larger ratio, making the fast leg closer in length to the slow leg.
This matters because the difference:
Fast T3 - Slow T3
is the quantity used for lag compensation.
If the fast and slow stages are very different:
Their separation can become larger.
Hull compensation becomes stronger.
The resulting line can react faster.
Overshoot potential increases.
If their lengths are closer:
Their separation becomes smaller.
The compensation term becomes more restrained.
The final line generally becomes smoother.
Fast Length Ratio is therefore another direct control over the aggressiveness of the Hull projection.
Hull Compensation
Hull Compensation controls how much of the fast-versus-slow difference is added back to the fast T3.
The underlying formula is:
Hull Raw = Fast T3 + Effective Compensation × (Fast T3 - Slow T3)
Before adaptive damping is applied, Effective Compensation begins from the Hull Compensation input.
Compensation = 0
The raw line becomes the fast T3 itself.
No Hull-style extrapolation occurs.
Compensation = 1
The calculation becomes:
2 × Fast T3 - Slow T3
which matches the standard Hull lag-compensation form.
Compensation between 0 and 1
Only part of the fast-slow separation is extrapolated.
This creates a middle ground between:
Pure fast smoothing.
Full Hull compensation.
Compensation above 1
The difference is extrapolated even more aggressively than a conventional Hull construction.
This can create a highly responsive line, but it also increases the likelihood of:
Overshoot.
Hooks.
Large tails after sharp turns.
The default is intentionally conservative relative to a standard Hull.
What are Hull tails?
Hull-style moving averages can develop a distinctive oscillating or hooked appearance around strong reversals.
This occurs because the lag-compensation term is effectively extrapolating the difference between two smoothers.
Imagine the fast smoother accelerating upward while the slow smoother is still catching up.
The difference:
Fast - Slow
becomes positive.
Adding that difference to the fast smoother projects the result even further upward.
When price abruptly reverses, the fast smoother begins turning first while the slow smoother remains elevated.
The compensation term can then change rapidly and cause the completed Hull to:
Extend beyond the fast line.
Hook sharply.
Reverse with excessive curvature.
This is not necessarily an error in the Hull formula. It is a consequence of aggressive lag compensation.
Adaptive T3 Hull includes several independent tools for reducing this behaviour.
Final Hull smoothing
After the fast and slow T3 legs are combined, the raw Hull is smoothed again.
The final smoothing length is calculated from:
Length^Hull Smoothing Exponent × Final Smoothing Multiplier
This generalizes the standard Hull square-root stage.
A conventional HMA normally uses approximately:
sqrt(Length)
which is equivalent to:
Length^0.50
before rounding.
Hull Smoothing Exponent
The Hull Smoothing Exponent controls how strongly the final smoothing length grows as the main Hull Length increases.
Exponent = 0.50
Reproduces the square-root relationship used in the conventional Hull construction.
Exponent below 0.50
Produces a shorter final smoothing stage, particularly at larger main lengths.
This generally:
Increases responsiveness.
Allows more of the compensated movement through.
Exponent above 0.50
Creates a longer final smoothing stage.
This generally:
Reduces local variation.
Smooths more aggressively.
Adds response delay.
The script allows this relationship to be generalized instead of forcing the standard square-root rule.
Final Smoothing
Final Smoothing applies an additional multiplier to the derived root length:
Final Length = Length^Exponent × Root Multiplier
This gives a second level of control over the final stage without changing the underlying power-law relationship.
Higher values:
Increase final smoothing.
Reduce local hooks.
Slow the line.
Lower values:
Decrease final smoothing.
Increase responsiveness.
Allow more short-term curvature through.
The Smoothing Exponent controls how smoothing scales with Hull Length.
The Final Smoothing multiplier controls the overall magnitude of that final stage.
Curvature measurement
Adaptive tail damping requires a way to determine when the fast T3 is changing direction unusually quickly.
The indicator first calculates velocity:
Velocity = Fast T3 - Previous Fast T3
Previous velocity is:
Previous Velocity = Previous Fast T3 - Fast T3 two bars ago
Curvature is then approximated as the absolute change in velocity:
Curvature = |Velocity - Previous Velocity|
This is a discrete second-difference concept.
Velocity describes how quickly the smoother is moving.
Curvature describes how quickly that velocity itself is changing.
For example:
A steadily rising line can have positive velocity but low curvature.
A line suddenly flattening after a strong rise can have high curvature.
A sharp reversal can produce very high curvature.
This makes curvature particularly useful for detecting the conditions in which Hull overshoot tends to appear.
ATR normalization
Raw curvature is not directly comparable across instruments.
A $10 curvature movement is enormous for one market and negligible for another.
The script therefore normalizes curvature using ATR:
Normalized Curvature = Curvature / ATR
The result is capped at 1.
This creates an adaptive pressure measure between approximately:
0 = little curvature relative to recent range.
1 = very large curvature relative to recent range.
ATR is calculated using the Damping Normalization length.
This normalized curvature drives several optional adaptive mechanisms.
Damping Normalization
Damping Normalization controls the ATR period used when converting curvature into a relative value.
Short values:
Make the normalization respond rapidly to current volatility.
Allow damping pressure to change quickly.
Longer values:
Create a more stable volatility baseline.
Reduce rapid changes in normalized curvature.
This setting does not smooth the final T3 Hull directly.
It changes how the adaptive systems interpret curvature.
Adaptive Tail Damping
Adaptive Tail Damping dynamically reduces Hull Compensation when curvature becomes large.
The process can be summarized as:
Effective Compensation = Hull Compensation × (1 - Damping Pressure × Damping Strength)
When curvature is low:
Damping Pressure approaches zero.
Effective Compensation remains close to the selected Hull Compensation.
When curvature becomes large:
Damping Pressure increases.
Effective Compensation is reduced.
This means the indicator deliberately removes some of its lag compensation precisely when the fast T3 is bending sharply.
Why reduce compensation during curvature?
Hull compensation is most useful when the fast and slow smoothers are moving consistently in the same directional structure.
During a smooth trend:
The fast line leads the slow line.
Their separation can be used to reduce lag.
During a sharp turn:
The fast line may reverse before the slow line.
Their separation can become a poor estimate of useful forward compensation.
Extrapolating the full difference can create overshoot.
Adaptive damping therefore treats high curvature as a reason to trust the Hull extrapolation less.
Damping Strength
Damping Strength determines how much curvature can reduce Hull compensation.
At zero:
Curvature has no effect on compensation.
As the value increases:
High-curvature events remove progressively more compensation.
The line becomes more restrained around sharp turns.
At a Damping Strength of 1 and maximum normalized curvature, compensation can theoretically be reduced all the way toward zero.
This does not stop the underlying T3 from moving.
It removes the additional Hull extrapolation.
Asymmetric Turn Damping
By default, curvature damping can apply whenever the fast T3 experiences significant curvature.
Asymmetric Turn Damping makes the condition more selective.
When enabled, damping pressure is only applied when the current velocity is moving against the previous directional pace.
Conceptually:
A previously rising fast T3 is damped when its upward velocity begins weakening or reversing.
A previously falling fast T3 is damped when its downward velocity begins weakening or reversing.
This allows strong acceleration in the existing direction to retain more compensation while focusing the damping mechanism around deceleration and turning behaviour.
The purpose is to distinguish:
Curvature caused by trend acceleration.
Curvature caused by trend exhaustion or reversal.
This can preserve responsiveness during strong continuation while still suppressing tails around turns.
Adaptive T3 Volume Factor
Adaptive T3 Volume Factor provides a second curvature-sensitive damping mechanism.
Instead of changing the Hull compensation, this feature changes the internal T3 coefficient itself.
The active factor is approximately:
Active VF = Base VF × (1 - Normalized Curvature × VF Damping Strength)
subject to the configured minimum.
When curvature is low:
Active VF remains near the selected T3 Volume Factor.
When curvature rises:
Active VF is reduced.
The T3 becomes less aggressively compensated.
This attacks overshoot earlier in the processing chain.
Hull damping versus VF damping
The two mechanisms affect different stages.
Adaptive Tail Damping
changes how much:
Fast T3 - Slow T3
is extrapolated.
Adaptive T3 Volume Factor
changes how the T3 smoothers themselves are constructed.
Using both means curvature can reduce:
The aggressiveness of each T3 leg.
The aggressiveness of the Hull compensation between those legs.
This can strongly suppress tails but may also reduce responsiveness.
The controls are therefore optional and independently adjustable.
VF Damping Strength
VF Damping Strength controls how strongly curvature reduces the T3 Volume Factor.
Higher values:
Produce larger reductions during sharp curvature.
Increase smoothing around turns.
Can reduce T3 overshoot more aggressively.
Lower values:
Keep Active VF closer to the base setting.
Preserve more of the original T3 response.
Minimum VF
Minimum VF prevents the adaptive mechanism from reducing the active coefficient indefinitely.
It defines the lower bound used when Adaptive T3 Volume Factor is active.
This keeps the filter within a controlled response range during extreme curvature.
If the selected base Volume Factor is already below the requested minimum, the script does not force it upward above the base value.
Generalize Final Hull
Generalize Final Hull adds another optional lag-compensation stage after the main T3 Hull has already been completed.
A second smoothed version of the completed Hull is calculated.
The final target then becomes:
Hull Target = Hull Base + Generalization × (Hull Base - Second Hull)
This uses the same broad idea as Hull compensation:
Compare a faster estimate with a slower version.
Add part of their difference back to the faster estimate.
At zero Generalization:
The stage has no effect.
As Generalization increases:
The final result becomes more responsive.
Lag is reduced further.
Overshoot potential increases.
This option exists because the earlier tail controls allow the user to reduce aggressive compensation in the main Hull construction and, if desired, reintroduce a smaller amount of controlled responsiveness at the end.
Generalization
Generalization controls the amount of final compensation.
Lower values create subtle lag reduction.
Higher values increasingly extrapolate the difference between the first and second completed Hull smoothers.
This feature should be considered one of the more aggressive responsiveness controls in the indicator.
If the objective is maximum tail suppression, it can be left disabled.
Velocity Limiter
The Velocity Limiter addresses a different problem.
Curvature damping changes how the line is calculated.
The Velocity Limiter places a direct cap on how far the completed line is allowed to move in one bar.
The maximum permitted movement is:
Maximum Step = ATR × Max ATR / Bar
The desired change is:
Delta = Hull Target - Previous T3 Hull
That change is clamped between:
-Maximum Step
+Maximum Step
The final T3 Hull then advances by only the permitted amount.
Why use a velocity limiter?
Occasionally, a large price shock or a combination of aggressive settings can cause the completed Hull target to jump sharply.
The limiter acts as a final mechanical speed limit.
It can reduce:
Single-bar jumps.
Extreme hooks.
Shock-driven movement.
However, this comes with a clear trade-off.
If the market genuinely reprices very quickly, the limiter deliberately prevents the trend line from following the full move immediately.
It therefore introduces controlled lag.
Max ATR / Bar
This setting determines the maximum permitted single-bar movement in ATR units.
For example:
0.35 allows the completed line to move by no more than 0.35 ATR in one bar.
Lower values:
Create stronger movement suppression.
Produce smoother transitions.
Can significantly delay response to genuine breaks.
Higher values:
Interfere less often.
Allow larger legitimate moves.
The limiter is disabled by default because it is a strong constraint.
How the tail controls work together
The script provides several different ways to reduce tail behaviour because overshoot can originate at multiple stages.
Fast Length Ratio
Reduces fast-versus-slow separation.
Hull Compensation
Directly controls extrapolation of that separation.
Final Smoothing
Smooths the compensated output more heavily.
Adaptive Tail Damping
Reduces Hull compensation during curvature.
Asymmetric Turn Damping
Restricts that damping mainly to deceleration and turning behaviour.
Adaptive T3 Volume Factor
Makes the underlying T3 calculations more conservative during curvature.
Velocity Limiter
Caps the final single-bar movement.
Generalization
Moves in the opposite direction by optionally adding some final lag compensation back.
These controls are intentionally modular.
A user does not need to enable all of them.
Default design philosophy
The default settings intentionally do not reproduce a standard Hull Moving Average.
A standard Hull-like configuration would approximately use:
Fast Length Ratio near 0.50.
Hull Compensation near 1.00.
Hull Smoothing Exponent near 0.50.
Final Smoothing near 1.00.
The default Adaptive T3 Hull uses a much more restrained compensation structure.
This shifts the design away from maximum lag cancellation and toward smoother trend tracking with reduced tail behaviour.
The advanced controls then allow users to progressively move the model toward either:
More responsiveness.
More stability.
Trend determination
Trend direction is determined directly from the slope of the completed T3 Hull.
If:
Current T3 Hull > Previous T3 Hull
the direction becomes bullish.
If:
Current T3 Hull < Previous T3 Hull
the direction becomes bearish.
If the line is unchanged:
The previous state persists.
The trend does not depend on price crossing the line.
It depends on whether the adaptive T3 Hull itself is rising or falling.
Long and short signals
A long signal occurs when direction changes into the bullish state.
A short signal occurs when direction changes into the bearish state.
The markers therefore identify:
A change in slope regime.
They do not represent:
Guaranteed entries.
Price targets.
Stop levels.
Because the signal is based on local slope, more responsive configurations will naturally produce more flips during sideways conditions.
Ribbon construction
The optional band is not a conventional upper-and-lower volatility channel.
The main line is the current T3 Hull.
The secondary ribbon reference is calculated from a smoothed version of the previous-bar T3 Hull :
Ribbon Reference = WMA(T3 Hull , Band Smoothing)
The area between these two lines is filled with a gradient.
This creates visual separation between:
The current adaptive trend estimate.
A delayed and smoothed reference to its prior values.
The band therefore functions as a trend ribbon rather than a statistical volatility envelope.
Band Smoothing
Band Smoothing controls the WMA applied to the one-bar-offset Hull series.
Lower values:
Keep the ribbon reference close to the main line.
Produce a tighter band.
Respond quickly to direction changes.
Higher values:
Create a slower reference.
Widen the visual separation during sustained movement.
Create a smoother ribbon.
This input affects the visualization only.
It does not change:
The T3 Hull calculation.
Trend direction.
Signals.
Trend Strength
The indicator also calculates a normalized trend-velocity measure for visualization.
Raw strength is based on:
|Current T3 Hull - Previous T3 Hull| / ATR
and is multiplied by the Strength Sensitivity input.
The result is capped at 1 and then smoothed with an EMA.
This produces a normalized value from approximately:
0 = very little line movement relative to ATR.
1 = strong line movement relative to ATR.
This is a measure of trend-line velocity , not a statistical probability that the trend will continue.
Strength Smoothing
Strength Smoothing controls how quickly the visual strength estimate changes.
Lower values:
React quickly to acceleration and deceleration.
Create faster ribbon-intensity changes.
Higher values:
Produce steadier strength visualization.
Reduce flickering in the gradient.
It does not affect the underlying trend calculation.
Strength Sensitivity
Strength Sensitivity determines how quickly line velocity reaches the maximum normalized strength.
Higher values:
Cause smaller ATR-normalized movement to appear strong.
Increase gradient intensity more easily.
Lower values:
Require greater movement before maximum visual intensity is reached.
Strength-Weighted Gradient
When disabled, the ribbon uses a fixed gradient transparency.
When enabled, gradient intensity changes with Trend Strength.
As the T3 Hull moves more quickly relative to ATR:
The near portion of the ribbon becomes more visible.
The broader gradient becomes stronger.
When trend velocity is weak:
The ribbon becomes more subdued.
This is purely a visualization feature.
It does not alter:
Direction.
Signals.
Smoothing.
Tail damping.
Trend candles
The indicator can recolor the main chart candles according to the active T3 Hull slope state.
Bullish trend = selected Long Color.
Bearish trend = selected Short Color.
The candle colour describes the indicator regime, not the individual candle’s own open-to-close direction.
A bearish candle can therefore remain bullish-coloured while the T3 Hull is still rising.
Tail diagnostics
Several internal values are exposed in TradingView’s Data Window.
These provide insight into how the adaptive model is currently behaving.
Effective Hull Compensation
Shows the compensation actually being used after adaptive tail damping.
If adaptive damping is disabled:
It remains equal to Hull Compensation.
If damping is active:
It falls below the base value when curvature pressure increases.
This is useful for seeing when the indicator is automatically becoming more conservative.
Active T3 Volume Factor
Shows the T3 coefficient currently being used.
If Adaptive T3 Volume Factor is disabled:
It remains equal to the base Volume Factor.
When enabled:
It can decrease during high curvature.
Normalized Curvature
Shows the current curvature estimate after ATR normalization.
Values closer to 1 represent greater changes in fast-T3 velocity relative to recent range.
Trend Strength
Shows the smoothed normalized T3 Hull velocity as a percentage.
This is the same quantity used by the optional Strength-Weighted Gradient.
Tail Overshoot
The script also measures whether the final T3 Hull has extended beyond the fast T3 in the direction of the fast/slow separation.
An upper overshoot occurs when:
Fast T3 is above Slow T3.
Completed T3 Hull is above Fast T3.
A lower overshoot occurs when:
Fast T3 is below Slow T3.
Completed T3 Hull is below Fast T3.
When this happens, Tail Overshoot reports:
|T3 Hull - Fast T3| / ATR
This expresses the size of the overshoot in ATR units.
A value of zero means the completed Hull is not currently beyond the fast T3 under that definition.
This diagnostic is particularly useful when tuning:
Hull Compensation.
Damping Strength.
Fast Length Ratio.
Adaptive VF.
Final Smoothing.
Generalization.
How to interpret the indicator
Rising T3 Hull
A rising line indicates a bullish trend state.
The model’s completed combination of T3 smoothing, Hull compensation and any active damping controls is moving upward.
Falling T3 Hull
A falling line indicates a bearish trend state.
Smooth persistent slope
A stable slope with few direction changes generally indicates a cleaner trend environment for this style of filter.
Frequent colour changes
Rapid bullish/bearish transitions generally indicate:
Sideways price action.
A very responsive configuration.
Insufficient smoothing for the current market.
High normalized curvature
High curvature means the fast T3’s velocity is changing rapidly relative to ATR.
If adaptive controls are enabled, this is where:
Hull compensation may decrease.
T3 Volume Factor may decrease.
High tail overshoot
A larger Tail Overshoot value indicates the completed Hull has moved materially beyond the fast T3.
If the objective is a less tail-heavy line, possible adjustments include:
Reduce Hull Compensation.
Increase Final Smoothing.
Increase Fast Length Ratio.
Increase Damping Strength.
Enable Adaptive T3 Volume Factor.
Reduce or disable Generalization.
Enable the Velocity Limiter.
How to use the indicator
1. Trend regime filter
The most direct use is as a slope-based regime filter:
Rising T3 Hull = bullish trend state.
Falling T3 Hull = bearish trend state.
This can be combined with independent entry logic.
2. Trend transition signals
Long and short markers identify when the adaptive line changes slope direction.
These can be used as:
Regime-change alerts.
Confirmation for another setup.
Potential trailing-exit conditions.
They are not standalone guarantees of a sustained reversal.
3. Pullback reference
During a persistent trend, the T3 Hull can act as a smoothed directional reference.
Price returning toward the line while the line continues to slope in the original direction may represent a pullback within the existing regime.
4. Ribbon expansion
The distance between the current T3 Hull and its delayed WMA reference can visually highlight persistent movement.
A stronger ribbon separation can occur when the current adaptive trend estimate is moving away from its delayed historical reference.
5. Tail tuning
The Data Window diagnostics allow the indicator to be treated as a filter-design tool.
Users can observe:
When compensation is being damped.
How strongly curvature is elevated.
Whether the completed line is overshooting.
How the active T3 coefficient changes.
This can make parameter changes easier to understand than tuning solely by appearance.
Suggested tuning approaches
Smooth / reduced-tail configuration
For a calmer trend line:
Use lower Hull Compensation.
Use a larger Fast Length Ratio.
Increase Final Smoothing.
Enable Adaptive Tail Damping.
Use moderate or higher Damping Strength.
Leave Generalization disabled.
If strong shocks still create large movements:
Enable the Velocity Limiter.
Responsive configuration
For faster behaviour:
Reduce Fast Length Ratio toward the traditional half-length relationship.
Increase Hull Compensation.
Reduce Final Smoothing.
Reduce the Hull Smoothing Exponent.
Use a more aggressive T3 Volume Factor.
These changes generally increase overshoot risk.
Adaptive configuration
For responsiveness in normal conditions with additional protection near turns:
Use moderate Hull Compensation.
Enable Adaptive Tail Damping.
Enable Asymmetric Turn Damping.
Optionally enable Adaptive T3 Volume Factor.
This allows stronger compensation during smooth directional movement while automatically reducing it when the line begins to decelerate or turn.
Maximum tail-control configuration
For very aggressive tail suppression:
Low Hull Compensation.
Higher Final Smoothing.
Adaptive Tail Damping enabled.
Higher Damping Strength.
Adaptive T3 Volume Factor enabled.
Generalization disabled.
Velocity Limiter enabled.
This can create a very stable line, but the cost is additional lag.
How this differs from a standard Hull Moving Average
A conventional HMA normally uses:
WMA at half length.
WMA at full length.
2 × Fast - Slow lag compensation.
Final WMA around sqrt(Length).
Adaptive T3 Hull changes every major part of that architecture:
T3 replaces WMA.
Fast Length Ratio is configurable.
Hull Compensation is configurable.
The final smoothing exponent is configurable.
Final smoothing has an additional multiplier.
Compensation can adapt to curvature.
T3 behaviour can adapt to curvature.
Final movement can be ATR-limited.
An additional generalized compensation stage can be enabled.
It is therefore better understood as a generalized adaptive Hull framework than as a conventional HMA with a different smoothing length.
How this differs from a normal T3
A standard T3 produces one smoothed price estimate from repeated EMA stages and a fixed Volume Factor.
Adaptive T3 Hull uses multiple T3 calculations in a Hull-style structure:
Fast T3.
Slow T3.
Compensated fast-slow projection.
Final T3 smoothing.
It can also dynamically alter the T3 factor according to curvature.
The T3 is therefore a building block inside the larger trend model.
How this differs from simply smoothing an HMA
Applying an additional moving average to an HMA can reduce its tails, but it also adds lag after the overshoot has already occurred.
Adaptive T3 Hull attacks the problem at several earlier stages.
It can:
Reduce the fast-slow separation.
Reduce compensation itself.
Reduce compensation specifically around sharp turns.
Reduce the T3 factor during curvature.
Change the final Hull smoothing geometry.
Limit extreme final movement.
This provides more control than applying one additional smoothing layer to a completed HMA.
Parameter interaction
Many settings interact strongly.
Fast Ratio + Hull Compensation
A low Fast Ratio creates greater separation between fast and slow legs.
Combining that with high Hull Compensation can produce aggressive extrapolation.
Hull Compensation + Adaptive Damping
Hull Compensation defines the maximum starting compensation.
Adaptive damping determines how much of it survives during curvature.
T3 Volume Factor + Hull Compensation
Both can contribute to lag reduction.
High values in both stages may amplify overshoot.
Final Smoothing + Generalization
Final Smoothing adds lag and stability.
Generalization removes some of that lag again.
Using both allows the user to create a smooth base and then selectively reintroduce responsiveness.
Adaptive VF + Adaptive Hull Damping
Both respond to curvature but at different stages.
Enabling both can create strong protection around turns.
Velocity Limiter + all other controls
The Velocity Limiter is applied near the end of the pipeline.
It can therefore override an aggressive target generated by the preceding calculations.
Input guide
Source
Price series used by the complete indicator.
Hull Length
Primary calculation horizon.
T3 Volume Factor
Controls the internal T3 coefficient structure. It does not use trading volume.
Hull Compensation
Controls how much of the fast-minus-slow T3 separation is added to the fast T3.
Final Smoothing
Multiplies the final Hull smoothing length.
Adaptive Tail Damping
Reduces Hull Compensation during high curvature.
Damping Strength
Controls the amount of compensation reduction.
Damping Normalization
ATR horizon used to normalize curvature.
Fast Length Ratio
Controls the fast T3 length relative to the main Hull Length.
Hull Smoothing Exponent
Controls the power-law relationship used to derive the final smoothing length.
Asymmetric Turn Damping
Restricts curvature damping primarily to deceleration and turning behaviour.
Adaptive T3 Volume Factor
Reduces the T3 coefficient during high curvature.
VF Damping Strength
Controls how strongly curvature reduces the active T3 factor.
Minimum VF
Limits how far the adaptive T3 factor can be reduced.
Velocity Limiter
Caps final one-bar T3 Hull movement using ATR.
Max ATR / Bar
Defines the maximum movement allowed by the Velocity Limiter.
Generalize Final Hull
Enables an additional lag-compensation stage after the main T3 Hull.
Generalization
Controls the strength of that final compensation.
Strength-Weighted Gradient
Allows ribbon intensity to vary with normalized T3 Hull velocity.
Strength Smoothing
Smooths the visual trend-strength measure.
Sensitivity
Controls how quickly ATR-normalized movement reaches maximum visual strength.
Band Smoothing
Controls the delayed WMA reference used to build the ribbon.
Strengths
Combines T3 smoothing with a generalized Hull framework.
Directly exposes Hull lag compensation as a user control.
Provides multiple independent methods for reducing oscillating tails.
Uses ATR-normalized curvature for adaptive behaviour.
Can distinguish general curvature from decelerating/turning curvature.
Can adapt the T3 coefficient as well as Hull compensation.
Allows the standard Hull square-root smoothing relationship to be generalized.
Includes an optional ATR-based velocity limiter.
Provides optional final lag compensation for advanced tuning.
Includes real-time tail and curvature diagnostics.
Provides trend-strength-reactive visualization without altering signals.
Limitations
The indicator remains a reactive trend filter rather than a predictive model.
Increasing lag compensation generally increases overshoot risk.
Aggressive tail suppression generally increases lag.
Slope-based signals can whipsaw in ranging markets.
The large number of controls creates many interacting parameter combinations.
Over-tuning parameters to one asset or historical period can reduce robustness elsewhere.
The Velocity Limiter can delay response to genuine price shocks.
Generalization can reintroduce overshoot that earlier damping stages removed.
Trend Strength measures line velocity, not probability of continuation.
Tail Overshoot is a diagnostic relative to the fast T3, not a trading signal.
Causality and real-time behaviour
The calculations use current and historical data without intentional future references.
The indicator can therefore be evaluated causally on completed bars.
However, on a live unfinished candle:
The source can change.
The T3 stages can change.
Curvature can change.
Adaptive compensation can change.
The final slope can change.
A long or short signal can appear or disappear before bar close.
Users requiring confirmed trend transitions should evaluate signals on completed candles.
Alerts
The indicator includes three alert conditions:
T3 Hull Long: the completed T3 Hull changes into a rising trend state.
T3 Hull Short: the completed T3 Hull changes into a falling trend state.
T3 Hull Signal: either directional transition occurs.
Summary
Adaptive T3 Hull is a generalized trend smoother built around the idea that Hull-style lag compensation does not need to be fixed.
The model begins with fast and slow T3 smoothers rather than traditional WMAs. Their difference is used to compensate the fast T3 for lag, but the amount of compensation is directly configurable.
This alone allows the user to move continuously between:
A restrained fast T3.
A partially compensated Hull structure.
A conventional 2×fast-minus-slow construction.
More aggressive extrapolation.
The final smoothing stage is also generalized. Instead of forcing the conventional square-root Hull relationship, the user can control both the smoothing exponent and a separate multiplier.
The adaptive systems then focus specifically on the behaviour that often makes Hull-style smoothers difficult to tune: oscillating tails around sharp turns.
The script measures changes in fast-T3 velocity, normalizes that curvature using ATR, and can use the result to:
Reduce Hull compensation.
Reduce the T3 Volume Factor.
Apply damping only around deceleration and turns.
An optional velocity limiter provides a final ATR-based cap on extreme one-bar movement, while an optional generalized compensation stage can reintroduce controlled responsiveness after the main smoothing process.
The final line determines trend through its slope, while a delayed WMA reference forms the optional ribbon. Ribbon intensity can also respond to normalized trend velocity.
Adaptive T3 Hull is therefore designed less as one fixed moving-average formula and more as a configurable filter architecture for exploring the trade-off between lag, smoothness, responsiveness and overshoot .
Its default configuration intentionally favors a less tail-heavy response than a conventional Hull construction, while the advanced controls allow users to move the model toward either greater responsiveness or stronger damping depending on the behaviour they want from the trend filter.
Indikator

Indikator

Multi-Confirmation Swing IndicatorMulti-Confirmation Swing Indicator is a multi-confirmation technical analysis indicator designed for traders who want to analyze trend direction, momentum, support/resistance, breakouts and potential swing entries from one chart.
Instead of relying on a single indicator, the system combines several independent components to provide a broader view of market structure.
The indicator combines:
EMA trend structure
RSI momentum confirmation
Smoothed Heikin Ashi
Dynamic trendlines with breakout detection
Volume-based support and resistance zones
Zone Shift trend detection
Trend initiation and retest levels
Impulse MACD
Swing BUY/SELL signals
Support/resistance breakout and hold signals
The objective is not to predict every market move, but to help traders determine whether multiple pieces of technical evidence are aligned.
How to Read the Indicator
The easiest way to use the indicator is to think of it as a confirmation system.
Don't treat every individual marker as a trade signal.
Instead, look for confluence.
🟢 Bullish Environment
A stronger bullish setup occurs when several of the following are aligned:
EMA 21 > EMA 55
Price is above the EMA structure.
EMA 21 and EMA 55 are rising.
RSI is above the bullish threshold.
Smoothed Heikin Ashi is bullish.
Zone Shift indicates an upward trend.
Price breaks above a resistance/trendline.
Former resistance begins behaving as support.
Impulse MACD confirms positive momentum.
A BUY signal appears after the above conditions align.
The more confirmations that agree, the stronger the overall technical picture.
🔴 Bearish Environment
A stronger bearish setup occurs when:
EMA 21 < EMA 55
Price is below the EMA structure.
EMA 21 and EMA 55 are falling.
RSI is below the bearish threshold.
Smoothed Heikin Ashi is bearish.
Zone Shift indicates a downward trend.
Price breaks below support/trendline.
Former support begins behaving as resistance.
Impulse MACD confirms negative momentum.
A SELL signal appears after the above conditions align.
Again, the objective is confirmation rather than prediction.
Understanding the Main Components
1. EMA Trend Structure
The EMA component uses three moving averages:
Fast EMA — 9
Trend EMA — 21
Major Trend EMA — 55
The basic interpretation is:
Bullish
Price > EMA 9 > EMA 21 > EMA 55
Bearish
Price < EMA 9 < EMA 21 < EMA 55
This helps identify whether short-, medium- and longer-term momentum are aligned.
The EMA settings can be adjusted from the indicator inputs.
2. RSI Confirmation
RSI is used as a momentum filter.
Default thresholds:
Bullish: RSI > 55
Bearish: RSI < 45
The purpose isn't to simply buy when RSI is high or sell when RSI is low.
Instead, RSI helps answer:
"Is momentum supporting the current trend?"
3. Smoothed Heikin Ashi
The Smoothed Heikin Ashi component attempts to reduce some of the noise present in normal candles.
It can help visually identify:
bullish phases
bearish phases
trend transitions
continuation periods
A series of bullish Smoothed Heikin Ashi candles together with bullish EMA structure provides stronger trend confirmation than either component alone.
Likewise for bearish conditions.
4. Dynamic Trendlines
The trendline component identifies swing highs and swing lows and creates dynamic trendlines from them.
It can identify:
Upward breakout
Price breaks through a descending resistance trendline.
Downward breakout
Price breaks through an ascending support trendline.
The B markers represent detected trendline breaks.
These are useful for identifying potential changes in short-term market structure.
5. Volume-Based Support & Resistance
The support/resistance component identifies potential zones around significant pivot areas while incorporating volume information.
The zones can help traders identify:
potential support
potential resistance
support breaks
resistance breaks
resistance becoming support
support becoming resistance
Example
If resistance is broken:
Resistance → Support
A subsequent successful retest of that level can provide additional bullish confirmation.
Similarly:
Support → Resistance
can provide bearish confirmation after a downside break.
6. Zone Shift
Zone Shift provides another view of the broader trend.
It uses a combination of:
EMA
HMA
price range/distance
trend initiation level
The indicator can switch between bullish and bearish states.
It also identifies potential retests of the trend initiation level.
This can be particularly useful for swing traders because it provides context beyond a single candle.
7. Impulse MACD
Impulse MACD provides an additional momentum layer.
It helps identify:
positive momentum
negative momentum
momentum expansion
momentum contraction
It should not be interpreted independently as a buy/sell system.
Instead, use it as another confirmation layer.
BUY Signal
The BUY signal is designed to appear when the primary swing-trend conditions become bullish.
The underlying logic considers factors such as:
EMA trend
EMA alignment
EMA slope
price position relative to the fast EMA
two-bar confirmation
RSI momentum
The system also prevents repeated BUY labels while the same bullish condition remains continuously active.
Ideal interpretation
Trend + momentum + structure + confirmation = stronger setup
Not:
"BUY label = guaranteed buy."
SELL Signal
The SELL signal works in the opposite direction.
It considers:
bearish EMA trend
bearish EMA alignment
declining EMA structure
price below the fast EMA
two-bar confirmation
RSI weakness
Repeated SELL signals are also filtered.
How I Recommend Using It
Rather than trading every signal, use a 3-stage approach.
Stage 1 — Identify the Trend
First ask:
Is the market bullish, bearish or unclear?
Look at:
EMA 21/55
EMA stacking
Zone Shift
Smoothed Heikin Ashi
If these disagree significantly, consider the market unclear.
Stage 2 — Look for Structure
Once the trend is identified, look for:
support/resistance
trendline breakout
breakout/retest
resistance becoming support
support becoming resistance
This helps avoid entering simply because an indicator changed color.
Stage 3 — Look for Momentum Confirmation
Finally check:
RSI
Impulse MACD
EMA slope
BUY/SELL confirmation
A setup where multiple components agree is generally more interesting than an isolated signal.
Example Bullish Setup
A potential swing-long setup could look like:
1. EMA 21 > EMA 55
↓
2. Price > EMA 9 > EMA 21
↓
3. Zone Shift turns bullish
↓
4. Resistance/trendline breaks
↓
5. Price retests the broken resistance
↓
6. RSI remains above bullish threshold
↓
7. Impulse MACD supports bullish momentum
↓
8. BUY signal appears
This creates a confluence-based setup rather than relying on one indicator.
Example Bearish Setup
The reverse:
EMA 21 < EMA 55
↓
Price < EMA 9 < EMA 21 < EMA 55
↓
Zone Shift bearish
↓
Support/trendline breaks
↓
Retest fails
↓
RSI below bearish threshold
↓
Impulse MACD bearish
↓
SELL signal
Again, this is a framework for analysis—not a guarantee of future price movement.
Best Use Cases
The indicator is primarily designed for:
Swing Trading
Good fit for traders holding positions for several candles to several weeks.
Trend Following
Useful when markets establish clear directional movement.
Breakout Trading
The trendline and support/resistance components can help identify structural breaks.
Breakout Retests
Useful for watching former resistance become support or former support become resistance.
Trend Confirmation
Useful when traders want multiple technical factors visible on a single chart.
What This Indicator Is NOT
This is important for the TradingView publication.
This indicator does not guarantee profitable trades or predict future prices.
It should not be treated as:
financial advice
a standalone automated trading system
a guarantee of trend continuation
a guaranteed entry/exit system
a substitute for risk management
Signals can fail, particularly during:
sideways markets
low-volume markets
sudden news events
high volatility
false breakouts
Always combine the indicator with appropriate position sizing and risk management. Indikator

Signal Pro 6.1Signal Pro 6.1 — Trend Structure, ARSI Market State, and Volatility Breakout Engine
Signal Pro 6.1 is a fully customizable trend analysis and signal engine designed to help traders identify directional momentum, avoid non trending environments, and adapt the indicator to any instrument or timeframe. It combines moving average trend structure, ARSI based market state detection, and Bollinger volatility breakouts to produce a clear, technical view of bullish, bearish, and neutral conditions.
How the Signal Engine Works
Signal Pro 6.1 uses three independent components to validate BUY and SELL signals:
1. Trend Structure (MA1 vs MA2)
Directional bias is determined by two customizable moving averages:
• Bullish Trend: MA1 > MA2
• Bearish Trend: MA1 < MA2
This ensures signals only occur in the direction of momentum.
2. ARSI Market State (Bullish / Bearish / Neutral)
ARSI determines the underlying market condition:
• Bullish State: ARSI > Overbought threshold
• Bearish State: ARSI < Oversold threshold
• Neutral State: Between thresholds
ARSI is a hard filter:
• BUY signals require bullish ARSI background
• SELL signals require bearish ARSI background
• Neutral zones block all trades
This ARSI methodology is inspired by LuxAlgo’s adaptive momentum research.
3. Volatility Breakout (Outer Bollinger Band)
Signals require a volatility expansion:
• BUY: close > upper2
• SELL: close < lower2
This prevents signals during compression and improves trend reliability.
Signal Logic (Matches the Code Exactly)
BUY Signals
Generated only when:
• MA1 > MA2
• ARSI is bullish (background green)
• Close breaks above the outer Bollinger band (close > upper2)
• BUY labels enabled
• In session
• No active position
SELL Signals
Generated only when:
• MA1 < MA2
• ARSI is bearish (background red)
• Close breaks below the outer Bollinger band (close < lower2)
• SELL labels enabled
• In session
• No active position
EXIT Signals
Exits are based on price crossing MA1:
• Long Exit: close < MA1
• Short Exit: close > MA1
This keeps exits responsive and avoids lag.
Recommended Default Settings (Based on Author Back Testing)
These settings provide a balanced, responsive structure suitable for most markets:
ARSI Settings
• ARSI Length: 10 (acceptable range 10–14)
• ARSI Signal Length: 3 (acceptable range 3–8)
• ARSI Overbought: 60 (acceptable range 50–70)
• ARSI Oversold: 40 (acceptable range 30–50)
Moving Averages
• MA1: EMA 8
• MA2: EMA 13
• MA3: EMA 50
• MA4: EMA 200
• MA5: EMA 500
These values create a clear trend hierarchy and help visually confirm directional bias.
Trend Alignment and MA Stacking
Although the indicator generates signals automatically, traders should also pay attention to the broader trend structure. Strong trends often show:
• EMA 8 > EMA 13 > EMA 50 > EMA 200 (bullish stacking)
• EMA 8 < EMA 13 < EMA 50 < EMA 200 (bearish stacking)
When moving averages are stacked cleanly and fanning out, trend strength is high. When they compress or cross repeatedly, the market is entering a range and signals become less reliable.
Signal Pro intentionally reflects this visually: trending markets appear clean and aligned, while range bound markets become noisy. This is a built in warning system.
Customization Is Required
Signal Pro 6.1 is not intended to be used “out of the box.” It is a modular system that must be configured for the specific instrument, timeframe, and trading objective.
Users can customize:
• Moving averages (type, length, visibility)
• Bollinger Bands (inner/outer, multipliers, lengths)
• ARSI thresholds and methods
• Background shading
• Candle colors
• Trend colors
• Session windows
• BUY/SELL/EXIT label visibility
• Momentum circles
• Chart clutter level
Because of this flexibility, the indicator may not look correct until properly tuned. Once configured, it becomes a stable and reliable trend clarity tool.
Versatility Across Markets
With correct settings, Signal Pro 6.1 can be used for:
• Futures scalping
• 0DTE options
• Intraday stock trading
• Swing trading
• Crypto
• Forex
There are no restrictions on where it can be applied. The key is adjusting the session window, timeframe, and indicator parameters to match the behavior of the chosen market and back testing accordingly.
Summary
Signal Pro 6.1 combines trend direction, ARSI market state, and volatility breakout logic to highlight high probability directional moves and warn against trading in non trending environments. Every component — moving averages, bands, colors, signals, and market state filters — is fully customizable, allowing traders to adapt the indicator to any market or timeframe.
Indikator

Trend Signal A (v2.3) - 1D Trend + 1H CrossThis indicator combines multi-timeframe trend analysis using Heikin-Ashi candles
smoothed with a configurable moving average (EMA, HMA, ALMA, SMA, etc.).
📌 How it works:
- Calculates trend on a higher timeframe (Daily by default) using the last
CLOSED Heikin-Ashi candle only (no repainting).
- Looks for a trend cross confirmation on the chart's timeframe (designed for 1H).
- BUY signal: daily trend is bullish + bullish cross on the current timeframe.
- EXIT signal: bearish cross OR ATR-based dynamic stop loss, whichever comes first.
📊 Built-in panel:
Shows in real time the daily trend state, whether a position is currently open,
the unrealized PnL of the open trade, and the cumulative historical PnL
(simulated, no fees/slippage) since the indicator was loaded on the chart.
⚙️ Fully configurable: moving average type and length, higher-timeframe
selection, ATR multiplier for the stop loss, colors, and panel visibility.
⚠️ This script is an analysis tool, not financial advice. Past results shown
in the panel do not guarantee future performance. The PnL displayed is a
simplified simulation for educational purposes, not a full strategy backtest
(no fees, slippage, or position sizing are accounted for).
🙏 Credits: based on "Trend Indicator A" by DZIV (dzi_v_), published under
CC BY-NC-SA 4.0. This script is released under the same license. Indikator

Scalp Lite + CHoCHSCALP LITE + CHoCH
WHAT THIS IS
Two independent trade engines running on one chart, sharing a single dashboard.
One trades moving-average crosses with volatility-scaled risk. The other trades
breaks of market structure with structure-scaled risk. They are not blended into
a combined signal - they run side by side and are allowed to disagree, because
the disagreement is the most useful thing the script produces.
ENGINE 1 - SCALP LITE (EMA 9 / EMA 50)
The trigger is EMA9 crossing EMA50, filtered by any combination of VWAP side,
above-average volume, a trading session window, and a cooldown between signals.
The part worth explaining is the deferred cross, because it fixes a failure mode
that is easy to miss. A crossover is a single-bar event, and ta.crossover() never
fires again while the two averages stay on the same side of each other. A naive
implementation requires every filter to pass on that exact bar - so a cross that
happens premarket, on thin volume, or outside your session window is discarded
permanently, and the script shows nothing while price trends all day.
Here, a cross ARMS a direction instead of consuming it. The signal fires on the
first later bar where every enabled filter passes AND the averages still agree
with the armed direction. Nothing is bypassed; the filters simply no longer have
to pass simultaneously on one specific bar. An opposite cross overwrites the
pending direction, so a stale arm cannot survive a reversal. The dashboard shows
which filter is currently blocking an armed signal.
Levels are ATR multiples from the entry close: stop at 0.75 x ATR, TP1 at 1 x
ATR, TP2 at 2 x ATR, all adjustable. A separate warning fires when EMA9 crosses
the 20-period SMA against an open position, which flattens the signal state.
ENGINE 2 - CHoCH (CHANGE OF CHARACTER)
Swing highs and lows are located with pivots. The left-bar setting is a
significance filter and costs nothing; the right-bar setting is confirmation lag
and is the only real cost, since a swing is not confirmed until that many bars
have printed after it.
A structure break requires a CLOSE beyond the swing by a minimum ATR distance,
not merely a wick through it. That break arms the engine. With pullback mode on
(default), entry then waits for price to trade back to within a small ATR buffer
of the broken level and close back on the correct side of it - a retest, not a
chase. If that does not happen within a set number of bars, the arm expires
unused. Filters for EMA agreement, VWAP side, volume and session apply on top.
Risk is structural, not volatility-based. The stop goes just beyond the swing
that defined the structure, because that is where the trade thesis is actually
wrong. R is the distance from entry to that stop, and both targets are multiples
of R. Optional breakeven move after TP1.
Structure direction is held in a latch that survives until something changes it.
Two guards keep that latch honest: it resets to neutral the moment price closes
back through the level it broke - a break price has closed back inside is a
failed break, not structure - and the dashboard shows how many bars old the
surviving break is, greying out the agreement mark once it passes a staleness
threshold. Without those, a latch reads as confidently bullish an hour after the
break that set it has stopped mattering.
WHY THESE TWO TOGETHER
They fail in opposite conditions, and each one's failure is the other's normal
operating range.
A moving-average cross system is structurally late at turns and comfortable in
trends. A structure-break system is early at turns and gets cut up in range-bound
conditions. Running one of them tells you what it thinks. Running both tells you
whether the answer is worth much: when a late-but-reliable method and an
early-but-noisy method point the same way, that is a different situation from
either one agreeing with itself.
The second reason is risk framing. The two engines size stops on incompatible
principles - one steps back a fixed volatility multiple, the other steps behind
the structure. When those two stops land near each other, volatility and
structure agree and the setup is clean. When they are far apart, the structure
was built during a fast move and the trade genuinely needs a wider stop than a
scalp framework would suggest. You cannot see that from either engine alone, and
it is not something a combined signal could express - which is why they are kept
separate rather than merged.
The BIAS row is the product of that design. It is not a third signal; it is an
agreement meter with an age stamp on the structural half.
RUNNER MODE
By default, price tagging TP2 does not end the trade. The whole level set rolls
forward one leg: the stop ratchets up to the target just cleared, old TP2 becomes
the new TP1, and a fresh TP2 is set one full leg further out. This repeats for as
long as the move runs, so the levels stay near live price instead of sitting
behind it. A leg counter on the dashboard shows how many rolls have occurred.
The ratchet can follow the prior target, the fast EMA, an ATR trail, or be
disabled.
CONTEXT LAYERS
Fair value gaps (three-bar imbalances, drawn as zones, removed when filled),
opening range with breakout state, previous day high/low, daily pivots, confirmed
and pending trendlines, higher-timeframe trend on two timeframes, RSI on the
chart timeframe and a higher one, VWAP, and a 200 EMA.
Every forward-drawn line is redrawn each bar starting at the current candle and
projected a fixed distance right, rather than painted back across history. Scalp
Lite's levels are dashed and CHoCH's are solid so the two sets are never
confused when both engines are in a trade at once.
DASHBOARD
Twelve rows: agreement bias with structure age, each engine's state, entry, stop,
targets with leg counter, RSI on two timeframes, volume and ATR, higher-timeframe
trend, nearest unfilled gaps, opening range state, and warnings. Position is
adjustable to any of nine anchors, with text size and a compact single-column
mode for smaller panes.
HOW TO USE IT
Intraday timeframes; the defaults are tuned for 1 to 5 minute charts.
Read the BIAS row first. Both engines agreeing with a fresh structure break is
the highest-quality condition the script identifies. Disagreement is a reason to
size down or stand aside, not a signal to fade. Check the opening range row - an
INSIDE reading is the chop regime where structure breaks fail most often.
If CHoCH's targets look impractically far away, that is the structural stop
telling you the nearest confirmed swing is a long way from price. Reducing the
pivot left-bars finds nearer structure and shrinks R honestly. There is also an
optional cap on stop distance, off by default, which shrinks R by moving the stop
somewhere structure does not justify - it makes the chart tidier and the logic
worse, which is why it ships disabled.
BEHAVIOUR AND LIMITATIONS
Swings require confirmation bars before they are recognised, so structure appears
after the fact by design. This is inherent lag, not repainting: a confirmed swing
never moves afterwards.
Scalp Lite signals evaluate on bar close. CHoCH conditions evaluate on the
current bar and can therefore change state intrabar until that bar closes; treat
an intrabar CHoCH signal as provisional.
Alerts are provided for both engines' entries, the exit warning, opening range
breaks, and structure breaks.
This is a decision-support tool. It reports what price, structure, volatility and
participation are doing - it does not forecast, and neither the signals nor the
targets are predictions. Defaults are starting points, not recommendations, and
will need adjusting per instrument and timeframe. Position sizing and the
decision to take or skip any setup remain entirely with the user. Nothing here is
financial advice. Indikator

Indikator

Average RSI | TR🔍 OVERVIEW
The Average RSI is a next-generation momentum oscillator that goes beyond the standard Relative Strength Index. Instead of relying on a single timeframe, it calculates the RSI across three distinct daily cycles (1 Day, 2 Days, and 3 Days) and averages them into one smooth, highly responsive signal.
This multi-timeframe averaging drastically reduces market noise, filters out false divergences, and provides a holistic view of the short-to-medium term momentum structure. Combined with a dedicated dynamic moving average, it acts as both a trend filter and an early entry/exit system.
⚙️ HOW IT WORKS
1. RSI Computation:
The script calculates the classic RSI of your chosen source (default: Close) for the 1D, 2D, and 3D timeframes.
2. The Average (AVG_RSI):
It takes the arithmetic mean of these three values. This "composite RSI" is the core line you see plotted on the chart.
3. The Trend Filter (MA_AVG_RSI):
A fully customizable Moving Average (default: EMA, Length: 275) is applied to the AVG_RSI. This acts as the "Zero Line" of the indicator:
• AVG_RSI > MA_AVG_RSI → Bullish Bias
• AVG_RSI < MA_AVG_RSI → Bearish Bias
🎨 VISUAL FEATURES & SIGNALS
• Dynamic Trend Coloring:
The main line, candles, and chart background dynamically shift colors based on a normalized gradient of the AVG_RSI, making trend strength instantly recognizable.
• Smart Gradient Fills:
Ribbon Fill: The area between the AVG_RSI and its Moving Average is filled with the trend color. Its transparency adjusts automatically based on price momentum—more opaque during strong trends and faint during consolidation.
Overbought/Sold Zones: Gradient fills between the AVG_RSI and the 50-level are activated only when the AVG_RSI extends beyond the Moving Average. This unique logic prevents misleading extreme-zone signals during trend reversals.
• Entry/Exit Signals (Triangles):
LONG (⬆️): A green triangle appears below the bar when AVG_RSI crosses ABOVE the MA_AVG_RSI.
SHORT (⬇️): A red triangle appears above the bar when AVG_RSI crosses BELOW the MA_AVG_RSI.
• Heads-Up Display (HUD):
At the last bar, a large table displays the current market bias (Bullish/Bearish), and a floating label shows the precise AVG_RSI value.
🎛️ INPUT CONFIGURATIONS
• RSI Length: Adjust the sensitivity of the RSI calculation (Default: 44).
• Source: Choose the base source for the RSI (Default: Close).
• Moving Average Engine: Select from 12 different MA types, including EMA, SMA, WMA, HMA, DEMA, TEMA, TRIMA, FRAMA, SWMA, and T3 (with adjustable T3 Factor).
• MA Length: Set the smoothing period for the trend filter (Default: 275).
• Color Palettes: Choose from 9 distinct visual themes—Classic, Modern, Heat, Robust, Accented, Monochrome, Moderate, Aqua, or Cosmic—to match your charting style.
🚨 ALERTS
Built-in alert conditions are ready to use:
• LONG: Triggered on a Bullish crossover.
• SHORT: Triggered on a Bearish crossunder.
💡 BEST USE CASES
• Swing Trading: Identify shifts in mid-term momentum.
• Trend Confirmation: Use the MA filter to avoid entering trades against the dominant flow.
• Divergence Spotting: The smoothed nature of AVG_RSI makes chart patterns and divergences much clearer than with standard RSI.
📌 Note: This indicator works on any asset (Crypto, Forex, Stocks, Commodities) and any timeframe, as the underlying MTF logic is anchored to the daily RSI structure. Indikator

Adaptive MA Ribbon [StrixEDGE]📊 WHAT IT DOES
StrixEDGE Adaptive MA Ribbon plots three of the most advanced low-lag moving averages — Hull MA, Arnaud Legoux MA, and Kaufman Adaptive MA — with automatic period adjustment based on current volatility. A consensus score (0-6) instantly shows whether all three agree on trend direction.
🔬 WHY IT'S DIFFERENT
Traditional MA ribbons use fixed periods that work in one market condition and fail in another. This ribbon automatically shortens its period when volatility spikes (for faster reaction) and lengthens it when markets are calm (to avoid whipsaws). The three MAs used — HMA, ALMA, and KAMA — are specifically chosen because each adapts to the market differently, so their agreement carries more weight than three similar MAs agreeing.
⚙️ HOW IT WORKS
The volatility ratio (current ATR / 50-period average ATR) dynamically adjusts the base period. This adjusted period feeds into all three MAs simultaneously. The consensus score counts two things: how many MAs are below price (0-3 points) and how many are rising (0-3 points). A score of 6 means all three MAs are below price AND rising — the strongest possible bullish configuration.
📈 HOW TO USE
• Consensus 5-6 (green fill): Strong uptrend — buy pullbacks to the ribbon
• Consensus 0-1 (red fill): Strong downtrend — sell rallies to the ribbon
• Consensus 2-4 (gray fill): Mixed — avoid trend strategies
• Diamond markers at consensus flips = key entry/exit signals
• Ribbon twist (MAs crossing) = early warning of trend change
• Works best on 4H and Daily timeframes
🎛️ INPUTS & DEFAULTS
Base Period: 21 | Min: 8, Max: 55 | ALMA Offset: 0.85, Sigma: 6.0
═══════════════════════════════════════════════════════
🔧 CUSTOMIZATION
All parameters are fully adjustable through the indicator settings panel. Inputs are grouped logically:
• ⚙️ Core Parameters — main calculation settings
• 📊 Table Settings — table size (Tiny to Huge), position (4 corners), visibility toggle
• 🎨 Visual Settings — colors, show/hide elements
• 🔔 Alert Settings — threshold values for notifications
📊 DATA TABLE
A built-in data table displays all key metrics in real-time. Adjust the table size from Tiny to Huge to match your chart layout. Position it in any corner. Toggle visibility on/off.
🔔 ALERTS
Pre-built alert conditions for all major signals. Set up alerts via TradingView's alert dialog — select this indicator and choose from the available conditions.
⏱️ RECOMMENDED TIMEFRAMES
Works on all timeframes. Recommended: 1H, 4H, Daily for best signal quality. Lower timeframes produce more signals but with higher noise. Weekly/Monthly for position trading context.
✅ COMPLIANCE
• No repainting — all signals based on confirmed bar close data
• No future data references
• Open-source code — verify the logic yourself
⚠️ DISCLAIMER
This indicator is a technical analysis tool, not financial advice. It does not predict future price movements. Past patterns and signals do not guarantee future results. Trading involves substantial risk of loss. Always use proper risk management, including stop losses and appropriate position sizing. Never risk more than you can afford to lose. Indikator

The Ultimate 50 EMA @JustinPerezTradesUltimate Day Trader — NQ/MNQ Multi-Timeframe 50 EMA Stack
A precision pullback/breakout indicator for NQ and MNQ that only signals when five timeframes of 50 EMAs are stacked in trend order.
Overview
This indicator looks for a specific structural setup on NQ and MNQ futures: a short-term pullback (or push) away from the 1-minute 50 EMA that occurs while the 50 EMA is climbing or falling in a clean, ordered stack across five timeframes (1m, 5m, 10m, 15m, 30m). The idea is to only trade pullbacks that are happening inside a confirmed multi-timeframe trend, rather than reacting to the 1-minute chart in isolation.
It's a signal/alert tool — it plots the EMA stack, marks entries and the exit target on the chart, and can fire alerts. It does not place trades for you.
How it works
Long setup — all of the following must be true at once:
Price is 50–100 points below the 1-minute 50 EMA (a pullback into value, not a full trend break)
5-minute 50 EMA is above the 1-minute 50 EMA
10-minute 50 EMA is above the 5-minute 50 EMA
15-minute 50 EMA is above the 10-minute 50 EMA
30-minute 50 EMA is above the 15-minute 50 EMA
When all five conditions align, the script marks a long entry. The exit target is the 30-minute 50 EMA — the trade is considered closed once price trades up to reach it.
Short setup is the mirror image: price 50–100 points above the 1-minute 50 EMA, with each higher timeframe's 50 EMA stacked below the one before it (5m < 1m, 10m < 5m, 15m < 10m, 30m < 15m). Exit target is the same 30-minute 50 EMA, reached from above.
Entries are edge-triggered — you get one signal per fresh setup, not a repeated marker on every bar the condition happens to remain true.
How to use it
Apply the indicator to a 1-minute chart on NQ or MNQ (front-month continuous contract or a dated expiry). The script checks both conditions and shows a warning label if either isn't met.
Watch the on-chart status table for a live read of: chart/symbol validity, current position state (flat / in long / in short), whether the MTF stack is bullish, bearish, or unaligned, the price's distance from the 1m EMA, and the current exit target level.
Green up-triangles mark long entries, red down-triangles mark short entries; a background tint confirms when the broader EMA stack is aligned even before price reaches the entry zone.
Right-click the chart → Add Alert to get notified on Long Entry, Short Entry, Long Exit, or Short Exit independently.
Inputs
EMA Length — default 50, applies to all five timeframes
Min / Max entry distance from the 1m EMA (points) — default 50 / 100, tuned for NQ/MNQ's typical point range
Restrict signals to NQ/MNQ only — on by default; disable to experiment with the same logic on other instruments
Higher timeframe overrides — 5m/10m/15m/30m are adjustable if you want to test alternate spacing
Display toggles for the EMA plots, stack-aligned background highlight, and the status table
Notes
This script is built BY @JustinPerezTrades specifically around NQ and MNQ's point behavior — the 50–100 point entry zone will not translate directly to instruments with different average ranges. It is a rules-based signal tool, not a guaranteed-profit system, and past alignment of these conditions does not predict future results. Backtest and paper-trade before using it with real capital, and use it alongside your own risk management. Indikator

EMA Ribbon + Smoothed RSI Trend StrategyEMA Ribbon Trend Filter + Smoothed RSI Entry Strategy
BEST IS 1/1RR
Overview
This strategy combines a moving-average trend filter with a smoothed RSI trigger to time entries in the direction of an established trend, with stop-loss levels placed at real market structure rather than a fixed distance.
How it works
1. Trend Filter (Ribbon)
An EMA(10) and EMA(20) are plotted on the chart. The strategy only considers trades when EMA(10) is above EMA(20) — treated here as confirmation of underlying bullish structure. Two additional SMAs (20/50) are plotted alongside for visual context but aren't part of the trade logic.
2. Entry Trigger — Smoothed RSI
Rather than using raw RSI, this script smooths RSI(21) with a 50-period SMA. That smoothed line is the actual decision value:
Crosses above 51 → long signal
Crosses below 49 → short signal
Smoothing the RSI this way filters out a lot of the noise a raw RSI produces, at the cost of some lag.
3. Structure-Based Stop Loss
Instead of a fixed pip/point stop, SL is placed at the nearest swing low (for longs) or swing high (for shorts) over a configurable lookback window, plus a small buffer. Take-profit is set as a configurable risk:reward multiple of that stop distance.
4. Trade Visualization
Every trade taken draws two boxes on the chart: a green "profit zone" from entry to TP, and a red "risk zone" from entry to SL. These extend in real time while the trade is open, so you can see the live risk/reward geometry of each position at a glance.
5. Non-Repainting
Signals only evaluate on confirmed, closed bars (barstate.isconfirmed), so what you see in the backtest is what would have fired in real time — no mid-bar flip-flopping.
Inputs
EMA/SMA ribbon lengths (default 10/20/20/50)
RSI length and smoothing length (default 21 / 50)
Buy/sell trigger levels (default 51 / 49)
Cross-only trigger toggle
Swing lookback, SL buffer, minimum SL distance
Risk:reward ratio 1/1 IS BEST
Box colors and visibility toggle
Optional date range filter for backtesting
Alerts
Built-in alertcondition() calls for both long and short signals, ready to connect to a webhook or notification service if you want to act on signals outside of TradingView.
⚠️ Disclaimer: This script is provided for educational and informational purposes only. Past performance shown in backtests does not guarantee future results. Backtest results can be affected by commission/slippage assumptions and do not account for real-world execution factors such as liquidity and order rejection. This is not financial advice — use proper risk management and test thoroughly before trading with real capital. Strategi

TURKS Engine - Tiered Unit Risk KernelMost position-sizing tools tell you what to hold after the move. This one tells you the price at which it changes, before price gets there.
TURKS Engine decides how much of a long position to hold. Exposure is a graded function of where the close sits against four moving averages, so it moves in rungs rather than switching on and off. That function is monotone in price, which means it inverts: every rung has exactly one price. The panel solves for those prices and prints them today — a ladder of levels at which the position gets larger or smaller, readable now.
Long only, 0 to 1. No shorting, no leverage, nothing resting at a broker.
This is the indicator build of TURKS. Same engine, no orders — it sizes, you execute.
📊 WHAT THE LADDER DID
Twelve symbols, shipped defaults, 4-hour charts, full available history. Commission $1.50 per order, slippage 0.01xATR per side, idle cash credited nothing. b&h is buy-and-hold over the identical bars, charged nothing at all. The comparison is deliberately rigged against the engine.
SCOREBOARD 12 symbols, 4h, full history, net of costs
maximum drawdown cut versus buy and hold .......... 12 of 12
CAGR / maxDD better than buy and hold .......... 7 of 12
CAGR better than buy and hold .......... 3 of 12
TURKS versus BUY AND HOLD, sorted by CAGR
CAGR MAX DRAWDOWN CAGR / maxDD
symbol sample TURKS b&h TURKS b&h TURKS b&h
SNDK 1.3y +1406.3% +1899.0% -37.2% -56.8% 37.82 33.43
ETH 9.5y +117.3% +71.9% -54.4% -94.1% 2.16 0.76
BTC 9.5y +70.0% +54.2% -62.3% -83.9% 1.12 0.65
ARM 2.7y +62.5% +72.9% -39.8% -55.8% 1.57 1.31
TSLA 15.9y +32.7% +41.7% -57.0% -74.9% 0.57 0.56
NVDA 22.4y +25.3% +36.4% -77.0% -85.2% 0.33 0.43
AMD 21.4y +20.2% +17.3% -69.3% -96.1% 0.29 0.18
AVGO 16.8y +16.9% +39.0% -36.9% -50.3% 0.46 0.78
MU 22.4y +9.3% +19.7% -81.4% -90.9% 0.11 0.22
GOLD 13.5y +7.2% +7.7% -20.0% -35.0% 0.36 0.22
SPY 20.4y +4.4% +9.1% -40.5% -56.7% 0.11 0.16
INTC 20.4y +2.2% +8.5% -73.3% -74.2% 0.03 0.11
CAGR / maxDD is the column that settles it — return earned per unit of drawdown suffered. On that measure the engine wins on 7 of 12. It cut maximum drawdown on 12 of 12, and beat buy-and-hold on raw return on 3.
▸ ETH — 117.3% against 71.9%, at −54.4% drawdown against −94.1%. Nearly double the return on barely half the pain.
▸ BTC — 70.0% against 54.2%, at −62.3% against −83.9%.
▸ AMD — 20.2% against 17.3%, turning a −96.1% hole into −69.3% across 21.4 years.
These are assets that spent their entire sample inside a historic bull market, measured against a benchmark paying no commission and no slippage. Halving a drawdown is ordinary. Halving it and finishing ahead is not.
Every one of those numbers comes from the BOOK panel in this script. There is no separate research harness behind them and no second, gross set of figures anywhere in the build. Load it on your own symbol and the whole table regenerates for that instrument in one bar, net of the costs you typed in.
The table was measured on 16 August 2026. A live chart keeps adding bars, so the panel will not read exactly these numbers — at the time of writing ETH has drifted to 122.3% against 76.1%. Read the panel, not the table, for what the engine is doing on your instrument today.
📖 HOW TO USE IT
1 — Set your costs first. Commission ($ per order) and Typical position size ($) are the only two numbers the cost model needs; every other cost figure is a rate derived from them. A flat $1.50 is 1.9bp on an $8,000 position and 7.5bp on a $2,000 one. Leave these wrong and the panel lies to you.
2 — Pick the instrument. Single names and crypto whose drawdowns are violent relative to their drift. The table above is the guide, including the four rows that say don't.
3 — Read the ladder, not the arrows. The SELL / BUY ENGINE block prints three live numbers:
▸ Sell next above — the price at which the next rung comes off
▸ Buy back below — the price at which it goes back on
▸ Rungs sold — how much the envelope has already taken off, e.g. *12 of 20*
Both prices exist now, before the move. They are not marks that appeared after one.
4 — Read the dial. THE RULE prints Target weight — what the rule says you should be holding at this instant — and Dial c / f. POSITION prints the modelled book: weight held, average cost, open return, and the round-trip cost that position is carrying, so the gap between intention and position is always visible.
5 — Size it with c and f, not by fighting the rungs. c scales the whole position down. f is the floor you keep while the rule is off; raising it walks the book continuously toward buy-and-hold. Both tooltips print the measured frontier — the whole curve of what each step costs in return and buys in drawdown, including the region where the rule loses to simply holding less.
6 — Check it on your own symbol before trusting any of it. BOOK prints Sample, CAGR against b&h, Max drawdown against b&h, CAGR/maxDD, Sharpe, Exposure and Turnover. BOOK LEDGER, bottom right, prints the same book in money: book value against buy-and-hold from the same start, spells closed, profit factor, worst run, open position.
🔔 ALERTS
Five named conditions in the alert dialog — Target weight changed, Weight added, Weight cut, Gate on, Gate off — plus a rich alert() message carrying the weight it moved from, the weight it moved to, and both envelope prices. Flip one checkbox and the same payload arrives as JSON for a webhook.
🪜 HOW THE EXPOSURE IS SET
Exposure Shape picks the weighting rule. *Ensemble 20/50/100/200 (graded)* is the default. Each of the four SMAs contributes its own 0-to-1 ramp as price clears it, scaled in ATR and widened for the longer means so a 200-day cross is not treated like a 20-day one. The four ramps are averaged, then rounded to the nearest third:
SMA 20 ramp 0..1 ---+
SMA 50 ramp 0..1 ---+
SMA 100 ramp 0..1 ---+-- average -- round to thirds -- 0 / 33% / 67% / 100%
SMA 200 ramp 0..1 ---+
Four reachable weights, three thresholds, and the panel prints the price of all three. *Graded (continuous)* uses one mean with an ATR ramp instead. *Binary gate (legacy)* is the original all-or-nothing rule, kept so the graded version has something to be measured against.
Risk dial c scales the entire position down. Risk dial f is how much you keep while the rule is off. These two are the real levers, and nothing about their trade-off is hidden — the full measured frontier is printed in the settings dialog, the losing region included.
Quantise Steps rounds the target to N reachable weights and requires price to clear 75% of a step before acting, so the weight does not twitch every bar. Ramp Width (xATR) sets how far above the mean price must travel to earn full size.
✂️ THE NADARAYA-WATSON SELL ENGINE
A trend weight cuts into weakness by construction, so it sells low: 59% of every unit the dial sells goes out below its own average cost, at 12.4 round trips a year. That is the flaw this block exists to fix. It replaces or constrains the sell side with a Gaussian kernel-regression envelope that only sells into genuine extension.
Sell Engine Mode — *Dial, NWE-gated* (default) keeps the dial's targets but forbids cutting while price sits below the smoother; it may still add. *NWE band only* turns the dial's sells off entirely. *Dial + NWE (both cut)* lets either one sell. *Dial only* leaves the envelope drawn but inert.
Sell Rungs is how much leaves on each upper-band cross: 1/N of the position. Going from 3 to 10 halved turnover, cut the share sold below basis from 16.7% to 8.9%, and pulled out-of-sample drawdown from −32.6% to −18.3%. It ships at 20, one step further along the same gradient; 10 is the last value with a formal table behind it.
Band Multiplier (3.0) and Buy-back Multiplier (2.5) set the upper and lower halfwidths in mean-absolute-deviation units. The asymmetry is the point: buying back nearer the mean than you sold restores the position before price has fully round-tripped, which is what keeps the overlay from bleeding in a chop. Bandwidth h widens and slows the smoother; it ships at 5.
🔬 HOW THIS WAS BUILT
Nine candidate signal families were tested against a matched-exposure control across 140 markets and 8,793 sessions: moving-average and momentum structure, cross-sectional relative strength, short-horizon mean reversion, volatility-of-volatility and regime transitions, drawdown state, volume, range compression, multi-timeframe agreement, and calendar seasonality. Not one was positive both in and out of sample. All nine were deleted from the codebase rather than left in as decoration.
The cleanest demonstration: take the original engine's own weight path and fire it 60 trading days late — same trades, same sizes, same turnover, same average exposure, only the dates broken. It scores better late than on time. Block-shuffling the path also beats it. A rule whose dates carry information cannot survive having them destroyed, so that engine was removed and what remains is geometry.
The stretch-proportional alternative to fixed rungs was then built and measured across 44 configurations. None beat rungs = 10. The project's pre-registered five-clause acceptance test passed all 20 graded cells — but a constant weight of 1.0 also passes three of five clauses, exactly one cell of twenty reaches p < 0.05 uncorrected (the null expectation for twenty tests), that p fails Bonferroni, and the cells are 0.985-correlated. It was reported as a failed test.
Everything left in this script survived a process designed to kill it. What remains is a sizing rule with no forecast in it: it does not predict the retest, it tells you at a price you can read now exactly what happens when one arrives.
⚙️ COSTS, AND THE SETTINGS THAT DECIDE THEM
Sell Engine Mode *Dial, NWE-gated*, Exposure Shape *Ensemble 20/50/100/200 (graded)*, c = 1.00, f = 0.00, Quantise Steps 3, Ramp 1.0 ATR, Trend Mean 200, Cash Yield 0.00%. Envelope: bandwidth 5, multiplier 3.0, buy-back 2.5, MAE window 499, Sell Rungs 20. Book notional 150,000, commission $1.50 cash per order, slippage 0.01xATR per side.
Slippage is charged in ATR units rather than ticks, because a tick is an absolute price and one tick count cannot be simultaneously correct for a $20 stock and a $1,600 one, nor for the same stock at $0.21 and at $224. A fraction of the instrument's own range travels between symbols; a tick count does not.
Cash Yield ships at 0.00%. The rule spends much of its life partly in cash, so any yield credited lands straight on the CAGR, and one constant cannot represent a twenty-year sample where real cash paid about 0.1% for eight years and about 5% for two. Every figure in the table above was measured with it at zero.
Exits are close-only by construction. The printed ladder is the memoryless level; the live quantiser is hysteretic, so the executed switch can sit up to 0.75 steps from the printed one.
🔁 THE STRATEGY BUILD
The same engine with orders attached is published separately as TURKS — Tiered Unit Risk Kernel Strategy, for anyone who wants the Strategy Tester's own accounting as a second opinion on the panel. Both builds compute the ladder, the envelope and the BOOK ledger from identical code.
© CREDIT
The envelope is a port of "Nadaraya-Watson Envelope " by LuxAlgo (www.tradingview.com), published open source under CC BY-NC-SA 4.0. The kernel, the MAE band construction and the crossover logic are theirs. This script is published under the same licence.
Only the non-repainting, one-sided causal branch was ported. LuxAlgo's script defaults to the repainting branch, which rebuilds its curve inside barstate.islast with a two-sided kernel, so the value at bar i averages bars on both sides of i — including bars that had not happened when i closed. That branch is deliberately absent here. The measured gap between the two is about 21% of the band halfwidth, which is why the repainting version's arrows look cleaner than any live rule can be. The sizing, the rung logic and the position accounting are new.
Open source, Pine v6.
Indikator

TASC 2026.09 Adaptive SuperSmoother█ OVERVIEW
This script implements the Adaptive SuperSmoother by John F. Ehlers, as presented in the "Improved Filter Performance" article from the September 2026 edition of the TASC Traders' Tips . The script demonstrates a simple technique to adapt the SuperSmoother's critical period to improve the filter's responsiveness.
█ CONCEPTS
In his article, Ehlers explains that many adaptive smoothers rely on Exponential Moving Averages (EMAs) at their core. Typically, these smoothers dynamically adjust an EMA's smoothing factor (alpha) based on specific volatility measures, often to reduce sensitivity during periods of volatile or choppy price movements. However, he suggests that EMAs are not great filters; they are first-order smoothers that offer very limited reduction, or attenuation, of high-frequency (low-period) signals in the dataset. For example, for an EMA with a critical period of 12 bars, the maximum gain reduction of smaller-period cycles is only about -17 decibels (dB). At this level of attenuation, a significant amount of high-frequency noise remains in an EMA-filtered series.
Ehlers proposes that traders should use the SuperSmoother instead of an EMA in most applications, including adaptive filtering. The SuperSmoother is a second-order filter. It has a second-degree polynomial in its transfer function and a zero of transmission at the Nyquist frequency . Thanks to these characteristics, the SuperSmoother offers a substantially greater reduction of higher frequencies than an EMA. Additionally, Ehlers notes that the filter's computational lag is not perceptibly greater than that of an EMA, further underscoring its usefulness as an improved filter.
Ehlers notes that there are many ways to make the SuperSmoother adaptive to market conditions. He demonstrates his preferred method, dubbed the Adaptive SuperSmoother , in the article's code. Rather than tuning the smoothing factor of an EMA based on a volatility measure, the Adaptive SuperSmoother dynamically adjusts the critical period of one SuperSmoother based on the rate of change (ROC) in another. The steps to calculate the filter are as follows:
Calculate a SuperSmoother filter using a fixed critical period.
Measure the one-bar ROC in the first filter, and calculate the RMS (Root Mean Square) of the result over a specified length (81 bars by default, as per the article).
Scale the ROC by the RMS, and limit the maximum scaled value to 2.
Calculate the factor for adjusting the final filter's period. The value is the square of one minus half of the scaled ROC.
Multiply the first filter's period by the factor from step 4, then limit the result to a minimum value of 2, to calculate the adaptive period.
Calculate a separate SuperSmoother using the adaptive period from step 5. This filter is the Adaptive SuperSmoother.
The resulting filter dynamically reduces its critical period to increase responsiveness when changes in the fixed-period SuperSmoother increase relative to the RMS. This behavior applies reasonable smoothing, while offering significantly reduced lag for aligning with market movements.
█ USAGE
This indicator plots a fixed-period SuperSmoother (red) and the Adaptive SuperSmoother (blue) on the main chart as well as an oscillator showing the relationship between the filters in the separate pane. Ehlers recommends analyzing the difference between these two filters to derive trading signals. The preferred trading direction is long when the Adaptive SuperSmoother is above the fixed-period SuperSmoother, and short otherwise. Ehlers also suggests that peaks and valleys in the difference between the filters can help identify turning points.
This script includes three inputs for customizing the filter calculations:
Source : The source series to process. The default is "Close".
Base period : The base period of the filters. The default is 20.
RMS length : The number of bars in the RMS calculation. The default is 81.
The snapshot below shows the indicator's outputs using default settings on a 1D S&P 500 Futures chart. The Adaptive SuperSmoother responds to market movements more quickly than the fixed-period SuperSmoother, while still smoothing out high-frequency noise in the data:
Indikator

Moving Average Liquidity Sweeps - Candle Iron CoreMoving Average Liquidity Sweeps - Candle Iron Core
OVERVIEW
Moving Average Liquidity Sweeps is a rule-based indicator designed to identify wick-based sweeps around a dynamically calculated moving average.
Unlike a fixed horizontal liquidity level, a moving average continuously changes with price. This indicator uses the selected EMA or SMA as a dynamic reference and evaluates how individual candles interact with it.
A candle is not classified as a sweep simply because its wick touches or crosses the moving average.
To qualify, the interaction must satisfy independent conditions involving:
The position of the candle body relative to the moving average.
The total length of the wick.
The actual depth of penetration beyond the moving average.
The purpose is to provide a configurable and repeatable method for distinguishing qualifying wick-based interactions from ordinary touches or shallow retests of a moving average.
CORE CONCEPT
The selected moving average acts as the dynamic reference level.
Users can choose:
EMA - Exponential Moving Average
SMA - Simple Moving Average
Moving Average Length
Moving Average Source
For example, the indicator can evaluate interactions with a 21 EMA, 89 SMA, 200 EMA, or any other user-defined combination.
The moving average itself does not determine whether an interaction qualifies as a sweep.
The candle must independently satisfy the sweep conditions described below.
MOVING AVERAGE CALCULATION
When EMA is selected, the script calculates an Exponential Moving Average using the selected source and length.
When SMA is selected, the script calculates a Simple Moving Average using the selected source and length.
The resulting value becomes the Liquidity Moving Average used as the reference for each candle.
Because the moving average is recalculated over time, the reference level evaluated by the script changes from bar to bar.
TWO INDEPENDENT PERCENTAGE FILTERS
The indicator separates two measurements:
Minimum Wick Length (%)
Minimum Sweep Depth Beyond MA (%)
These measurements serve different purposes.
A candle can have a large wick while only slightly crossing the moving average.
Conversely, crossing the moving average does not necessarily mean that the wick itself is significant.
Requiring both conditions provides additional control over what the user chooses to classify as a qualifying sweep.
1. MINIMUM WICK LENGTH
This parameter evaluates the complete wick responsible for the interaction.
For a sweep below the moving average:
Lower edge of candle body → Candle Low
For a sweep above the moving average:
Upper edge of candle body → Candle High
The lower edge of the candle body is defined as the lower value between Open and Close.
The upper edge of the candle body is defined as the higher value between Open and Close.
Therefore, the calculation works consistently for both bullish and bearish candles.
The percentage calculation used by the indicator is:
Lower Wick % = (Body Low - Low) / Body Low × 100
Upper Wick % = (High - Body High) / Body High × 100
The complete wick must meet or exceed the Minimum Wick Length selected by the user.
2. MINIMUM SWEEP DEPTH BEYOND MA
Sweep Depth measures a different distance.
Instead of measuring the complete wick, it measures only how far price extends beyond the moving average.
For a sweep below:
Moving Average → Candle Low
For a sweep above:
Moving Average → Candle High
The percentage calculation is:
Sweep Depth Below % = (Moving Average - Low) / Moving Average × 100
Sweep Depth Above % = (High - Moving Average) / Moving Average × 100
This condition helps distinguish a qualifying penetration from a candle that merely touches or moves slightly beyond the moving average.
SWEEP ABOVE MOVING AVERAGE
A candle qualifies as a Sweep Above when all of the following conditions are satisfied:
The entire candle body remains at or below the moving average.
The upper wick crosses above the moving average.
The complete upper wick meets or exceeds the selected Minimum Wick Length.
The distance from the moving average to the candle High meets or exceeds the Minimum Sweep Depth Beyond MA.
The selected direction settings allow sweeps above the moving average.
When all conditions are satisfied, a downward triangle is plotted above the candle.
SWEEP BELOW MOVING AVERAGE
A candle qualifies as a Sweep Below when all of the following conditions are satisfied:
The entire candle body remains at or above the moving average.
The lower wick crosses below the moving average.
The complete lower wick meets or exceeds the selected Minimum Wick Length.
The distance from the moving average to the candle Low meets or exceeds the Minimum Sweep Depth Beyond MA.
The selected direction settings allow sweeps below the moving average.
When all conditions are satisfied, an upward triangle is plotted below the candle.
WHY BODY POSITION MATTERS
The candle body is intentionally required to remain on the original side of the moving average.
A candle whose body crosses through the moving average represents a different type of interaction from a candle that penetrates the level only with its wick.
For this reason:
Sweep Above → Body remains below the MA.
Sweep Below → Body remains above the MA.
This allows the indicator to focus specifically on wick-based interactions rather than classifying every candle that crosses a moving average as a sweep.
WHY WICK LENGTH AND SWEEP DEPTH ARE SEPARATE
Consider a candle with a large lower wick.
The candle may satisfy the Minimum Wick Length requirement while extending only slightly below the moving average.
Without an additional depth requirement, a shallow interaction could qualify solely because the candle happened to have a long wick.
The Minimum Sweep Depth Beyond MA solves this by requiring price to travel a separately defined minimum distance beyond the moving average.
Therefore:
Wick Length measures the wick itself.
Sweep Depth measures the penetration beyond the moving average.
A qualifying signal must satisfy both.
SWEEP DIRECTION
The indicator allows users to select:
Both - Detect interactions above and below the moving average.
Above MA - Detect only sweeps above the moving average.
Below MA - Detect only sweeps below the moving average.
CANDLE CLOSE CONFIRMATION
The Confirm only after candle close option determines whether the script waits for the current candle to close before confirming a signal.
When enabled, a sweep is marked only after the bar is confirmed.
This is particularly relevant because the High, Low and Close of an active candle can continue changing before the candle closes.
VISUAL SETTINGS
Users can customize:
Whether the moving average is displayed.
Moving Average color.
Moving Average width.
Sweep marker color.
The plotted moving average corresponds directly to the dynamic reference used by the sweep calculations.
HOW TO USE
A basic workflow is:
Select EMA or SMA.
Choose the Moving Average Length.
Select the Moving Average Source.
Define the Minimum Wick Length.
Define the Minimum Sweep Depth Beyond MA.
Choose whether to detect sweeps above, below, or in both directions.
Optionally require candle-close confirmation.
Evaluate qualifying interactions within the context of the user's own trading methodology.
EXAMPLE
Suppose a trader selects a 200 EMA.
A candle trades below the EMA and its upper wick extends through it.
Crossing the EMA alone does not produce a signal.
For the candle to qualify as a Sweep Above:
Its complete body must remain at or below the EMA.
Its upper wick must cross the EMA.
Its complete upper wick must satisfy the Minimum Wick Length.
The portion extending beyond the EMA must satisfy the Minimum Sweep Depth Beyond MA.
Only when all conditions are satisfied does the indicator plot the sweep marker.
ORIGINALITY AND PURPOSE
This indicator is not intended to introduce another moving-average crossover system.
The moving average serves only as a dynamically changing reference level.
The script's primary functionality is the classification of candle interactions around that reference using three independent structural conditions:
Candle-body position relative to the moving average.
Minimum total wick length.
Minimum penetration depth beyond the moving average.
Separating total wick length from actual penetration depth is particularly important because the two measurements describe different characteristics of the candle.
This combination allows users to define a consistent threshold for wick-based interactions with dynamic EMA or SMA levels rather than treating every touch, crossover, or wick penetration as equivalent.
ALERTS
Alert conditions are included for:
Liquidity Sweep Above MA
Liquidity Sweep Below MA
The alerts use the same conditions as the corresponding visual markers.
IMPORTANT NOTES AND LIMITATIONS
The term "Liquidity Sweep" in this indicator describes a candle interaction that satisfies the quantitative rules defined above.
The indicator does not observe the exchange order book and therefore does not confirm the presence of resting orders, stop-loss concentrations, institutional orders, or actual available liquidity at the moving average.
Likewise, an EMA or SMA is not inherently a liquidity level.
The moving average is used by this script as a dynamic reference selected by the user for evaluating wick behavior.
A qualifying sweep does not predict that price will reverse, continue, or produce a profitable trading opportunity.
Moving averages, volatility and candle characteristics can behave differently across assets and timeframes. Parameters should therefore be evaluated specifically for the market, timeframe and methodology in which they are intended to be used.
This indicator does not provide Buy or Sell signals and does not guarantee future market behavior. Indikator

Sattam | Trend FilterSATTAM | Trend Filter
A trend-following overlay built on a triple-pass exponential smoothing engine
with Fibonacci-adaptive volatility bands and a live command-center panel.
── HOW IT WORKS ──────────────────────────────────────────────
1) NOISE FILTER
Price is passed through three chained EMA stages. Each stage feeds the next,
which removes most of the intrabar noise that makes a single moving average
whipsaw, while keeping the turn of the trend readable.
2) TREND DETECTION
Direction is taken from the 2-bar slope of the filter line (base - base ),
not from a price/MA cross. The line turns green while the slope is positive
and red while it is negative. An orange diamond marks the exact bar where the
slope flips sign (confirmed on close only - no repainting of the signal).
3) FIBONACCI-ADAPTIVE BANDS
Band width is the smoothed high-low range, expanded by three Fibonacci
multipliers (0.236 / 0.382 / 0.618, scaled). The bands breathe with real
volatility, so the same settings work on a quiet range and on a fast trend.
Fills are gradient-colored by trend momentum, from bear color to bull color.
4) MULTI-FILTER (optional)
Adds a slower filter line. Triangles mark fast/slow crosses, and the panel
reports whether both filters agree (Aligned) or conflict (Divergent).
── COMMAND CENTER PANEL ──────────────────────────────────────
• Trend - current direction
• Strength - 0-100% of the strongest slope in the lookback window
(Strong / Moderate / Weak / Flat)
• Band Pos - where price sits inside the outer bands
(Over-Extended / Upper Band / Mid / Lower Band)
• Filters - fast vs slow agreement (multi-filter mode)
• Signal - the active flip on this bar
── HOW TO USE ────────────────────────────────────────────────
• Trade in the direction of the line color; treat flips as the alert to act.
• Prefer entries taken while Strength is Strong or Moderate; Flat readings
usually mean a range, where flips are least reliable.
• "Over-Extended" in Band Pos warns that price is stretched to the outer band
- useful for taking partials or waiting for a pullback instead of chasing.
• Turn on Multi-Filter for higher-timeframe context: take signals only when
the panel shows Aligned.
── SETTINGS ──────────────────────────────────────────────────
All inputs are labelled in English and Arabic.
• Filter Length - lower = faster and more signals, higher = smoother
(25 default; try 50-80 on lower timeframes, 10-20 for scalping)
• Slow Filter Length - the confirmation filter (80 default)
• Colors, fill transparency, bar coloring
• Panel position, size, and language (EN / AR)
── ALERTS ────────────────────────────────────────────────────
• Trend Bullish / Trend Bearish (slope flip)
• Fast Cross Up / Fast Cross Down (multi-filter cross)
All alerts fire once per bar close and include ticker, timeframe and price.
Panel language (EN / AR) also controls the alert message language.
Works on any symbol and any timeframe.
Disclaimer: for education and analysis only. This is not financial advice.
No indicator predicts the future - always use your own risk management.
SATTAM | Trend Filter — فلتر الاتجاه
مؤشر اتجاه يُرسم فوق الشارت، مبني على محرّك تنعيم أُسّي ثلاثي المراحل،
مع نطاقات فيبوناتشي متكيّفة مع التذبذب، ولوحة تحكّم مباشرة.
── كيف يعمل ─────────────────────────────────────────────────
١) فلتر الضجيج
يمرّ السعر عبر ثلاث مراحل EMA متسلسلة، كل مرحلة تُغذّي التي بعدها.
هذا يزيل معظم الضجيج الذي يجعل المتوسط المتحرك العادي يتذبذب،
مع بقاء لحظة انعكاس الاتجاه واضحة وقابلة للقراءة.
٢) تحديد الاتجاه
الاتجاه يُؤخذ من ميل الخط عبر شمعتين (base - base )، وليس من تقاطع
السعر مع متوسط. الخط أخضر عندما يكون الميل موجباً، وأحمر عندما يكون سالباً.
الماسة البرتقالية تحدّد الشمعة التي انقلب فيها الميل — وتُؤكَّد عند إغلاق
الشمعة فقط، بلا إعادة رسم للإشارة.
٣) نطاقات فيبوناتشي المتكيّفة
عرض النطاق = مدى (أعلى − أدنى) بعد تنعيمه، مضروباً في ثلاثة معاملات
فيبوناتشي (٠.٢٣٦ / ٠.٣٨٢ / ٠.٦١٨ بعد التحجيم). النطاقات تتّسع وتضيق مع
التذبذب الحقيقي، فتعمل نفس الإعدادات في السوق الهادئ وفي الترند السريع.
تعبئة النطاقات ملوّنة بتدرّج حسب زخم الاتجاه، من لون الهبوط إلى لون الصعود.
٤) الفلتر المزدوج (اختياري)
يضيف خط فلتر أبطأ. المثلثات تحدّد تقاطع السريع مع البطيء، واللوحة تُظهر
هل الفلتران متوافقان (متوافق) أم متعارضان (متعارض).
── لوحة التحكّم ─────────────────────────────────────────────
• الاتجاه — الاتجاه الحالي (صاعد / هابط)
• القوة — من ٠ إلى ١٠٠٪ مقارنةً بأقوى ميل في فترة القياس
(قوي / متوسط / ضعيف / محايد)
• موضع النطاق — أين يقع السعر داخل النطاقات الخارجية
(تشبّع / النطاق العلوي / الوسط / النطاق السفلي)
• الفلاتر — توافق السريع مع البطيء (في وضع الفلتر المزدوج)
• الإشارة — الانعكاس النشط على الشمعة الحالية
── طريقة الاستخدام ──────────────────────────────────────────
• تداول مع لون الخط، واعتبر لحظة الانعكاس هي إشارة التحرّك.
• فضّل الدخول عندما تكون القوة «قوي» أو «متوسط»؛ قراءة «محايد» غالباً تعني
سوقاً عرضياً تكون فيه الانعكاسات أقل موثوقية.
• ظهور «تشبّع» في موضع النطاق يعني أن السعر امتدّ إلى النطاق الخارجي —
مفيد لجني جزء من الأرباح أو انتظار الارتداد بدل المطاردة.
• فعّل الفلتر المزدوج للحصول على سياق الفريم الأكبر، وخذ الإشارات فقط
عندما تُظهر اللوحة «متوافق».
── الإعدادات ────────────────────────────────────────────────
جميع الإعدادات مكتوبة بالإنجليزية والعربية معاً.
• طول الفلتر — الأقل = أسرع وإشارات أكثر، والأعلى = أنعم
(الافتراضي ٢٥؛ جرّب ٥٠–٨٠ على الفريمات الصغيرة، و١٠–٢٠ للمضاربة السريعة)
• طول الفلتر البطيء — فلتر التأكيد (الافتراضي ٨٠)
• الألوان، وشفافية التعبئة، وتلوين الشموع
• موضع اللوحة وحجمها ولغتها (EN / AR)
── التنبيهات ────────────────────────────────────────────────
• اتجاه صاعد / اتجاه هابط (انعكاس الميل)
• تقاطع صاعد / تقاطع هابط للفلتر السريع (في الفلتر المزدوج)
كل التنبيهات تُطلق مرة واحدة عند إغلاق الشمعة، وتتضمّن الرمز والفريم والسعر.
لغة اللوحة (EN / AR) تتحكّم أيضاً في لغة نص التنبيه.
يعمل على جميع الرموز وجميع الفريمات الزمنية.
إخلاء مسؤولية: هذا المؤشر لأغراض تعليمية وتحليلية فقط، وليس نصيحة مالية.
لا يوجد مؤشر يتنبأ بالمستقبل — التزم دائماً بإدارة رأس المال الخاصة بك. Indikator

TrendFusion Pro | Multi-MA + ADX + KAMA + VWAP Hariss 369A flexible multi-timeframe trend-following indicator designed to identify bullish and bearish market conditions using configurable Moving Average alignment.
The system allows traders to combine up to three Moving Averages, with independent settings for MA type, length and timeframe. Supported MA types include EMA, SMA, WMA, VWMA, RMA and HMA.
Core Features
• Three independently configurable Moving Averages
• EMA, SMA, WMA, VWMA, RMA and HMA support
• Individual timeframe selection for each MA
• Flexible MA alignment logic for BUY and SELL conditions
• Optional DMI/ADX trend-strength filter
• Optional Higher-Timeframe KAMA trend filter
• Optional Higher-Timeframe VWAP filter
• ATR-based dynamic trailing stop
• Separate long and short ATR trailing stops
• BUY and SELL signals with configurable colours
• Alert conditions for BUY and SELL signals
• Clean chart-based trend visualization
How the Trend Logic Works
When multiple MAs are enabled, the indicator looks for price and MA alignment.
For bullish conditions, price must be above the selected MAs and the enabled MAs must be properly aligned from faster to slower.
For bearish conditions, price must be below the selected MAs and the enabled MAs must be aligned in the opposite direction.
The indicator can also require confirmation from:
• DMI/ADX
• Higher-Timeframe KAMA
• Higher-Timeframe VWAP
These filters are optional and can be enabled or disabled according to the trader's methodology.
ATR Trailing Stop
The indicator calculates a dynamic ATR-based trailing stop.
For long conditions, the stop can only move upward as the trend progresses.
For short conditions, the stop can only move downward.
This provides a dynamic way to manage trend-following trades while allowing the trader to adjust ATR length and multiplier according to the market and timeframe.
Suggested Use
The indicator can be used for:
• Trend identification
• Trend-following entries
• Pullback confirmation
• Multi-timeframe market analysis
• Dynamic trailing-stop management
• Alert-based trading workflows
The default configuration uses 20 EMA, 50 EMA and 200 EMA, but these settings are fully customizable.
Different combinations can be tested depending on the instrument, timeframe and trading style.
Important
This indicator is designed as a technical-analysis and decision-support tool. It does not guarantee profitable trades and should not be treated as a standalone trading system.
Always test settings on historical data and in real-time market conditions before using them with real capital. Indikator

CPI Gate Regime v3.1 (SMA)CPI Gate Regime v3.1 (SMA)
A daily trend + macro-regime dashboard built for trading TQQQ, using QQQ as the regime instrument. The trend signal runs on the TQQQ chart you apply it to; the bear-market classifier deliberately measures the underlying index (QQQ), because the index defines the market regime while the leveraged ETF is only the vehicle.
What chart to use it on
Apply it to the TQQQ daily chart (or another QQQ-tracking vehicle you trade). The moving-average signal computes on the chart symbol — on TQQQ, the lines are TQQQ's own 200-day and 20-day SMAs. The bear latch, however, always reads QQQ's drawdown, regardless of chart symbol. This is intentional: a −15% drawdown in QQQ corresponds to roughly a −40% move in TQQQ, and measuring the regime on the noisier 3x series would latch it on ordinary corrections. Index for the regime, leveraged ETF for the trade.
The idea
Not all bear markets are the same shape. Fast crashes in low-inflation environments (2018, 2020) tend to V-bottom, and a fast re-entry catches the recovery early. Grinding bears in high-inflation environments (2000–02, 2022) chop down for months, and the same fast re-entry buys every failed rally. The differentiator used here: when CPI is above ~3%, the central bank is constrained (cutting into hot inflation is hard), so declines are more likely to grind. When CPI is below 3%, policy support is available and declines are more likely to snap back.
Trend signal (two-speed, on the chart symbol — TQQQ)
200-day and 20-day simple moving averages of the daily close, computed on daily bars regardless of chart timeframe. Lines plot green when the close is above them, red when below.
The rule: LONG when the close is above the 200-day SMA, or (below it) above the 20-day SMA; FLAT only below both. Above the 200-day the position is locked long and the 20-day is ignored — the fast line only becomes active below the 200, where it serves as the early re-entry during a recovery.
In a latched GRIND bear (see below), the 20-day re-entry is disabled entirely — only a full 200-day reclaim signals a buy.
Signals on the chart
Exactly two marker types, printed only when the complete system flips: a green BUY label below the bar, a red SELL label above it. No markers on ordinary 20-day crosses (they don't change the position above the 200-day), and no markers on 20-day re-entries during a grind bear (the system refuses those trades). What you see marked is what the rule set actually does. Signals form on the daily close; execution is assumed at the next open.
The latched bear regime (the "CPI gate", on QQQ)
A bear LATCHES when QQQ closes 15% or more below its trailing 2-year high.
At that moment — once — the classifier checks CPI YoY: above the gate (default 3%) = GRIND, below = SNAP.
Latched means latched: the mode does not flip-flop with daily data. One-way upgrade only: SNAP can become GRIND if CPI heats up mid-bear, never the reverse.
The latch releases when QQQ recovers to within 5% of its 2-year high.
Effect on signals: GRIND kills the fast re-entry (200-day reclaim only); SNAP keeps the normal two-speed.
Dashboard (early warnings, top right)
CPI YoY vs the gate (ECONOMICS:USIRYY)
FINRA margin debt YoY — manual input; elevated / blow-off thresholds
High-yield credit spread (FRED:BAMLH0A0HYM2) — waking / stress thresholds
QQQ drawdown from its 2-year peak — heads-up at −10%, trigger at −15%
Regime label escalates: CALM → FRAGILITY BUILDING (hot CPI + elevated margin) → STRESS IGNITING (credit spreads waking) → BEAR: SNAP or GRIND (latched)
Only the −15% / CPI latch changes the signals; the other rows are context so a latch never arrives as a surprise.
Inputs
All thresholds are configurable: SMA lengths, CPI gate %, margin elevated/blow-off %, HY spread waking/stress (bps), drawdown heads-up/trigger %, and the CPI / HY spread symbols. Margin debt YoY is entered manually (FINRA publishes monthly).
Notes
Designed on daily bars; on intraday charts the signal stays locked to daily data. The bear-latch state on historical bars is computed from the chart's loaded history, so labels at the far left edge of a short history may differ from a fully loaded chart; current-bar state is unaffected. For educational purposes — this is a regime framework, not financial advice. Test any rule set yourself before trading it.
v3.1 — markers now show only full-system BUY/SELL signals (including the grind-bear gate); removed the 20-day cross dots and 200-day flip triangles. Indikator

Slope & MA Cross + Acc + Range FilterSlope & MA Cross + Acceleration + Angle Filter Strategy
This strategy combines Moving Average Velocity (Slope), Momentum Acceleration, Trigonometric Angle Filtering, and Dynamic Risk Management (Shrinking SL) into a unified quantitative trading framework. It is designed to capture early trend reversals while aggressively filtering out sideways/ranging market noise, especially on lower timeframes (e.g., 3-minute or 5-minute charts).
---
### 🚀 Key Features
#### 1. Momentum Acceleration (Early Signal Logic)
Instead of waiting for price crossovers or MA slope direction changes—which can introduce lag—the strategy measures the 2nd derivative of the Moving Average (Acceleration):
Acceleration = Current Slope - Previous Slope
This allows the algorithm to detect early deceleration at market bottoms/tops before the Moving Average officially changes direction.
#### 2. Scaled Trigonometric Angle Filter
Ranging markets often trigger costly false signals (whipsaws). The strategy calculates the slope angle using the arctangent function:
Angle = degrees(arctan(Price Change % * Multiplier))
Using an Angle Sensitivity Multiplier, micro percentage changes on short timeframes (e.g., 3m) are scaled across a wider degree spectrum, allowing precise filter fine-tuning to ignore sideways consolidation.
#### 3. Dynamic Shrinking Stop Loss
To protect profits during exhausting trends, the strategy features a Shrinking Stop Loss. When a trade reaches a specific profit threshold and momentum starts fading, the stop-loss level dynamically tightens toward the current price structure.
#### 4. Real-Time Dashboard
The built-in table displays live information including:
- Current Position Status & Market Regime (Trending vs. Ranging)
- MA Slope, Acceleration, and Scaled Angle Values
- Real-Time Open PnL (%) and Total Net Profit ($ / %)
---
### ⚙️ How to Use
1. Apply to Chart: Best suited for fast-moving assets on low timeframes (3m / 5m / 15m) using responsive MAs like Hull MA or ALMA.
2. Tune Angle Filter: Adjust Angle Sensitivity Multiplier and Minimum Trend Angle to filter out local consolidation areas.
3. Execution: All trades are executed upon bar confirmation (barstate.isconfirmed) to prevent repainting. Strategi