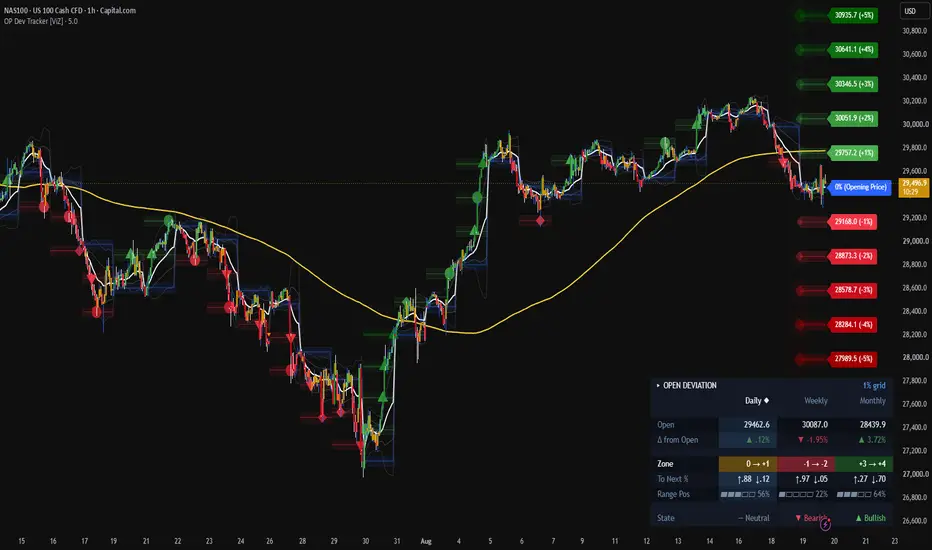
Opening Price Deviation Tracker v2 - Buffer Zones - VWAP [ViZ]OPENING PRICE DEVIATION TRACKER v2 — BUFFER ZONES — VWAP
WHAT IT DOES
Measures how far price has travelled from the opening price of a chosen anchor
period, and maps that distance onto a fixed percentage grid on the chart.
The reasoning is that the open of the current period is a reference every
participant on the instrument shares, and that distance from it expressed in
percent is comparable across instruments and across time in a way raw price
distance is not. A 1% move from the weekly open means the same thing on a
30,000-point index as on a 40-dollar stock.
Around that single idea the script adds a tolerance band on each level, a
permanent record of which levels each period actually reached, a three-timeframe
summary panel, optional trend and volume references, and three alert channels
that differ in what they detect rather than only in speed.
Every component keys back to the same anchor open. This is not a set of unrelated
tools sharing a pane.
1. THE ANCHOR OPEN, AND WHY IT IS LATCHED
The Timeframe input sets the anchor period — weekly by default, but any timeframe
longer than the chart's.
The script obtains that period's opening price by latching it: on the first chart
bar of a new anchor period, that bar's own open IS the period's open, so the value
is stored and held until the next rollover.
There is no request.security() call anywhere in the script. Not for the anchor
open, not for the three table columns, not for VWAP.
That matters for a specific reason worth stating plainly. The obvious way to build
this is request.security with lookahead enabled, and for an OPEN that is actually
defensible — an open is fixed by the first tick of its period, so requesting it
with lookahead never returns a number that was unknowable at the time. Without the
flag the same call returns the PREVIOUS period's open until the current one closes,
which puts the whole grid one full anchor period behind itself, so simply turning
the flag off is not an option. Latching sidesteps the argument entirely: the value
is a chart bar's own open, so it provably cannot look ahead, there is no
higher-timeframe request to disclose, and there is no real-time-to-historical
transition to reason about. Levels drawn on historical bars are the levels that
genuinely existed at the time, and they do not change on reload.
The period high and low used by the panel are accumulated from chart bars for a
different and stronger reason: a period's extremes are only settled when the period
ENDS, so requesting those with lookahead genuinely would leak future data onto
historical bars. Open safe, extremes not — that distinction is the whole substance
of the question.
Latching does cost something, in the form of four documented behaviours. They are
in the LIMITATIONS section, and reading it will explain most of what could
otherwise look like a bug.
2. THE DEVIATION GRID
From the latched open the script builds five levels above and five below, spaced by
a fixed percentage step, with the 0% line marking the open itself. Line width
increases with distance, so ±1 is a hairline and ±5 is the heaviest — depth is
readable without checking the labels. Each level carries a right-edge label showing
both its price and its percentage offset. Colours darken progressively outward from
the two base colours you set.
The step comes from a preset list, each labelled with its own value:
0.25% — scalping / very low volatility
0.3875% — reactive / lower timeframes
0.50% — intraday
1.00% — balanced (default)
2.00% — swing / higher timeframes
3.00% — high volatility / highest timeframes
Custom — any value from 0.1 upward
Because the grid always runs to five levels, the step also fixes its total span: 1%
covers ±5%, 2% covers ±10%, 0.25% covers ±1.25%. Pick the step whose span roughly
brackets what your anchor period typically moves. Too small and price sits
permanently off the top or bottom of the grid; too large and it never leaves the
first band, and nothing the script draws will tell you anything.
As orientation rather than instruction: the lower steps suit major FX pairs and
large-cap equities on intraday anchors, the middle of the range suits indices and
most equities on daily and weekly anchors, and the upper steps suit small caps,
commodities and crypto, or any weekly-and-above anchor. Volatility varies more
inside an asset class than between them, so verify against the instrument in front
of you and switch to Custom once you know what you want.
The step also drives the panel's Zone and To Next rows, the buffer positions, touch
detection and the markers — one number, one grid, everywhere.
3. LINE DISPLAY
Three modes:
Off — no grid lines; panel, markers and alerts still work
Show All — full grid across history and the live period
Touched Only (Historical) — live period shows the full grid; completed periods
keep only the levels price actually reached
The third is the default and is the one worth understanding. On a chart with months
of history, showing all eleven lines per period is unreadable. Retaining only the
levels each period actually reached leaves a permanent record of how far each period
extended — which is usually the only thing you wanted from the older periods.
Those historical segments are stored as drawn objects and accumulate without an
explicit cap, bounded only by TradingView's 500-line budget. When the ceiling is
reached the platform deletes the oldest, so the recent history you actually look at
is never what disappears. The 0% opening line is exempt from filtering and always
renders in full.
4. BUFFER ZONES
Each deviation level, and the open itself, can carry a translucent band drawn a set
percentage of price above and below it — eleven bands in total.
Two reasons for them. Price rarely reacts at an exact tick; it reacts in a region
around a reference, so a band represents the level more honestly than a line. And
the band gives an anticipatory alert trigger: entry into the band fires before the
level is reached.
The live period's bands are drawn spanning the current period. Bands from previous
periods are also retained, but only for levels that were actually touched, so past
structure appears where something happened rather than as uniform wallpaper.
Historical retention is capped at 44 periods, which is the limit of the platform's
500-drawing budget once the live period's own eleven boxes are accounted for; lower
it freely for a cleaner chart, nothing else depends on it.
One interaction to be aware of: buffer size is a percentage of price and does not
scale with the grid step. Lead time depends on the RATIO of the two, not the
absolute size. At roughly a quarter of the deviation step the warning is genuinely
early; at half or more the warning and the touch collapse into the same bar. The
default 0.15 against a 1% grid is 15%. Against the 0.3875% preset the same value is
39%, which effectively eliminates the early warning; against the 3% preset it is 5%,
which may be too tight to see. If you change the step, check the buffer against it.
5. TOUCH MARKERS
Optional, and off by default. A small marker is placed on the first bar of each
period that reaches each level — one marker per level per period, re-armed at every
rollover.
Marker shapes:
● circle — touch: the bar's range reached the level.
▲ ▼ triangle — acceptance: the bar CLOSED beyond the level. Points up above the
open, down below it.
◆ diamond — rejection: the bar tagged the level and closed back, with a retreat wick
larger than the threshold you set.
✕ cross — gap through: the bar reached the level without trading into it.
Three detail modes let you take just the touches, touches plus acceptance, or the
full touch / rejection / acceptance set. Rejection sensitivity is adjustable as a
fraction of the bar's range, 0.5 by default; raise it toward 0.65 for a stricter
read. Marker range is adjustable up to ±5 levels, ±4 by default. The 0% line can be
marked too, optionally. Colours inherit from the grid by default, so a +3 marker
matches the +3 line; the 0% marker is always blue to match the opening-price line.
Each marker's tooltip states the level and the classification.
Markers use the same reach test as the historical line segments — directional above
and below the open, straddle at 0% — so a marker and a retained line segment can
never disagree about whether a level was touched. Markers appear at bar close by
default; an option tags them on the live bar instead, in which case the shape may
still change before the bar closes, because acceptance and rejection both depend on
where the bar ends up. That option is visual only and affects no alert.
6. BAR COLOURING
Optional, with two selectable sources.
Deviation Levels colours each bar by which of the eleven grid zones it closed in,
using the same progressively darkening shades as the lines, with the "between
levels" colour for bars inside the first band. The candles then carry the deviation
reading themselves, which means you can switch the grid off entirely and still see
depth — a genuinely clean chart that still reports.
VWAP / Bands colours by position relative to the anchored VWAP and its bands
instead: five zones, beyond the outer band, beyond the inner band, and between, on
each side. It falls back to plain above/below VWAP when bands are off. Useful when
you want the grid for structure but volume-weighted price for bias. This mode needs
only volume and a valid anchor, so it works with the VWAP line itself hidden.
Bars before the first anchor rollover are deliberately left uncoloured rather than
being painted a default shade, since no zone reading exists for them yet.
7. MOVING AVERAGE
Optional SMA or EMA, adjustable period, 200 by default. Context rather than signal:
it exists so you can see whether a level is being approached with or against the
prevailing trend, which usually matters more than the touch itself.
8. VWAP
Optional anchored VWAP with its own reset selection, independent of the deviation
anchor: daily session, weekly, monthly, quarterly, semi-annual, annual, Match
Deviation Anchor, or a custom timeframe. Daily session matches the standard
TradingView VWAP. The multi-month options are derived from the monthly rollover and
then gated by calendar month, so they land on real calendar boundaries — January /
April / July / October, January / July, and January — rather than drifting from an
arbitrary reference point.
Match Deviation Anchor is the setting for a single consistent frame of reference:
grid and VWAP then reset on the same bar and describe the same period. The
independent options cover the common case of a session VWAP underneath a weekly or
monthly grid.
Two optional band pairs, in either standard-deviation or percentage units, are
independent of the deviation grid preset. The outer pair is rendered a step more
transparent than the inner, so depth reads without a second colour input, and a very
light fill between the inner pair is available but off by default so it does not
compete with the buffer zones. Note that in sigma mode the bands pinch shut at each
anchor reset and flare open over following bars — that is inherent to anchored
standard deviation, not a fault; percentage mode does not do it.
The line and bands are blanked on the anchor bar itself, so the plot BREAKS at each
reset instead of drawing a diagonal from the old period's last value to the new
one's first.
VWAP needs volume, and needs an anchor longer than the chart timeframe. If either
is missing, an on-chart label states which — including when VWAP is hidden but the
VWAP bar-colouring mode is active and starved.
9. THE DATA PANEL
Projects the same deviation grid onto three user-selectable timeframes, each
measured from that timeframe's own latched opening price. Defaults are daily,
weekly and monthly, and the column matching the indicator's own anchor is marked
with a diamond. The title bar shows the active step, for example "1% grid".
Rows, in Full detail:
Open — that period's opening price, at the symbol's own precision.
Δ from Open — percentage move from that open, with a direction arrow. Colour
intensity scales with magnitude, and the saturation ceiling scales as the square
root of the column's length, so at the 1% preset the daily column saturates around
2%, the weekly around 4.5% and the monthly around 9.2%. Each column is therefore
meaningful on its own scale, rather than one fixed ceiling that the longest column
always maxes out.
Zone — which band price currently occupies, shown as "+1 → +2", "0 → -1" and so on,
filled with the SAME colour as the corresponding chart grid line. Beyond the grid it
reads "> +5" or "< -5" rather than silently clamping.
To Next % — distance to the level above and the level below. This is the practical
number for judging whether a target is in reach.
Range Pos — where price sits inside that period's realised high-low range so far, as
a percentage with a small meter. 90% means price is near the top of everything the
period has covered.
State — bullish, bearish or neutral, combining direction from Δ with conviction from
Range Pos, so it is not merely a restatement of the sign of Δ. When the range is
unknown it degrades to direction only.
Compact detail drops To Next and Range Pos and closes the gap rather than leaving
empty rows. The panel's whole surface palette — header band, row banding,
separators, anchor-column wash — is derived from one background colour input, and
text automatically switches to a dark set on light backgrounds. Colour is carried by
text tint throughout, with the Zone row as the single filled block and the panel's
focal point.
Three column states exist. A column SHORTER than the chart timeframe reads "below
chart TF", because a shorter-timeframe open cannot be resolved honestly from a
longer chart bar. A column whose boundary has not appeared inside the loaded chart
history reads "no boundary yet" — see LIMITATIONS. Otherwise it reports normally.
The point of three columns at once is alignment. Bullish daily, bearish weekly,
bullish monthly is a different situation from all three agreeing, and the panel makes
that visible without changing timeframe.
10. ALERTS — THREE CHANNELS
The three channels differ in WHAT THEY DETECT, not only in how fast they report.
Each has its own toggle.
BUFFER (early warning) — fires when price first enters the band around a level.
Dispatches intrabar, the moment the band is entered; delivered at the bar close it
would already have been overtaken by events. On by default.
AT LEVEL — fires on any bar whose range CONTAINS a level, and keeps repeating for
as long as price stays there. Dispatches intrabar, on the first qualifying tick.
This is safe intrabar because the test reads only high and low: inside a live bar
the range only ever widens, so once it engulfs a level no later tick can un-happen
it. The cost is partial reporting — a candle running through +1, +2 and +3 names +1,
because that is what was true at the tick it fired. On by default.
FIRST TOUCH — fires the first time each level is reached in the anchor period, then
stays silent about that level until the next period. Dispatches at bar close,
because its wording carries a classification — touch, closed beyond, rejected — and
all of those read where the bar closed, which on a live bar is only the current
price and could flip tick to tick. Evaluated once on a finished bar, it loops every
level and reports all of them. Off by default. Works with the markers hidden.
The two level channels also DETECT differently, which is why both exist. At Level
requires the bar to straddle the level. First Touch tests directionally, so a bar
that jumps clean over a level without trading back into it is reported by First
Touch and is structurally invisible to At Level. That is the gap-through case, and
it is exactly what a news candle does.
So: buffer and at-level answer "tell me now". First touch answers "tell me
everything, a moment later".
All three messages render as ": | Price: ", with the
buffer channel adding " | Level: ", so anything parsing them downstream sees
one consistent shape. No timestamps are embedded, because every delivery method
TradingView offers already stamps the notification.
TO SET UP: create ONE alert on the indicator with the condition set to "Any alert()
function call". The three toggles decide what it reports. The long string
TradingView pre-fills is the alert's NAME, auto-built from every input — rename it
in the dialog; it is not the message.
If you want a different sound or webhook per channel, add the indicator to the chart
more than once, enable exactly one channel per instance, strip the extra instances
of all drawing, and name each chart alert after its channel. Keep the anchor and
preset identical across instances or the channels start describing different grids.
One known behaviour: if a single bar enters more than one buffer band, the buffer
message names the last one evaluated rather than listing all of them. The alert
still fires; the label is simply not exhaustive. Most visible on fast bars, or when
buffer size approaches half the deviation step and bands begin to overlap.
11. CHOOSING A CHART TIMEFRAME AND ANCHOR
The useful rule of thumb is that the anchor period should span roughly 20 to 100
bars of the chart timeframe. Fewer and the grid has no room to develop; many more
and the levels are too distant to be actionable within a session.
In practice: 1m to 15m charts pair with daily and weekly anchors, hourly and 4-hour
with weekly and monthly, daily and above with monthly, quarterly and annual. For
the panel, suggested column sets are 4H/D/W under a weekly anchor, D/W/M under a
weekly or monthly anchor, and M/3M/12M under a quarterly anchor.
Some ways it gets used:
Mean-reversion context — a level reached early in a period, price stalling inside
the band, moving average leaning the other way, is a different proposition from the
same level reached mid-expansion. The rejection marker is what separates the two
after the fact.
Continuation context — sequential first-touches inside one period, left on the
chart by the touched-only display, show whether a period is expanding steadily or
stalling at the same band repeatedly. Acceptance triangles at successive levels read
differently from a diamond at the same level three times.
Risk framing — because levels are percentage distances, To Next % converts directly
into stop and target distances in the same units you size positions in.
Period bias — the panel alone, grid switched off, works as a compact
three-timeframe bias readout.
Monitoring — the first-touch channel lets you watch a list of instruments for
meaningful extension from their period open without staring at charts, and the
buffer channel gives the heads-up before it happens.
None of the above is prescriptive. The defaults are a reasonable place to start
rather than a recommendation, and the script is deliberately built so that almost
every part of it can be moved without breaking anything else — so move things.
Put the same anchor on three different chart timeframes and watch how the grid
changes character. Run the panel's three columns as 4H/D/W for a session, then as
D/W/M, and see which alignment you actually read. Switch the VWAP anchor from
session to weekly, or match it to the deviation anchor, and notice how differently
the two reference points behave when they reset together versus separately. Try
the bar colouring on one source, then the other, with the grid lines switched off
entirely. Step the deviation preset up and down on an instrument you know well
until the spacing stops feeling arbitrary — that is usually the moment the tool
starts being useful, and it is different for every instrument and every holding
period. Custom exists for when you get there.
Nothing you change is destructive and nothing is hidden behind a setup process:
every input has a tooltip explaining what it does and, where it matters, what it
interacts with. The fastest way to understand any of this is an afternoon of
switching things on and off on a chart you already have an opinion about.
12. LIMITATIONS AND KNOWN BEHAVIOURS
These are consequences of the design choice in section 1, and are stated rather
than hidden.
Leading partial period is blank. Nothing is latched until the first rollover INSIDE
loaded history, so the leftmost partial anchor period has no open and therefore no
grid, no buffers, no labels and no bar colour. It scales inversely with chart
resolution — trivial on a 15-minute chart holding thirty weeks, pronounced on a
1-minute chart holding two. Scroll hard left to see it. It is not a fault, and it is
the exact price of using no lookahead.
Columns longer than loaded history report nothing. No boundary in history means no
open, which cascades through every row, so the Δ cell says "no boundary yet" to make
the cause legible instead of leaving the column looking broken. This is a bar-density
effect: roughly 20,000 loaded one-minute bars is about 2.5 months of a 6.5-hour
equity session but under three weeks of a 24-hour instrument, so a monthly column
resolves on the former and not the latter. It also moves with the viewer's data
plan, so two users on the same chart can see different columns populated. The remedy
in every case is to view the same period on a higher chart timeframe — and in
practice column choice tracks chart timeframe anyway.
The open is session-dependent. It is the first chart bar's open under your CURRENT
session settings, which on an extended-hours symbol need not equal the feed's
official daily open. Verified to line up with session boundaries across equities,
indices and FX; it is simply the property to know about when comparing against a
platform VWAP or a broker's stated open.
The first snapshot is skipped. On the very first rollover in loaded history there is
no preceding period to snapshot, so that one period's historical segments and buffer
boxes are absent. It degrades quietly.
Buffer does not scale with the grid, as described in section 4.
The grid is not volatility-adaptive. Levels are fixed arithmetic percentages of the
open. The script does not measure realised volatility and will not widen the grid in
a volatile regime — step selection is yours to make and to revisit.
References need data. The moving average needs its full lookback before plotting;
VWAP needs volume and an anchor longer than the chart timeframe.
Drawing budgets. Retained line segments and markers share TradingView's per-script
object limits. When a ceiling is reached the oldest objects are dropped, so recent
history is never what goes missing. Reducing the marker range or the historical
buffer lookback extends how far back the rest survives.
Chart type. Use standard candles or bars. Heikin Ashi, Renko, Kagi and range bars
synthesise their own prices, which distorts every level, every touch and every alert
this script produces.
Finally, this is a measurement and context tool. It reports where price is relative
to a period open and tells you when that changes. It does not forecast direction,
and nothing in it should be read as a prediction or as a standalone entry system.
13. NOTES
Open source under the Mozilla Public License 2.0, and the source is heavily
commented — every design decision above, including the ones I chose not to make and
why, is documented in the code itself alongside the reversion instructions.
All logic is self-contained. No external libraries, no imported code from other
authors, no request.security() of any kind.
Defaults ship usable rather than optimal for any one instrument: weekly anchor, 1%
grid, touched-only historical lines, 0.15% buffer with 44 periods of history,
200-period SMA, session VWAP with bands off, deviation bar colouring, markers off,
and the buffer and at-level alert channels enabled.
This is a separate publication from my earlier opening-deviation script rather than
an update to it, because the feature set and default behaviour differ enough that
replacing the original in place would change existing users' charts without warning.
The earlier version remains available and unchanged.
Indikator

Sattam | Trend FilterSATTAM | Trend Filter
A trend-following overlay built on a triple-pass exponential smoothing engine
with Fibonacci-adaptive volatility bands and a live command-center panel.
── HOW IT WORKS ──────────────────────────────────────────────
1) NOISE FILTER
Price is passed through three chained EMA stages. Each stage feeds the next,
which removes most of the intrabar noise that makes a single moving average
whipsaw, while keeping the turn of the trend readable.
2) TREND DETECTION
Direction is taken from the 2-bar slope of the filter line (base - base ),
not from a price/MA cross. The line turns green while the slope is positive
and red while it is negative. An orange diamond marks the exact bar where the
slope flips sign (confirmed on close only - no repainting of the signal).
3) FIBONACCI-ADAPTIVE BANDS
Band width is the smoothed high-low range, expanded by three Fibonacci
multipliers (0.236 / 0.382 / 0.618, scaled). The bands breathe with real
volatility, so the same settings work on a quiet range and on a fast trend.
Fills are gradient-colored by trend momentum, from bear color to bull color.
4) MULTI-FILTER (optional)
Adds a slower filter line. Triangles mark fast/slow crosses, and the panel
reports whether both filters agree (Aligned) or conflict (Divergent).
── COMMAND CENTER PANEL ──────────────────────────────────────
• Trend - current direction
• Strength - 0-100% of the strongest slope in the lookback window
(Strong / Moderate / Weak / Flat)
• Band Pos - where price sits inside the outer bands
(Over-Extended / Upper Band / Mid / Lower Band)
• Filters - fast vs slow agreement (multi-filter mode)
• Signal - the active flip on this bar
── HOW TO USE ────────────────────────────────────────────────
• Trade in the direction of the line color; treat flips as the alert to act.
• Prefer entries taken while Strength is Strong or Moderate; Flat readings
usually mean a range, where flips are least reliable.
• "Over-Extended" in Band Pos warns that price is stretched to the outer band
- useful for taking partials or waiting for a pullback instead of chasing.
• Turn on Multi-Filter for higher-timeframe context: take signals only when
the panel shows Aligned.
── SETTINGS ──────────────────────────────────────────────────
All inputs are labelled in English and Arabic.
• Filter Length - lower = faster and more signals, higher = smoother
(25 default; try 50-80 on lower timeframes, 10-20 for scalping)
• Slow Filter Length - the confirmation filter (80 default)
• Colors, fill transparency, bar coloring
• Panel position, size, and language (EN / AR)
── ALERTS ────────────────────────────────────────────────────
• Trend Bullish / Trend Bearish (slope flip)
• Fast Cross Up / Fast Cross Down (multi-filter cross)
All alerts fire once per bar close and include ticker, timeframe and price.
Panel language (EN / AR) also controls the alert message language.
Works on any symbol and any timeframe.
Disclaimer: for education and analysis only. This is not financial advice.
No indicator predicts the future - always use your own risk management.
SATTAM | Trend Filter — فلتر الاتجاه
مؤشر اتجاه يُرسم فوق الشارت، مبني على محرّك تنعيم أُسّي ثلاثي المراحل،
مع نطاقات فيبوناتشي متكيّفة مع التذبذب، ولوحة تحكّم مباشرة.
── كيف يعمل ─────────────────────────────────────────────────
١) فلتر الضجيج
يمرّ السعر عبر ثلاث مراحل EMA متسلسلة، كل مرحلة تُغذّي التي بعدها.
هذا يزيل معظم الضجيج الذي يجعل المتوسط المتحرك العادي يتذبذب،
مع بقاء لحظة انعكاس الاتجاه واضحة وقابلة للقراءة.
٢) تحديد الاتجاه
الاتجاه يُؤخذ من ميل الخط عبر شمعتين (base - base )، وليس من تقاطع
السعر مع متوسط. الخط أخضر عندما يكون الميل موجباً، وأحمر عندما يكون سالباً.
الماسة البرتقالية تحدّد الشمعة التي انقلب فيها الميل — وتُؤكَّد عند إغلاق
الشمعة فقط، بلا إعادة رسم للإشارة.
٣) نطاقات فيبوناتشي المتكيّفة
عرض النطاق = مدى (أعلى − أدنى) بعد تنعيمه، مضروباً في ثلاثة معاملات
فيبوناتشي (٠.٢٣٦ / ٠.٣٨٢ / ٠.٦١٨ بعد التحجيم). النطاقات تتّسع وتضيق مع
التذبذب الحقيقي، فتعمل نفس الإعدادات في السوق الهادئ وفي الترند السريع.
تعبئة النطاقات ملوّنة بتدرّج حسب زخم الاتجاه، من لون الهبوط إلى لون الصعود.
٤) الفلتر المزدوج (اختياري)
يضيف خط فلتر أبطأ. المثلثات تحدّد تقاطع السريع مع البطيء، واللوحة تُظهر
هل الفلتران متوافقان (متوافق) أم متعارضان (متعارض).
── لوحة التحكّم ─────────────────────────────────────────────
• الاتجاه — الاتجاه الحالي (صاعد / هابط)
• القوة — من ٠ إلى ١٠٠٪ مقارنةً بأقوى ميل في فترة القياس
(قوي / متوسط / ضعيف / محايد)
• موضع النطاق — أين يقع السعر داخل النطاقات الخارجية
(تشبّع / النطاق العلوي / الوسط / النطاق السفلي)
• الفلاتر — توافق السريع مع البطيء (في وضع الفلتر المزدوج)
• الإشارة — الانعكاس النشط على الشمعة الحالية
── طريقة الاستخدام ──────────────────────────────────────────
• تداول مع لون الخط، واعتبر لحظة الانعكاس هي إشارة التحرّك.
• فضّل الدخول عندما تكون القوة «قوي» أو «متوسط»؛ قراءة «محايد» غالباً تعني
سوقاً عرضياً تكون فيه الانعكاسات أقل موثوقية.
• ظهور «تشبّع» في موضع النطاق يعني أن السعر امتدّ إلى النطاق الخارجي —
مفيد لجني جزء من الأرباح أو انتظار الارتداد بدل المطاردة.
• فعّل الفلتر المزدوج للحصول على سياق الفريم الأكبر، وخذ الإشارات فقط
عندما تُظهر اللوحة «متوافق».
── الإعدادات ────────────────────────────────────────────────
جميع الإعدادات مكتوبة بالإنجليزية والعربية معاً.
• طول الفلتر — الأقل = أسرع وإشارات أكثر، والأعلى = أنعم
(الافتراضي ٢٥؛ جرّب ٥٠–٨٠ على الفريمات الصغيرة، و١٠–٢٠ للمضاربة السريعة)
• طول الفلتر البطيء — فلتر التأكيد (الافتراضي ٨٠)
• الألوان، وشفافية التعبئة، وتلوين الشموع
• موضع اللوحة وحجمها ولغتها (EN / AR)
── التنبيهات ────────────────────────────────────────────────
• اتجاه صاعد / اتجاه هابط (انعكاس الميل)
• تقاطع صاعد / تقاطع هابط للفلتر السريع (في الفلتر المزدوج)
كل التنبيهات تُطلق مرة واحدة عند إغلاق الشمعة، وتتضمّن الرمز والفريم والسعر.
لغة اللوحة (EN / AR) تتحكّم أيضاً في لغة نص التنبيه.
يعمل على جميع الرموز وجميع الفريمات الزمنية.
إخلاء مسؤولية: هذا المؤشر لأغراض تعليمية وتحليلية فقط، وليس نصيحة مالية.
لا يوجد مؤشر يتنبأ بالمستقبل — التزم دائماً بإدارة رأس المال الخاصة بك. Indikator

Session Stats I EonMetrics Session Stats by EonMetrics
Every market has session folklore: "Asia is quiet", "London sweeps the overnight range", "the New York morning makes the high or low of the day". This tool replaces the folklore with numbers — it measures how each session has actually behaved on YOUR symbol, on YOUR chart's history, and shows the result in one table.
🔶 WHAT THIS TOOL IS AND IS NOT
This is a statistics dashboard, not a signal generator. It draws no entries, no targets, and it does not predict anything. It counts what already happened, so you can judge whether a session tendency on your instrument is real or imagined. All statistics are computed from completed sessions on confirmed bars. The only element that moves intrabar is the TODAY row, which is clearly labeled LIVE while a session is still open.
🔶 WHY THESE METRICS ARE ONE SCRIPT, NOT SEVERAL
Every row of the table answers the same single question — "what does this session usually do here?" — from a different side: how much it moves (range), where it sits in the day's structure (high/low of day), which way it leans (bull close, continuation), and how much participation it carries (volume share). Splitting these apart would leave each number without the context that makes it readable. The TODAY row then compares the current session against that same measured history, which is only possible because the history and the live reading live in one engine.
🔶 WHAT IT MEASURES
For up to four configurable sessions (defaults: Asia, London, NY AM, NY PM — New York time), over up to 500 stored trading days:
- Days (n) — the sample size behind every number in that column. Small samples (under ~20) are flagged in orange, because statistics on a handful of days are weak. If a number matters to you, check its n first.
- Avg Range and Median Range — the session's range expressed as a percent of the daily ATR, so quiet and violent weeks can be averaged together honestly. The median is shown next to the average on purpose: one news day can inflate an average, but it cannot drag a median. A big gap between the two tells you the session's "typical" day is calmer than its average suggests.
- High of Day / Low of Day — how often the session contained the trading day's extreme. A star marks the most frequent session in each row.
- Bull Close — how often the session closed above its open. Near 50% means no directional lean worth talking about.
- Continuation — how often the session repeated the direction of its own previous occurrence. Above 50%: the session tends to continue its behavior day over day; below: it tends to alternate.
- Vol Share — the session's average share of the whole trading day's volume.
- TODAY — the current session's range as a percent of daily ATR, plus its percentile within that session's own history. "62% (88th)" reads: today's London has already covered 62% of a normal day's range, which is larger than 88% of past Londons in the sample.
A weekday filter (Mon-Sun checkboxes) restricts the whole sample to the days you care about — Fridays only, weekdays only, and so on.
🔶 HOW THE NUMBERS ARE BUILT
-------------------------
The trading day rolls over at 18:00 in the selected session timezone, so the Asia session that opens in the evening belongs to the day it actually shapes. The daily ATR used for normalization is built internally from those same trading days (previous completed days only), which keeps the "day" definition consistent on 24/7 markets and means the ATR value is fixed for the whole current day. The script uses no higher-timeframe data requests. Session records are written once, when the session completes on a confirmed bar, and never change afterwards.
🔶 HOW TO USE IT
1. Add it to an intraday chart (1-minute to 1-hour). Let the chart load as much history as your plan allows — more history, bigger sample.
2. Check the Days (n) row first. Then read the table column by column: which session moves, which one sets the day's extremes, which one leans.
3. Use the TODAY row during the session: a high percentile early in the window tells you this session is already unusual relative to its own history.
4. Two alerts are available: one fires when any tracked session closes, one when the live session's range first reaches your chosen percentile (default 90th) of its own history.
🔶 SETTINGS
Four session slots (on/off, name, window, color), session timezone, sample depth, daily ATR length, weekday filter, optional rows (median, continuation, volume share), table position/size/theme, background tint of the active session, and the alert percentile.
🔶 LIMITATIONS
Session statistics describe the past; they are tendencies, not guarantees, and they can change when market conditions change. On symbols without meaningful volume data the Vol Share row will be empty. The tool needs an intraday chart — on daily and higher timeframes there are no bars inside a session window to measure.
This tool is for analysis and education. It is not financial advice, and past behavior of a session does not guarantee its future behavior. Always do your own analysis and manage your own risk.
Indikator

Indikator

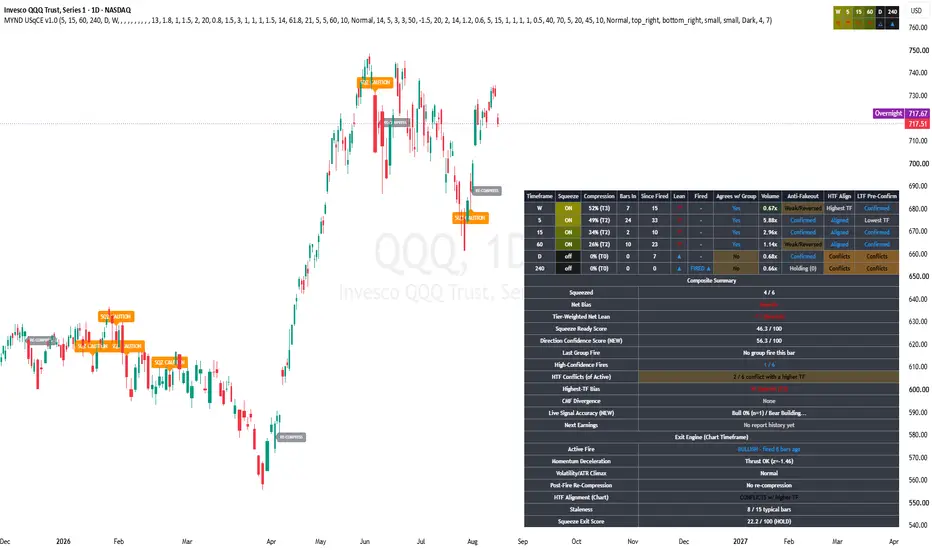
MYND Command Center Screener v2.0MYND Command Center Screener
Scan up to 30 watchlist symbols and rank them by general setup quality, compression readiness, or both - now with the answer to "which of my tickers is coiled and about to move."
WHAT IT DOES
This screener scans your configured watchlist (up to 30 symbols) and ranks them live in a table by score. v1.0 had one score - a general Alpha Score blending trend efficiency, relative volume, and volatility-regime fit. v2.0 adds a second, independent Squeeze Score - how tight, deep, and recently-fired each symbol's own compression engine reads - plus a Composite Score blending both, and a Rank By dropdown so you choose which question the table answers.
HOW IT WORKS
Each symbol is pulled once per bar (1 request.security() call each, 30 total) and run through two scoring engines. The Alpha Score checks how efficiently price has been moving, whether volume confirms it, and whether volatility sits in a tradeable middle ground. The Squeeze Score runs the same TTM-Squeeze-Pro-style 3-tier compression test used in MYND Ultimate Squeeze Confluence & Exit Dashboard (Bollinger Band inside 3 nested Keltner Channel bands) and blends compression depth, tier, and recent-fire status into a 0-100 read. A new Confluence column checks whether the two engines' directional reads agree, and a Rank Δ column tracks how fast each symbol is climbing or falling in the ranking itself.
KEY FEATURES
Two independent 0-100 scores (Alpha, Squeeze) plus a configurable-weight Composite Score and a Rank By selector. A Confluence column and a compression Tier column. Rank Δ tracking showing rank momentum bar to bar. A Watchlist Override for a fast all-on/all-off bulk switch without losing your individual per-symbol settings. A table that automatically sizes itself to only the symbols currently in use - no blank rows. Score columns display as "NN.N / 100" and Tier as "T# (#/3)" so the scale is always visible. Light/Dark theme presets plus a Colorblind-Safe Okabe-Ito option. Full tooltips throughout.
HOW TO USE IT
Configure your watchlist (20 symbols enabled by default). Set Rank By to Composite for a blended "good setup AND coiled" ranking, or switch to Squeeze Score alone if you specifically want the tightest coils regardless of general trend quality. Watch for symbols with a high Squeeze Score, Tier 3, and Confluence = Yes - the strongest combined read this tool can give. A fast-climbing Rank Δ can flag a symbol worth attention before it reaches the top of the table. Use the Watchlist Override dropdown for a quick "scan everything" or "quiet the table" moment without touching your 30 individual checkboxes - switch back to "Use Individual Toggles" and your prior per-symbol setup returns exactly as you left it.
SETTINGS WORTH TUNING FIRST
Rank By and the two Composite Weight inputs - the core dial for what "best" means in your table. Squeeze Score Threshold for the Newly Squeeze-Ready alert - your sensitivity for the compression-specific alert.
ALERTS
4 alertcondition()s (Watchlist Strength Rising/Falling, Symbol Entered Top N, Symbol Newly Squeeze-Ready) plus a combo bundle, and 1 dynamic alert() for leadership changes (set up via TradingView's "Any alert() function call" condition, not the named dropdown).
This tool can only tell you what trend/volume/volatility/compression behavior has looked like recently across your watchlist - it is not a guarantee of future performance. This tool is provided for informational and educational purposes and does not constitute financial advice. Trading involves risk; past performance and historical patterns do not guarantee future results. Indikator

Luna ATM Approach 100pt Hard Switch ContinuationLuna ATM Approach — 100pt Hard Switch Continuation
This indicator is built around the ATM session model and is designed to identify both ATM reversal opportunities and strong continuation conditions during the Asia, AM, and PM trading sessions.
The model automatically builds the ATM High and ATM Low using fixed New York session times and then monitors price action during the corresponding execution window.
ATM SESSION WINDOWS — NEW YORK TIME
Asia ATM Range:
6:00 PM – 7:00 PM
Execution:
7:00 PM – 8:30 PM
AM ATM Range:
7:00 AM – 9:30 AM
Execution:
9:30 AM – 11:00 AM
PM ATM Range:
11:30 AM – 1:30 PM
Execution:
1:30 PM – 3:00 PM
ATM REVERSAL MODEL
The reversal model begins after price sweeps either the ATM High or ATM Low.
ATM High Sweep:
Looks for a SHORT reversal.
ATM Low Sweep:
Looks for a LONG reversal.
Rather than waiting for a limit entry or a retest of the gap, the indicator looks for the inversion of a Significant FVG.
Once a qualifying Significant FVG becomes an IFVG, the indicator enters immediately on the confirmed candle close.
Reversal sequence:
ATM Liquidity Sweep
→ Significant FVG
→ FVG Inversion / IFVG
→ Immediate Reversal Entry
There is no limit order and no additional FVG retest required.
The indicator also displays market structure shift information for additional context.
Reversal stops can be based on the sweep swing or IFVG invalidation.
The default reversal target is the opposing ATM liquidity, with an optional fixed-RR target available.
100-POINT HARD SWITCH
The most important feature of this version is the automatic reversal-to-continuation regime switch.
If price expands 100 points above the ATM High after an ATM High sweep:
ATM High + 100 Points
→ Reversal SHORT model is immediately disabled
→ Indicator permanently switches to CONTINUATION LONG mode for that ATM session.
If price expands 100 points below the ATM Low after an ATM Low sweep:
ATM Low - 100 Points
→ Reversal LONG model is immediately disabled
→ Indicator permanently switches to CONTINUATION SHORT mode for that ATM session.
Once the 100-point threshold has been reached, the indicator will no longer attempt to fade the move.
CONTINUATION MODEL
Continuation trades require evidence that the market is maintaining directional expansion.
CONTINUATION LONG:
ATM High +100 reached
→ Reversal shorts disabled
→ Wait for retracement into a bullish 1-minute OR 5-minute FVG
→ Identify the pullback swing low
→ Wait for bullish Break of Structure
→ Enter LONG immediately on the confirmed BOS close
→ Stop below the pullback swing low
→ Target 1:1 Risk-to-Reward
CONTINUATION SHORT:
ATM Low -100 reached
→ Reversal longs disabled
→ Wait for retracement into a bearish 1-minute OR 5-minute FVG
→ Identify the pullback swing high
→ Wait for bearish Break of Structure
→ Enter SHORT immediately on the confirmed BOS close
→ Stop above the pullback swing high
→ Target 1:1 Risk-to-Reward
MULTI-TIMEFRAME FVG CONTINUATION
The continuation engine can use either:
1-Minute FVG
OR
5-Minute FVG
A tap into either qualifying FVG can arm the BOS portion of the continuation model.
The indicator identifies which timeframe was used and displays the BOS level that must be broken before entry.
CHART DISPLAY
The indicator automatically displays:
ATM High / ATM Low
ATM range windows
Execution windows
Liquidity sweeps
MSS information
Significant IFVG used for reversal
100-point continuation regime switch
1m / 5m continuation FVG tap
Continuation BOS level
Entry
Stop Loss
Take Profit
Trade outcome labels
Entry, Stop Loss, and Take Profit are displayed as clean horizontal levels with compact labels to reduce chart clutter.
IMPORTANT
The 100-point threshold refers to actual index price points, not ticks.
For example:
ATM High = 20,000
Continuation Long Mode activates at 20,100.
ATM Low = 20,000
Continuation Short Mode activates at 19,900.
The continuation model is designed primarily around 1-minute execution while also scanning confirmed 5-minute FVG structure.
MODEL SUMMARY
REVERSAL:
ATM Sweep
→ Significant IFVG
→ Immediate Entry
→ Opposing ATM / Fixed RR Target
CONTINUATION:
ATM ±100 Points
→ Reversal Model OFF
→ 1m or 5m FVG Tap
→ BOS
→ Immediate Entry
→ Swing-Based Stop
→ 1:1 Target
This indicator is intended as a structured trading and educational tool. It does not guarantee profitable trades and should be used alongside proper risk management, testing, and trader discretion. Indikator

MYND Ultimate Squeeze Confluence & Exit Dashboard v1.0MYND Ultimate Squeeze Confluence & Exit Dashboard
Multi-timeframe squeeze confluence for catching coiled setups before they fire - now paired with a genuine chart-resolution Exit Engine that tells you when the ride is over.
WHAT IT DOES
This is a two-sided squeeze tool. The ENTRY side scans up to 15 independent, user-configurable timeframes at once for TTM-Squeeze-Pro-style compression (a 3-tier Bollinger-inside-Keltner read), and flags when several timeframes fire together in the same direction - true multi-timeframe "coiled and ready" confluence, not just a single-timeframe squeeze. The EXIT side runs at your chart's own resolution and watches an active fired trade for momentum deceleration, a volatility/ATR climax, fresh re-compression forming again, higher-timeframe alignment breaking down, and staleness - combined into a single Squeeze Exit Score and a HOLD/CAUTION/EXIT read.
HOW IT WORKS
Each of your 15 configured timeframes is checked for a Bollinger Band sitting inside 3 nested Keltner Channel bands (tightest to loosest = deeper compression tier). A squeeze "fires" when the bands release. The entry engine tallies how many timeframes are squeezed, how deep, which direction they lean, and whether fires are volume-confirmed and holding - rolled into a 0-100 Squeeze Ready Score and a separate Direction Confidence Score. An HTF Alignment check keeps you from entering a move on one timeframe that's firing into an opposing move on a higher one, with a mirrored LTF Pre-Confirm check for early lower-timeframe agreement. Once a trade fires on your chart's own timeframe, the Exit Engine takes over: it watches momentum's acceleration for signs of thrust fading, volume/range for a climax/rejection signature, the squeeze engine itself for fresh re-compression, and the higher timeframes for alignment breaking down - all weighted into the Squeeze Exit Score.
KEY FEATURES
A dynamic heatmap strip and detail table covering all 15 timeframes (tightest-first sort, HTF Align and LTF Pre-Confirm columns, volume/anti-fakeout confirmation). Squeeze Ready Score, Direction Confidence Score, and a rolling Live Signal Accuracy tracker split Bullish/Bearish. A dedicated Exit Engine section with 5 independent exit signals rolled into one Squeeze Exit Score and state. CMF/price divergence detection and a projected earnings countdown. Full Light/Dark/Custom theming plus a Colorblind-Safe Okabe-Ito option, complete color customization, and tooltips throughout.
HOW TO USE IT
Configure your 15 timeframes (defaults: 5m, 15m, 1H, 4H, Daily, Weekly) and watch the heatmap/table for multiple timeframes compressing together. When several fire the same direction with HTF alignment intact, that's your entry read - check the Direction Confidence Score for how clear the direction actually is, not just how coiled it is. Once you're in the trade, watch the Exit Engine section: CAUTION means tighten your management, EXIT means multiple exhaustion signals are agreeing.
SETTINGS WORTH TUNING FIRST
Minimum Timeframes Firing Same Direction for Alert - how many of your 15 need to agree before the entry alert fires. Squeeze Exit Score CAUTION/EXIT Levels - the sensitivity dial for the exit read. Typical Hold (bars) - set this to roughly your own usual swing hold length so the staleness flag means something on your timeframe.
ALERTS
9 alerts total, all standard alertcondition() alerts - no special setup required. Individual alerts cover Bullish/Bearish Multi-Timeframe Squeeze Fire, Squeeze Exit CAUTION/EXIT, Post-Fire Re-Compression Detected, and a Live Accuracy Warning. Three combo alerts bundle these down: ALL Entries, ALL Exits, and ALL Signals.
This tool can only tell you what squeeze/momentum/volatility behavior has looked like recently on this symbol/timeframe - it is not a guarantee of future performance. This tool is provided for informational and educational purposes and does not constitute financial advice. Trading involves risk; past performance and historical patterns do not guarantee future results. Indikator

Vol-Target Trend EngineWHAT IT DOES
VTTE is a leveraged-ETF allocation engine. It holds a 3x index ETF (built for TQQQ/UPRO) only during favorable regimes, and lets realized volatility set the position size. There is no entry signal being predicted anywhere in the script - the edge is the risk-allocation policy itself, which is why the system has almost no tunable surface to overfit.
HOW IT WORKS
1) REGIME GATE - the position exists only while price trades above its 200-day SMA. Leveraged ETFs suffer volatility decay fastest in downtrends; the gate removes the catastrophic left tail instead of trying to predict it. Below the SMA the system is 100% cash.
2) VOLATILITY TARGETING - exposure = min(100%, target vol / realized vol), using 20-day realized volatility annualized against a 45% target. This is the same architecture vol-control indices and risk-parity desks run: position size shrinks mechanically as volatility expands, which front-runs drawdowns because volatility clusters.
3) REBALANCING - weekly, inside a 10% tolerance band to keep turnover and commission drag low, with an immediate de-risk override when held exposure runs 1.5x over target. Regime flips act immediately.
BACKTEST PROPERTIES (fully disclosed)
0.05% commission per side, 1 tick slippage, fills on close, $10,000 initial. TQQQ daily Feb 2010 - Aug 2026: +3,862% realized net, profit factor 3.33, 155 rebalance events (67.7% profitable), max drawdown 41.9%. Buy-and-hold TQQQ returned more over the same window (+20,107%) but with multiple drawdowns beyond 80%; the S&P 500 returned roughly +630%. The honest comparison is CAGR ~26% at roughly half of buy-and-hold's worst drawdown.
WHAT WAS TESTED AND REJECTED
A faster variant (5-day vol estimate, de-risk any day of the week) was tested and REJECTED with numbers: turnover more than doubled, the system repeatedly sold volatility spikes at their lows and re-bought higher, net return fell from +3,862% to +2,158%, profit factor 3.33 to 1.98, and max drawdown got WORSE (41.9% to 49.6%). Slow rebalancing is a feature, not a limitation.
INPUTS
Realized vol lookback (20d), target annualized vol (45%), regime SMA length (200), rebalance band (10%), fast de-risk toggle.
LIMITATIONS
Single instrument, single history, in-sample. TQQQ's listed history begins in 2010 - a mostly secular-bull window; the regime gate carries the 2020 and 2022 stress periods, but the configuration has not been walk-forward validated yet. Treat every figure as an upper bound on expectancy, not a forecast. Not financial advice. Strategi

Segmented Momentum PeakSegmented Momentum Peak (SMP) by Chao Ivans
This indicator builds an adaptive momentum threshold by collecting peak and trough readings from a series of past time segments and averaging them into a reference. A current move is treated as significant only when it matches or exceeds what the instrument has historically been capable of producing.
Calculation
The process runs in four stages.
First , Rate of Change is measured on closing prices over a defined period. This value feeds everything that follows.
Second , the chart is divided into segments of a set length. From each segment, one highest reading and one lowest reading is taken. This repeats across the chosen number of segments, gathering a collection of peak samples and trough samples spanning a substantial stretch of history.
Third , all peak samples are averaged into an upper reference and all trough samples into a lower reference. Both are then divided by the sensitivity parameter to produce the working thresholds drawn on the panel.
Fourth , the system counts how many times ROC has broken those thresholds within a recent window of bars. A signal appears only when the count meets the required quota and the current bar is breaking as well.
Logic Behind the Formula
The approach used here is known as block maxima, where extreme values are drawn from each block of data and their distribution is studied. Peaks are used rather than a plain average because averaging every reading would be dominated by the far more numerous quiet bars, dragging the threshold too low and flooding the chart with signals. Collecting only peaks produces a threshold that reflects how strong a move the market has genuinely been capable of delivering.
A useful consequence is that the threshold is self scaling across instruments. On a sluggish asset it settles low on its own. On a volatile asset it rises accordingly. No recalibration is needed when switching markets.
The cluster counting layer exists because a single threshold break is often nothing more than a momentary spike. When real pressure enters, breaks tend to arrive repeatedly within a short span. The quota requirement is what separates the two.
Function
The indicator identifies momentum that is statistically unusual relative to the instrument's own history, then filters it further through a repetition requirement. The output is a directional marker on the main chart whenever buying or selling pressure is confirmed as sustained.
How to Use
The lower panel shows three elements. Columns represent the ROC reading, turning green when breaking the upper threshold, red when breaking the lower threshold, and grey when sitting between them. Two thick lines represent the adaptive thresholds, which shift as volatility conditions change.
Pay attention to the threshold line colours. A blue upper line and a purple lower line indicate the thresholds sit at a meaningful level, so any break carries weight. A black line warns that the threshold has collapsed to a very low level, which typically happens in thin or dormant markets. Breaks come easily under those conditions but signify little, so signals should be ignored or treated with caution.
A green triangle below the bar marks a confirmed cluster of buying pressure. A red triangle above the bar marks selling pressure. These triangles are pressure markers, not entry commands. Use them to confirm a plan already built from price structure rather than as a standalone reason to open a position.
Tuning Guide
Start with sensitivity. If signals feel too scarce, raise it gradually. If the chart gets crowded, lower it.
Segment Length shapes the character of the threshold. Small values give a nimble threshold that tracks current conditions. Large values give one that only shifts when volatility changes on a broad scale.
Number of Segments Sampled controls stability. A large sample count makes the threshold resistant to one or two extreme events, but also slower to adapt when the market regime turns.
Cluster Window and Minimum Hits work as a pair. A narrow window with a high quota demands tightly packed pressure and produces the fewest but firmest signals. A wide window with a low quota is permissive and produces more. Indikator

Fibonacci Trend Continuation Signals [AlgoAlpha]🟠 OVERVIEW
Fibonacci Trend Continuation Signals maps Fibonacci retracement levels inside an adaptive trend structure. It combines a smoothed price midline, volatility-based outer bands, and Fibonacci ratios to show where price is trading within the current bullish or bearish trend range.
The trend changes only when price moves beyond a volatility-adjusted outer band. Once a direction is active, the script projects 0.236, 0.382, 0.500, 0.618, and 0.786 levels between the active outer band and the midline. This creates a moving Fibonacci framework that adjusts as price and volatility change.
Continuation signals appear when price closes back through an enabled Fibonacci level in the direction of the active trend. This lets traders use retracements within an established trend instead of treating each Fibonacci level as a fixed reversal point.
🟠 CONCEPTS
Trend Midline — An exponential moving average of closing price. It forms the central reference for the trend structure and the endpoint of the Fibonacci range.
Volatility Bands — Outer boundaries placed above and below the midline using a smoothed measure of the high-to-low price range. Price crossing an outer band changes the active trend direction.
Fibonacci Trend Range — The distance between the active outer band and the midline. In bullish trends, levels are measured upward from the lower band. In bearish trends, they are measured downward from the upper band.
Fibonacci Levels — The 0.236, 0.382, 0.500, 0.618, and 0.786 ratios divide the active trend range into retracement zones that move with the underlying trend structure.
Continuation Signal — A bullish signal occurs when price closes upward through an enabled Fibonacci level during a bullish trend. A bearish signal occurs when price closes downward through an enabled Fibonacci level during a bearish trend.
🟠 FEATURES
Adaptive Fibonacci Profile — Displays five configurable Fibonacci levels between the active volatility band and trend midline.
Trend Continuation Signals — Shows bullish and bearish markers when price closes through an enabled Fibonacci level in the direction of the active trend.
Current Level Labels — Shows the current price value of each enabled Fibonacci level at the latest bar.
Trend Change Markers — Marks the Fibonacci structure when a new bullish or bearish trend begins.
🟠 HOW TO USE
Identify the active trend structure — A bullish structure projects Fibonacci levels from the lower band toward the midline, while a bearish structure projects them from the upper band toward the midline.
Watch price during a retracement — Use the displayed Fibonacci zones to see how far price has moved through the active trend range.
Look for continuation signals — An upward triangle shows that price crossed above an enabled Fibonacci level during a bullish trend. A downward triangle shows the equivalent bearish close below a level.
Compare signals with price structure — Use nearby swing points, support, resistance, or your existing confirmation method before acting on a continuation signal.
Adjust Midline Length, Pivot Length, and Band Width to control how quickly the trend framework responds to price and how wide its outer boundaries are.
Enable or disable individual Fibonacci levels to keep only the retracement levels relevant to your method.
🟠 CONCLUSION
Fibonacci Trend Continuation Signals combines volatility-based trend detection with adaptive Fibonacci retracement levels and directional continuation signals. It gives traders a moving reference for measuring pullbacks and identifying closes that resume movement in the active trend direction. Indikator

FVG Intelligence - Fill Probability AI [Dots3Red]📦 FVG INTELLIGENCE - FILL PROBABILITY AI
Every Fair Value Gap tool draws the gap. None of them tell you what usually happens to it. This script keeps records instead — every gap that appears on your chart is tracked all the way to its resolution, and when a new one forms, the script reports what the most similar past gaps on this chart actually did.
✨ WHY THIS MATTERS
"Gaps get filled" is one of the most repeated assumptions in SMC trading — but it's rarely checked against the actual chart in front of you. Some instruments fill gaps quickly and reliably. Others leave them open for a long time, or never fill them at all. A gap formed on heavy volume during a strong trend behaves differently than one formed on quiet, choppy conditions.
This script doesn't assume any of that. It measures it. Every gap that resolves — filled or expired — becomes a data point: how big it was, what volume looked like when it formed, how volatile the market was, and where price sat relative to trend. When the next gap appears, the script finds the most similar historical gaps and reports their real outcomes.
📊 Fill 74% | ~6 bars | N=52
That reads as: of the 52 most similar gaps this chart has produced, 74% filled, taking about 6 bars on average. Measured history, not an assumption that "gaps always fill."
⚙️ HOW IT WORKS
📦 Detection — the standard 3-bar imbalance definition: a bullish gap exists when the current low sits above the high from two bars back, leaving an untraded price zone between them. Bearish gaps are the mirror. A minimum size filter (in ATR) discards micro-imbalances too small to carry real information.
🧠 The KNN engine — every gap is stored as five measurements the moment it forms: direction, size relative to ATR, volume behavior, volatility context, and position relative to the trend. When the gap resolves, the actual outcome — filled or not, and how many bars it took — is recorded against those five measurements. A brand-new gap is compared against this stored history, and the K most similar past gaps vote on fill probability and expected duration.
🎯 Fill definition — a gap counts as filled when price fully traverses it, reaching the far edge. This is the strictest standard (some traders count a midpoint touch as "filled" too) — deliberately conservative so the statistics mean exactly what they say.
📐 Near edge vs. far edge — each gap is drawn with two distinct boundaries. The edge price actually returns to first (the "near" edge) is shown with a solid line; the origin edge (the "far" edge, the one that defines a full fill) is shown dashed and dimmer. The fill inside fades from strongest near the solid edge to faintest near the dashed one, visually encoding which boundary carries more weight.
🔒 Non-repainting — detection, fill-checking, and outcome grading all happen strictly on confirmed bars. A gap's KNN read is calculated once, at the moment it forms, and its label stays fixed at that spot — it does not shift, recalculate, or repaint as the chart moves forward.
🧭 HOW TO USE
1️⃣ Check the sample count before trusting the percentage. "Fill 74% | N=52" is a real pattern; "Fill 74% | N=6" could easily be noise. The label always shows N so you can judge for yourself — the script won't display a probability at all until enough history exists ("Training…" appears instead).
2️⃣ Use the average bars figure as a timing expectation, not a countdown. "~6 bars" is the mean of gaps that did fill — it tells you the typical pace, not a guaranteed deadline for this specific gap.
3️⃣ Read the near/far edge distinction on the chart itself. The solid line is the boundary price will most likely interact with first; the dashed line is what a genuine full fill requires. A gap that's touched its solid edge but not yet reached the dashed one is still open, by this script's strict definition.
4️⃣ Watch the dashboard's global fill rate for chart-level context. Beyond any single gap, it tracks what percentage of every recorded gap on this chart has filled overall — useful for gauging whether this instrument tends to leave gaps open or close them reliably.
5️⃣ Adjust the fill window to the timeframe. A 30-bar window means something very different on a 1-minute chart versus a daily chart — tune it so "expired unfilled" reflects a genuinely meaningful amount of time for what you're trading.
🛠️ SETTINGS
📦 FVG Detection
• Min Gap Size — smallest imbalance the script will bother tracking
• Fill Window — bars allowed for a gap to fill before it's graded as expired
• Max Gaps Shown — how many open/recent gaps stay on the chart at once
📊 KNN Engine
• K Neighbors — how many similar past gaps vote on the current one
• Max / Min Training Samples — memory cap and the minimum before probabilities display
• ATR Baseline Period, Trend MA Length — the context windows used in matching
🎨 Visualization
• Keep Filled Gaps Visible — leave resolved gaps on the chart as faint gray outlines, or clear them for a cleaner view
• KNN Labels on Gaps — toggle the fill-probability readout
• Box Extension — how far each gap's zone projects forward while still open
🖥️ Dashboard
• Show/hide, position — open gap count by direction, chart-wide fill rate, KNN training progress, and the active fill window
📝 NOTES
Gap frequency and fill behavior vary significantly by instrument, timeframe, and market conditions — a volatile, fast-moving asset will accumulate the sample size needed for meaningful probabilities much faster than a slow, quiet one. On a new chart, expect a number of gaps to pass before the KNN read becomes genuinely informative rather than a placeholder.
⚠️ DISCLAIMER
This is an analytical and visualization tool. It does not generate trade signals and does not constitute financial advice. Historical fill rates do not guarantee how any specific future gap will resolve. Indikator

Ticker Tag [theUltimator5]This indicator is a compact, dynamic, over-engineered... tag. It was designed to show a bunch of information about the chart at a glance rather than actually having to look at the chart for yourself.
The tag is designed to be as visually pleasing as possible ( by my standards, at least ) while providing the maximum amount of information that can be mentally absorbed with two seconds after glancing at the tag.
If you don't care about the chart information as much, you can customize it in the settings to turn it into a logo-style tag that can be horizontally and vertically adjusted relative to the chart with your own custom text.
At its center is the current ticker symbol, surrounded by directional corner brackets and accompanied by the company name, an optional company-specific tagline, the current price, daily percentage change, and a configurable five-segment strength meter.
By default, the center of the tag displays the chart's ticker symbol.
The ticker can be replaced with custom Logo Text through the indicator settings if a different abbreviation or label is preferred.
The company-name line can be independently enabled or disabled (disabled in image above)
Ticker Tag contains a large internal library of company-specific market-themed taglines. When a supported ticker is detected, an appropriate phrase is automatically displayed beneath the company name. The tagline is displayed in an italicized style to visually separate it from the company name.
Automatic taglines can be disabled independently from the company-name display, and users can enter their own 'Bottom Tagline Override', which is A custom tagline takes precedence over the automatically mapped phrase.
If no predefined tagline exists for a ticker, the indicator simply omits that line rather than inserting a generic fallback.
Above the central ticker, the indicator normally displays the current price using the symbol's native minimum tick formatting.
The price is dynamically colored according to the current day's performance:
Positive day: Positive Color (Green default)
Negative day: Negative Color (Red default)
Consolidating/low-directionality condition: White (special condition)
A custom top text can also replace the live price entirely. When custom top text is used, it uses its own configurable color rather than the market-state coloring applied to the live price.
The lower portion of the tag displays the live percentage change from the previous daily close.
The calculation is:
Current Price / Previous Daily Close − 1
and is displayed as a percentage.
The percentage is colored using the selected Positive and Negative colors so the current day's direction can be identified at a glance.
This daily calculation is performed from daily-timeframe data even when the indicator is being viewed on an intraday chart.
Four brackets frame the central ticker and act as a simple visual representation of the current day's direction.
The brackets use the Positive Color when the current price is above the previous daily close and the Negative Color when price is below it.
When a previous daily close is unavailable, the current daily open is used as the directional reference.
These brackets are separate from the strength meter and therefore provide a quick daily directional cue regardless of which signal is selected for the meter.
Below the main ticker symbol is a five-segment strength meter. This is designed to give a very quick price action indication for the current timeframe
The meter converts the selected market signal into a normalized 0–100 strength score and progressively fills from left to right.
The default color progression moves from weak to strong:
Red → Orange → Yellow → Lime → Green
Unfilled segments remain dimmed.
Each segment's color can be customized independently.
The meter is intentionally progressive. If the fourth segment is illuminated, for example, the first three segments are illuminated as well.
Selectable Strength Signals
The strength meter can be driven by any of six different calculations:
1) Combined Score
2) RSI
3) MACD
4) Bollinger Bands
5) Stochastic
6) ATR
A small letter beside the meter identifies the selected source:
C - Combined Score
R - RSI
M - MACD
B - Bollinger Bands
S - Stochastic
A - ATR
This makes it possible to change the meter's interpretation without losing track of the active calculation.
Several of the meter's underlying signals naturally operate on very different numerical scales.
To make them comparable, Ticker Tag normalizes them into a common 0–100 framework.
For unbounded signals, the indicator evaluates the signal relative to its own historical mean and standard deviation:
Normalized Score = 50 + 15 × Z-Score
The result is then constrained between 0 and 100.
Under this system:
50 represents approximately neutral or historically average behavior.
Values progressively above 50 represent increasingly strong positive conditions.
Values progressively below 50 represent increasingly weak or negative conditions.
The normalization lookback is user configurable and defaults to 252 bars (1-year in daily timeframe)
Because this strength meter operates on the current chart timeframe, changing the chart timeframe also changes the context being measured.
The default meter mode is Combined Score.
The combined score combines five different measurements into an equal-weighted composite:
1) RSI - A standard 14-period Relative Strength Index is calculated and then statistically normalized relative to its own history.
2) MACD - The difference between the standard MACD line and signal line using : 12 / 26 / 9 settings is normalized relative to its historical distribution.
3) Bollinger Bands - A 20-period Bollinger Band with a two-standard-deviation envelope is used to determine where price sits within the band structure. That position is then normalized relative to its historical behavior.
4) Stochastic - A 14-period Stochastic calculation with a three-period smoothing component contributes a direct 0–100 momentum measurement.
5) ATR Directional Volatility - ATR is combined with directional movement information rather than being treated as pure volatility alone.
The indicator considers the difference between +DI and −DI and scales it according to the instrument's ATR as a percentage of price relative to its historical ATR behavior. This produces a directional-volatility measurement intended to distinguish volatility associated with bullish directional pressure from volatility associated with bearish directional pressure.
The five normalized components are then equally weighted
The result drives the five-segment meter.
The Combined Score is intended to provide a broader view of current market strength than any single momentum calculation alone.
Consolidation Detection
Ticker Tag can also visually identify periods where directional trend strength becomes weak.
When white/Bold Price on Low ADX is enabled (on by default), the live price changes to bold white text when the indicator's consolidation criteria are satisfied.
The condition evaluates multiple conditions that all need to result in true:
1) ADX below the user-defined low threshold
2) +DI below 25
3) −DI below 25
4) relatively little separation between the directional components
This state is intended to visually distinguish low-directionality or consolidating conditions from ordinary bullish and bearish price movement.
It affects only the default live-price display. If custom Top Text is entered, that text retains its selected custom color.
Positioning
Ticker Tag is positioned beyond the most recent chart bar rather than directly on top of historical candles. The horizontal position begins one bar beyond the last chart bar and then applies the user-defined **Offset from Right Edge**.
The default horizontal offset is 30 bars.
Vertical positioning is volatility aware.
Instead of using a fixed percentage of price, the vertical offset is measured in multiples of ATR:
Tag Position = Current Price + Vertical Offset × ATR
A value of:
0 positions the tag near current price.
A positive value moves it above current price.
A negative value moves it below current price.
Because the offset scales with ATR, its placement adapts more naturally across instruments with very different prices and volatility characteristics.
The ATR length used for positioning is independently configurable.
In summary (if you read this far), the Ticker Tag is a compact, dynamic, over-engineered... tag. Indikator

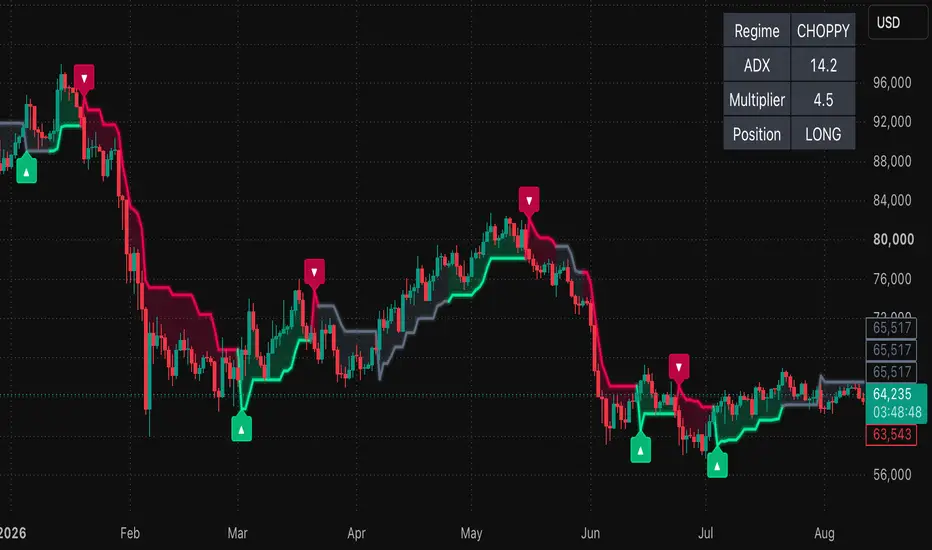
TrendShift | Supertrend + ADX Regime-Adaptive StrategyOverview
Most Supertrend strategies use one fixed ATR multiplier for every market condition — which means it's either too tight (whipsawed in chop) or too wide (late to catch real trends). TrendShift fixes this by reading market regime in real time with ADX and automatically shifting the Supertrend multiplier to match: tight and responsive when the market is trending, wide and defensive (or disabled entirely) when it's choppy. The strategy essentially "changes gears" as conditions change, and shows you exactly which gear it's in.
Features
ADX-based regime detection — classifies the market as Trending, Choppy, or Neutral, with a built-in hysteresis zone so the regime doesn't flicker back and forth near the threshold.
Dynamic Supertrend multiplier — automatically tightens (fast entries) in trends and widens (fewer false signals) in chop, recalculated live every bar.
Signal gating — Supertrend flips during choppy conditions are suppressed by default; no trades fire on noise.
Risk-based position sizing — every trade risks a fixed % of equity, sized off the actual stop distance (the Supertrend line), so trade size adapts to current volatility automatically.
Trailing stop + optional R-multiple take profit — the Supertrend line itself trails the stop; an optional fixed reward-to-risk target can close the trade early.
Optional chop-flatten & max-bars-in-trade exits — extra safety nets for getting out of dead trades.
Clean, glowing trend line with gradient fill — colored green/red by direction, turns gray and flat in chop, with minimal arrow labels only on actual signal flips (no clutter).
Live dashboard — a small on-chart table showing current Regime, ADX value, Active Multiplier, and Position status, so you can literally watch the strategy shift gears.
How it works
ADX is calculated each bar and compared against two thresholds (default: 25 trending / 20 choppy).
Based on that regime, the strategy picks a tight multiplier (trending) or a wide one (choppy) for the Supertrend calculation — held steady in the neutral zone to avoid jitter.
Supertrend is recalculated using this adaptive multiplier, and a flip in trend direction becomes a trade signal only if the current regime allows new entries.
Position size is calculated from your risk % input and the distance from price to the Supertrend line, so every trade risks roughly the same account %, regardless of how wide the current band is.
The Supertrend line trails your stop; an optional R-multiple limit order banks profit early if enabled.
Tips
Start with the default ADX thresholds (20/25) and multipliers (1.75 tight / 4.5 wide) — they're tuned to be reasonable across timeframes, but always re-check on your specific instrument.
On lower timeframes or noisier symbols, consider raising the choppy threshold or widening the "wide" multiplier further — chop is more common intraday.
Leave "Disable new entries in choppy regime" ON for cleaner equity curves; turn it off if you want to see how the strategy performs without the filter (useful for comparison).
The dashboard's ADX/Multiplier readout is the fastest way to sanity-check whether the strategy is behaving as expected on a given chart — if it feels like it's not trading, check whether it's stuck in "CHOPPY."
Combine with your own higher-timeframe bias filter if you want extra confluence; the strategy doesn't currently check higher-timeframe trend.
This is a strategy script (has backtest results), not just a visual indicator — use the Strategy Tester tab to evaluate performance before live use.
Strategi

RS Leader - Early Breakout RadarRS Leader - Early Breakout Radar identifies stocks demonstrating exceptional relative strength before a conventional price breakout occurs.
The indicator compares the current symbol with a selectable market benchmark, using SPY by default. It searches for situations in which the relative-strength ratio is near a long-term high while the stock remains in a tight consolidation beneath its previous price high. This combination can help identify securities outperforming the broader market before that leadership becomes obvious from price alone.
RS Leader is different from the RSI oscillator. Its relative-strength calculation is:
Stock Price ÷ Benchmark Price
RS Leader Score
Each stock receives a dynamic score from 1 to 100:
• Relative-strength leadership: 40 points
• Proximity to the breakout level: 20 points
• Price-range contraction: 15 points
• Moving-average structure: 15 points
• Volume behavior: 10 points
A default minimum score of 70 is required before an RS Leader signal can appear. All requirements and scoring thresholds can be adjusted in the indicator settings.
Signal Interpretation
• Blue RS LEADER label: Relative strength is near a long-term high while price remains tightly consolidated below resistance.
• Blue line: The nearby price level that must be exceeded for a potential breakout.
• Green BREAKOUT label: Price closed above the prior resistance level following an active RS Leader setup.
• Blue background shading: Optional highlighting of bars that currently satisfy the complete setup.
Dashboard Colors
• Green: Condition is favorable or confirmed.
• Blue: An active RS Leader setup meets the minimum score.
• Orange: Condition is developing, neutral or requires caution.
• Red: Condition is not currently satisfied.
The dashboard displays the current RS Leader Score, relative-strength status, distance from the price high, consolidation width, moving-average alignment, relative volume and selected benchmark.
The indicator uses confirmed closing-bar information and does not intentionally use future data. Signals can still fail, and historical relationships do not guarantee future results. Relative strength may deteriorate, apparent breakouts may reverse, and market or company-specific events can materially affect price behavior.
RS Leader is provided solely for educational and informational purposes. It does not constitute investment advice, a recommendation to buy or sell any security, or a guarantee of future performance. Users should independently evaluate market conditions, liquidity, earnings dates, volatility and personal risk tolerance before making any financial decision. Indikator

Universal Trade Manager Template ATR Trailing SL TP with AlertsA modular, signal-agnostic trade management engine. This template does not generate trade entries itself. Instead, it takes a Long/Short trigger from any compatible TradingView indicator and handles everything downstream — initial stop-loss placement, ATR-based trailing, TP1/TP2 tracking, trade timeouts, and webhook-ready JSON alerts for automated execution.
It is designed as a reusable management layer: connect the same tested trade-management logic to different signal-generating indicators without duplicating the underlying code.
HOW IT WORKS
Connect any signal source Point the Long Trigger and Short Trigger inputs to the corresponding alert conditions from your signal indicator.
Controlled entry timing By default, the template applies a one-bar offset: a signal confirmed on bar N triggers the entry on the open of bar N+1. This follows standard non-repainting execution. The offset can be disabled when the connected indicator generates its trigger after bar close.
Flexible initial stop-loss Set the initial SL using an ATR multiple, or pull it from an external structural level such as a swing high/low or FVG edge. An optional opposite-level input can widen the stop to a structural floor/ceiling, but will never tighten it.
A third Initial SL Mode, Last Pivot High/Low, is also available: instead of only ATR-based or external-source stops, the stop can be set to the highest high (shorts) / lowest low (longs) over a lookback window. At 1x multiplier it sits exactly on that level, with the multiplier available to tighten or widen from there. Falls back to the ATR stop if the lookback window isn't fully available yet.
Two trailing modes Choose between:
Continuous: re-evaluates the trailing stop on every eligible bar after the configured delay.
Stepped: updates only at fixed bar intervals, useful for reducing SL-update noise in choppy markets. Stepped trailing now has its own configurable alert, with a message ready to use with platforms that can consume webhook signals to execute orders on your broker or prop account.
VISUALS
Entry Zone Displays the initial SL/TP1 range at the moment of entry. The zone remains frozen even when the trailing stop subsequently moves.
Live trade status Entry zones are color-coded:
Gray — trade still open or closed BE
Green — TP1 reached
Red — initial SL breached
Zone Stats Table Tracks the results of the most recent entry zones, including TP, SL and neutral/BE outcomes, together with the hit rate. This provides a quick view of how the connected signal is performing without relying on the Strategy Tester.
Live management levels Separate trailing SL, TP1 and TP2 lines are plotted on the chart, with pip-distance labels for both the entry zone and current trailing stop, plus a display label for the trailing stop itself.
ALERTS & AUTOMATION
The template provides seven alert conditions:
Long Entry
Short Entry
Stop Loss Update
Stop Loss Hit
TP1 Hit
TP2 Hit
Timeout Exit
Each alert includes a pre-built JSON payload with TradingView placeholders, capturing the relevant values at the exact moment the alert fires.
The payload is designed as a starting point for integration with platforms which can consume webhook signals to execute orders on your broker or prop account. Fields such as traderIdKey, tradeSide, relativeTakeProfit, and relativeStopLoss can be adapted to match the configuration and credentials required by your chosen platform.
This allows the trade-management layer to send automated execution instructions directly from TradingView to your broker or prop firm account, without any manual order entry.
NON-REPAINTING DESIGN
All internal trade-management logic uses confirmed-bar data and proper offsetting.
There is no lookahead in the entry/exit logic, and the alert payload captures values when the event actually occurs rather than relying on values that may change later as the chart updates.
IMPORTANT
This is a trade-management layer, not a signal generator.
It will not produce entries or plot trade-management levels until it is connected to a compatible indicator source through input.source().
For educational and informational purposes only. This template is not financial advice. Test thoroughly in TradingView and on a demo account before connecting it to any live automated execution system. Indikator

Trend Trail, Trailing Stop & Buy Sell Signals [LunqFX]An ATR trailing stop — the trend-following construction most traders know as SuperTrend — breaks in the same place every time. Price stops trending, the trailing stop gets clipped from both sides, and it prints a buy, a sell, a buy and a sell inside twenty bars. Every one of those is a false trend reversal, and the logic is not wrong: it is being asked a question the market is not answering.
This is an open-source modification of the classic ATR based SuperTrend, and it asks that question first. Before it will give you a buy or sell signal it measures whether there is a trend to trail at all. When there is not, the whole chart goes dark — the trailing stop disappears, the fill drops, the candles fall to grey, and no long entry or short entry prints.
And it does not ask you to take that on trust. A plain fixed-distance ATR trailing stop runs alongside it on the same data, and the panel shows both counts side by side with the difference worked out for you.
Included: an average true range trailing stop with adaptive distance, a self-calibrating trend regime filter, buy and sell signals with the stop level printed on every label, a dormant state that switches the chart off in ranges, a live dashboard, and alerts on every trend reversal.
❶ THE REGIME FILTER — what this adds to a SuperTrend
Trend strength is measured with the Kaufman Efficiency Ratio: the ground price actually covered, divided by the distance it travelled getting there. A clean leg scores near 1. The same distance walked back and forth scores near 0.
That raw ratio is useless as a threshold on its own, and this is where most attempts at this fail. Gold on a 30-minute chart runs an efficiency around 0.01 while the euro daily runs 0.40 — any fixed cutoff leaves the fast charts permanently asleep and the slow ones permanently awake. So the reading is scored as a PERCENTILE of the symbol's own recent history. The trail arms when efficiency reaches the top third of what this instrument normally manages, whatever that happens to be. One setting, no per-symbol tuning.
Two guards keep the state from flickering, because they catch different things. Hysteresis handles wobble around the threshold: once armed, the regime stays armed until efficiency drops clearly below the line. A minimum dwell time handles the other case — a clean spike that clears the threshold by a mile and drops straight back. Without both, a filter opens hundreds of regimes and ends up emitting more marks than the raw trail it was meant to quieten.
❷ DORMANCY — the trail does not exist in a range
This is stronger than dimming a colour. When no regime is live the trail is torn down completely, and it is rebuilt from the current price when one opens, taking its side from the move that woke it.
The reason is not cosmetic. A trail left running through a range turns over inside it, unseen, and the market then re-opens onto a direction that was decided while nobody was watching — a position with no entry behind it. Destroying and rebuilding means every segment on the chart begins with a real event, and every event gets a label.
What you see is a chart that is either lit or switched off. Grey candles, no line, no signal: there is nothing here to do, and you can read that from across the room.
❸ THE ATR TRAILING STOP AND ITS ADAPTIVE DISTANCE
The average true range sets the band width, and the trailing stop ratchets in the direction of the trend and never loosens — the same dynamic support and resistance line a SuperTrend gives you, flipping to a trend reversal when price closes through it. The stop level is printed on every buy and sell label, so the one number you need at the moment of a long entry or short entry is already on the chart.
The distance is not fixed. One multiple has to be either too tight for choppy conditions or too loose for a clean run — it cannot be right for both, so the distance widens as efficiency falls and tightens as it rises. Turn it off in the settings for a constant multiple.
❹ THE RECEIPT — a filter you can audit
A second trailing stop is computed on the same bars: fixed distance, no regime filter, nothing else — what an ordinary trailing stop would have done here. Its flip count sits in the panel next to this one's signal count, with the reduction calculated:
Signals here · plain trail 164 · 236 Noise removed −31%
Both numbers count the same thing — entries against entries. A state is not counted as a trade on either side. And when the result goes the wrong way the panel says "Noise ADDED" in red rather than quietly dropping the sign, because a panel that flatters its own script is worse than no panel.
Read it as what it is: a measure of how much less often this fires, not a claim about money. Fewer signals is not automatically better signals, and this number does not pretend otherwise.
❺ THE DASHBOARD
Direction and stop price in the header, trend strength as a 0–100 reading with a bar and the arming threshold beneath it, current stop distance in price and in ATR, and the two comparison rows. In the dormant state the header says so plainly and the stop row reads "no stop — dormant" rather than printing a number that does not exist.
HOW TO USE IT
1 — Trade the lit stretches, ignore the grey ones. That is the whole discipline the tool is built around, and it is the part most trend systems leave to you.
2 — Use the trail as the stop, not just as a signal line. The level on the label is where the stop goes; the panel keeps showing the distance in ATR as the trade runs, so you can see when the trail has tightened to the point of being one bar away.
3 — Set the arming threshold to your patience. At 65 you get the top third of this symbol's clean moves. Raise it to 75 and you will trade far less on far cleaner legs. This is the one setting worth changing.
4 — Read the comparison rows on your own instrument. If the reduction on your symbol and timeframe is small, the filter is not finding much to remove there — which is itself information about the instrument, not a reason to distrust the reading.
HOW IT WORKS
The average true range sets the band width; the mid price plus and minus that width form the raw bands, exactly as in a classic ATR trailing stop. Each band ratchets in the trend's favour and never against it, and price closing through the opposite band flips the direction — the trend reversal. Efficiency is the net move over the lookback divided by the summed absolute bar-to-bar movement, ranked as a percentile against its own history. The regime arms above the threshold with hysteresis and a minimum dwell, and outside a regime the trail is not computed at all.
Works on any symbol and any timeframe. The regime filter needs the self-calibration window to fill before it can arm, so the first stretch of a fresh chart stays dormant by design.
SETTINGS
▸ Trail — ATR length, base distance, adaptive distance and its strength. ▸ Regime Filter — on or off, efficiency lookback, self-calibration window, arming percentile, hysteresis, minimum bars per regime. ▸ Signals — buy and sell signals, labels or arrows, stop level on the label. ▸ Visuals — glow, fill, candle dimming, dashboard position.
ALERTS — buy, sell, any signal, regime opened and regime closed. All fire on closed bars.
NON-REPAINTING — the trail is built from closed-bar values and every signal fires on bar close. A printed signal never moves and never disappears.
WHY THESE PARTS ARE ONE SCRIPT
The trail alone is an ordinary trailing stop and will chop you up in a range. The regime filter alone has nothing to gate. The comparison exists only because a filter nobody can check is just a claim, and it needs both of the others to have something to measure. Take any one away and the other two stop making a point.
This indicator is an educational market-analysis tool, not financial advice. It does not predict price. The comparison figures describe how often each version of the trail changed direction on the loaded chart; they say nothing about profit or loss. Always confirm with your own analysis and manage your risk. Indikator

Realized Volatility Comparator [AlgoTraderPro]What it does
Plots the annualized realized volatility of the chart's symbol and of a second symbol of your choice in the same pane, so you can compare how "nervous" two assets actually are — and how that changes across years. The default comparison is gold, which makes it useful for one specific long-term study: watching Bitcoin's volatility mature toward that of older stores of value.
How it works
For each symbol the script computes the standard deviation of logarithmic returns over a configurable window, then annualizes it:
realized vol = stdev( ln(close / close ), window ) × √(periods per year) × 100
The annualization factor is derived from the chart timeframe automatically (a 365-day year), so the reading is comparable across daily and weekly charts. The comparison symbol's volatility is computed in its own symbol context via request.security, using its own bar series. An optional simple moving average smooths both lines, and a readout table shows the current value for each symbol plus the ratio between them.
Inputs
Realized volatility window — bars in the standard deviation (default 26; suggested 26 on weekly ≈ six months, 90 on daily ≈ one quarter). Shorter = more reactive, longer = smoother regime view.
Smoothing — SMA applied to both lines; 1 = off.
Comparison symbol — any symbol (default OANDA:XAUUSD). Indices, FX, equities all work.
Show readout table — toggles the current-values table.
Colors — line colors for each series.
How to read it
The absolute level tells you the market's current disagreement about the asset's value: a young or contested asset prints high realized volatility; a settled one prints low. The slope across years tells you whether that disagreement is widening or narrowing. The ratio in the table condenses the comparison into one number — how many times more volatile the chart symbol is than the reference.
Suggested study
Load on BNC:BLX (Bitcoin Liquid Index, history back to 2010) on a weekly chart with the default gold comparison. The full history shows Bitcoin's realized volatility declining cycle after cycle while gold's stays in a low band — a maturation pattern gold itself went through after 1971.
Other uses
Position sizing context (size inversely to the regime), comparing any two assets' risk regimes before pairing them in a portfolio, or checking whether a "quiet" market is genuinely quiet by historical standards. Indikator

Robust Regression Residual Bands [Pineify]Robust Regression Residual Bands
Overview
This overlay fits a rolling line while bounding influence from unusual closes. It shows a robust center, two MAD shells, confirmed extremes, and an optional dashboard. It is context, not a forecast.
Problem Definition
Least-squares channels and standard deviation magnify large errors. One gap, wick, or bad print can rotate the line and widen its bands, changing both the reference and the meaning of “far.” Short windows add noise; long ones preserve distortion. The invariant is that ordinary observations define the path, extremes stay visible, and their influence remains bounded.
Design Rationale
Regression stays because slope and residual distance answer different questions. Finite Huber-style refits replace unrestricted influence: residuals inside a threshold keep full weight; those outside receive progressively less. Hard deletion was rejected because values switch abruptly at a cutoff. Final scale uses median absolute deviation (MAD) times 1.4826. MAD resists isolated extremes but is less efficient for Gaussian errors. Two passes balance refreshed weights with bounded workload; users may select one to three.
Key Features
Rolling regression with bounded influence refits.
Two shells sized from final residual MAD.
Center color for normalized slope.
Confirmed outer-entry diamonds.
Optional bar color and dashboard for residual z, slope/MAD, scale, window, and passes.
How It Works
Each bar loads a chronological rolling window and fits an equal-weight line. It finds every residual, their median, and median absolute distance from that median. MAD times 1.4826 becomes robust scale; minimum tick prevents zero division.
Each distance is compared with clipping threshold times scale. Inside values keep weight 1. Outside values receive threshold divided by distance, smoothly capping influence. The line is refitted for the selected passes; residual median and MAD are then recomputed. Displayed center is the newest fit plus median residual.
Bands equal center plus or minus selected MAD multiples. Residual z divides current distance by scale; slope divided by scale controls color. A full window without missing data is required. Open-bar values can change; markers and alerts require confirmation.
How Multiple Indicators Work Together
These are causal stages, not unrelated indicators. Regression supplies direction but needs clipping to limit leverage. Clipping needs scale, and MAD prevents the same extreme from dominating it. Final residual measures price against the stabilized path; normalized slope separates direction from dispersion. Without refitting, bands inherit a tilted center; without scale, distance is not comparable. All visuals expose one model.
Trading Ideas and Insights
A confirmed outer entry means the close is unusual relative to current path and scale; it does not imply reversal. Alignment with strong slope can describe expansion, while repeated extremes with flattening slope can motivate a balance review. Alternating center crosses expose noise. Compare states with structure, liquidity, events, and risk controls. The script provides no entries, stops, sizing, or expected returns.
Unique Aspects
The contribution couples bounded influence refits with a median-centered MAD field. Common channels let an extreme affect slope and width through squared error. Here distance sets a smooth influence cap, the line is rebuilt, and final residuals size the tunnel. Median residual shifts the newest fit instead of assuming zero arithmetic mean. Center is primary, shells encode distance, and amber diamonds encode confirmed entries—not probability.
How to Use
Add it to a standard chart and wait for a full window.
Choose a window matching the horizon and review several regimes.
Read center color as normalized direction and bands as robust distance.
Use the dashboard to compare raw and scale-relative movement.
Alert on confirmed outer entry or center crossing, then apply independent context and risk rules.
Secondary layers can be disabled without changing the model.
Customization
Short windows adapt faster and vary more; long ones smooth more and retain old regimes. Extra refit passes can limit leverage further but cost computation and may underweight a true break. Lower clipping resists extremes sooner; higher clipping approaches ordinary regression. MAD multiples set tunnel thresholds, with a minimum shell gap enforced. Visual layers and palette are independent. Defaults are not universal optima.
Assumptions and Limitations
The model assumes a useful local line and comparable source data. Curves, breaks, gaps, rolls, illiquidity, adjusted history, and non-standard charts weaken it. Robust weights bound influence but cannot label an extreme as error or regime change. Results lag, parameters matter, and small MAD makes flat markets sensitive to the tick floor.
Open-bar values may change. Confirmed alerts still depend on feed and settings. Missing data restarts warm-up. The script has no volume, order flow, higher-timeframe request, future value, pivot, or simulation. It estimates neither reversal probability nor fair value, execution, risk, or profit. Outer distance is deviation, not proof of return.
Conclusion
Bounded refits stabilize rolling path, MAD stabilizes scale, and the tunnel exposes both. Treat distance and direction as lagging context, not a forecast; use independent confirmation.
Indikator

ATR PulseATR Pulse is an ATR-based trend and signal indicator designed to identify transitions around a dynamic volatility-adjusted trailing stop.
The script combines one core ATR transition engine with optional validation filters. These filters are not separate trading systems merged together; they act as configurable confirmation layers around the same underlying price-versus-trailing-stop event. This allows users to keep the indicator simple or make signal requirements more selective without changing the core concept.
**How it works**
The indicator calculates Average True Range over the selected ATR Period and multiplies it by the ATR Sensitivity setting.
This produces a dynamic loss distance:
ATR distance = ATR x Sensitivity
The trailing stop then adjusts according to the relationship between the current price, the previous price, and the previous trailing-stop value.
When price remains above the trailing stop, the stop follows upward without moving lower.
When price remains below the trailing stop, the stop follows downward without moving higher.
A directional transition is detected when price crosses the ATR trailing stop:
* A bullish signal requires price to cross above the trailing stop.
* A bearish signal requires price to cross below the trailing stop.
The indicator uses standard chart prices and does not request data from another symbol or timeframe.
**ATR Sensitivity**
ATR Sensitivity controls how closely the trailing stop follows price.
Lower values create a tighter stop that reacts to smaller price movements.
Higher values create a wider stop that requires a larger price movement before a directional transition occurs.
ATR Period controls the lookback used to calculate market volatility.
**Optional EMA trend filter**
When enabled:
* Bullish signals require price to be above the selected EMA.
* Bearish signals require price to be below the selected EMA.
The purpose of this filter is to restrict ATR transitions to the selected broader price direction.
**Optional ADX / DMI filter**
When enabled, the indicator requires both directional strength and directional agreement.
For bullish signals:
* ADX must be at or above the selected minimum.
* +DI must be greater than -DI.
For bearish signals:
* ADX must be at or above the selected minimum.
* -DI must be greater than +DI.
DI Length, ADX Smoothing, and Minimum ADX are independently adjustable.
**Optional RSI filter**
The RSI filter provides an additional directional condition.
When enabled:
* Bullish signals require RSI above the selected RSI Direction Level.
* Bearish signals require RSI below that level.
The default center level is 50, but both the RSI length and directional level can be changed.
**Optional volume filter**
When enabled, current volume must be at least the selected multiple of its moving average.
For example, a setting of 1.5 requires current volume to be at least 1.5 times the selected average-volume reference.
If usable volume data is not available for the symbol, the volume condition is bypassed rather than preventing all signals. Volume therefore should be interpreted according to the quality of volume data provided for the selected market.
**Optional candle-quality filter**
This filter evaluates the signal candle itself.
When enabled:
* A bullish signal requires a bullish candle.
* A bearish signal requires a bearish candle.
* The candle body must represent at least the selected percentage of the candle's full high-to-low range.
This can be used to exclude transition candles with relatively small bodies and large wicks.
**Signal cooldown**
The Minimum bars between signals setting can be used to reduce closely spaced signals.
A value of 0 disables the cooldown.
Higher values require the specified number of bars to pass before another signal can be accepted.
**Candle-close confirmation**
Confirm signals on candle close is enabled by default.
When enabled, Buy and Sell signals are accepted only after the current candle is confirmed closed.
When disabled, signal conditions can become true while the realtime candle is still developing. In that mode, a signal may appear or disappear before the candle closes as price changes.
**Visual controls**
The indicator can display:
* Buy and Sell labels.
* The ATR trailing stop.
* The trend EMA.
* A bullish or bearish background.
* An information dashboard.
Most supplementary visuals are optional so users can keep the chart clean and display only the elements relevant to their analysis.
The dashboard can show the current trend state together with ATR, ADX, RSI, sensitivity, and current filter readiness.
**Alerts**
Two alert conditions are included:
* ATR Pulse Buy
* ATR Pulse Sell
These alerts use the same final signal conditions as the chart labels, including any optional filters that the user has enabled.
Users should configure the indicator settings before creating an alert so the alert reflects the intended configuration.
**Pine Screener support**
ATR Pulse can also be used with TradingView's Pine Screener.
The script includes dedicated Buy and Sell alert conditions that can be used as screening filters, allowing users to scan a watchlist for symbols currently meeting the ATR Pulse bullish or bearish conditions.
This can be particularly useful when the same ATR Pulse settings need to be evaluated across multiple symbols instead of checking charts individually.
Pine Screener has its own platform limitations and calculation scope, so screening results should be interpreted within the data and timeframe processed by the Screener.
**Example workflow**
A user who wants the basic ATR transition behavior can leave all optional filters disabled.
A more selective configuration can enable one or more of the following:
* EMA trend alignment.
* ADX / DI directional strength.
* RSI direction.
* Volume expansion.
* Candle quality.
* Signal cooldown.
Each enabled filter becomes an additional requirement for the same underlying ATR transition signal.
There is no single recommended combination for every symbol or timeframe. Settings should be selected according to the market, timeframe, and type of analysis being performed.
**Repainting and realtime behavior**
ATR Pulse does not use future data or lookahead calculations.
With Confirm signals on candle close enabled, signal confirmation occurs only on closed candles.
The ATR trailing stop itself continues to update as new market data arrives.
If candle-close confirmation is disabled, conditions on the realtime candle can change before that candle closes. This is normal realtime behavior and should not be interpreted as a confirmed historical signal until the bar is complete.
Changing indicator settings, symbol, timeframe, or available chart history causes TradingView to recalculate the indicator.
**Limitations**
ATR Pulse is sensitive to volatility and parameter selection.
A tight ATR Sensitivity may produce more frequent transitions in sideways markets, while a wider setting can respond more slowly to directional changes.
Optional filters can reduce the number of signals, but they can also delay or exclude transitions that would otherwise qualify under the core ATR logic.
ADX, RSI, EMA, volume, and candle-quality conditions describe different aspects of current market behavior. Their inclusion does not guarantee that a subsequent price move will continue in the signal direction.
Signals are descriptive outputs of the selected rules, not forecasts of future price movement.
ATR Pulse is an indicator, not a strategy. It does not place orders, provide performance statistics, or claim a particular win rate. It is intended as a configurable technical-analysis and screening tool to help users identify and evaluate ATR-based directional transitions.
Indikator

QuantLine Auction State EngineQuantLine Auction State Engine asks one question: what is price doing with the
edge of its prior range?
Many breakout tools mark the first trade above a rolling high or below a rolling
low. That does not distinguish a wick from acceptance, and the rolling level can
move while the event is still being judged. This script separates the process
into explicit states and locks the point-in-time range when a test begins.
States
- BAL — price remains in balance inside the prior range.
- CMP — balance with low ATR percentile: potential energy, no direction.
- T↑ / T↓ — price is testing beyond a locked range edge; acceptance is not yet confirmed.
- A↑ / A↓ — the required closes remain outside the edge and the move passes the selected efficiency and relative-volume checks.
- FA↑ / FA↓ — price returns inside after an attempted auction beyond the edge.
- RT↑ / RT↓ — the first retest holds on the accepted side of the locked edge.
How it is calculated
1. The reference range is the highest high and lowest low of prior bars. The
current bar is excluded.
2. When a close moves beyond an edge by the selected ATR distance, both edges
are locked. They cannot slide while the test is active.
3. Acceptance requires a user-selected number of closes beyond the locked edge.
4. Kaufman-style efficiency ratio separates directional travel from a noisy
path. Optional relative volume checks whether participation is above its
recent average.
5. ATR percentile identifies compression. It does not predict the direction of
the next expansion.
6. A return inside the edge marks a failed auction. After acceptance, the first
touch that closes on the accepted side marks a held retest.
State transitions and alerts occur on confirmed bars. No future bars are used,
and the active range is locked at the time of the test.
How to use it
The tool is a market-structure classifier. It can help a trader distinguish
between “price traded beyond a level” and “price was accepted beyond a level.”
It does not provide an entry, stop, target, position size, probability, or
profitability claim.
All defaults are round research hypotheses and are user-adjustable. Market
quality, fees, slippage and higher-timeframe context remain outside this script.
Educational context only. Not financial advice. Indikator

TF: BB/KC and Potential Reversals (BBKC)TradingFlow: BB/KC and Potential Reversals (BBKC)
BBKC combines Bollinger Bands (BB) and a Keltner Channel (KC) in one clean overlay, then uses band re-entry and momentum conditions to highlight potential bullish and bearish reversals. Its purpose is to make volatility structure, trend behaviour, compression, expansion, and possible turning points easier to read without covering the chart with separate indicators.
The diamond markers are hints that price may be reacting after an extended move or that momentum may be fading. They are not automatic trade instructions, and they do not mean a reversal is confirmed.
A Unified BB / KC View
Bollinger Bands and Keltner Channels describe volatility in different ways:
• Bollinger Bands: use standard deviation, so their width changes as price movement expands or contracts.
• Keltner Channel: uses ATR around an EMA to create a smoother channel for reading trends and pullbacks.
BBKC plots both structures with one visual theme rather than stacking two unrelated indicators. The more visible aqua boundaries are the KC, while the lighter boundaries are the BB. Subtle shading makes it easier to see how the two envelopes contract and expand around price, and the full KC area can also be lightly shaded if preferred.
This merged presentation is useful even without the reversal markers. The slope and direction of the channels, the side of the channel where price is holding, and the way price reacts at the boundaries can all provide trend context.
Why the Default KC Multiplier Is 1.6
By default, the KC uses a 20-period EMA and an ATR multiplier of 1.6. Many modern Keltner Channel implementations use a 2.0 ATR setting. BBKC uses 1.6 to keep the boundaries somewhat closer to price, making routine pullbacks, boundary tests, and re-entry behaviour easier to see. This is a visual design choice, not a claim that 1.6 is inherently more accurate.
The multiplier is adjustable. Different instruments and trading styles may benefit from a wider or narrower channel, so 1.6 should be understood as a useful default rather than a universal optimum.
How to Read the Potential Reversal Markers
• Green diamond: a bullish potential reversal. Price has reacted from a lower volatility boundary and passed the enabled filters.
• Red diamond: a bearish potential reversal. Price has reacted from an upper volatility boundary and passed the enabled filters.
By default, the script looks for the close to cross back inside a lower or upper KC or BB boundary. An optional rejection rule also checks whether the current or preceding candle touched or pierced a Bollinger Band before the current candle closed back inside.
The optional filters are designed to reduce ordinary boundary crossings:
• Volatility context: one of the two preceding closes must have been outside the corresponding boundary of a separate ATR-based Volatility Channel.
• RSI momentum: RSI must be below the bullish threshold or above the bearish threshold. Both levels are adjustable.
• Stoch RSI extreme: within a recent validity window, at least one completed bar must have both smoothed K and D in the 90/10 extreme zone. The window is adjustable and defaults to the two bars before the potential reversal; the current re-entry bar is excluded.
Potential reversal conditions are confirmed at bar close. The separate Volatility Channel can remain hidden while its values are still used by the filter; display it when you want to inspect those boundaries on the chart.
What a Marker Can and Cannot Mean
A potential reversal may become a major trend reversal, but it may also be only a small pullback, a pause within the existing trend, or a failed signal followed by continuation. The script detects a filtered move back from a volatility boundary; it cannot know in advance which outcome will follow.
The marker is therefore more useful as a prompt to investigate the chart than as a standalone entry command. A marker appearing against a strong trend should generally require more evidence than one appearing at a well-established structural level after an exhausted move.
Practical Reading Process
1. Read the slope and position of the BB / KC structure to understand the current trend and volatility regime.
2. Note whether the BB is compressing inside the KC or expanding beyond it.
3. When a diamond appears, check whether it is located near meaningful market structure rather than evaluating the marker in isolation.
4. Look for confirmation through price action, trend structure, support and resistance, or a failed breakout.
5. Add independent context such as volume profile, high- and low-volume areas, and the reaction around important support or resistance levels.
6. Define invalidation and risk before considering an entry.
Alerts
Alerts can be created for bullish potential reversals, bearish potential reversals, or either direction. They use the same final confirmed conditions and remain available when chart markers are hidden. For live use, “Once Per Bar Close” is recommended.
Important
BBKC is a chart-reading and opportunity-screening tool. Its markers are filtered potential reversals, not probabilities, guaranteed turning points, or complete trading systems. Settings behave differently across instruments and timeframes. Always combine the output with broader trend analysis, market structure, volume context, support and resistance, and appropriate risk management.
---
TradingFlow: BB/KC and Potential Reversals (BBKC)
BBKC 把布林通道(Bollinger Bands,BB)與肯特納通道(Keltner Channel,KC)整合在同一張主圖,並根據價格重新進入通道及動能條件,標示潛在的多頭和空頭反轉。它讓波動、趨勢、收縮、擴張和可能的轉折位置更容易判讀,不用另外疊加兩個指標。
菱形標記只是一個提示:價格經過一段延伸後,可能開始回頭,或原有動能正在減弱。它不是自動交易指令,也不代表反轉已經確認。
整合的 BB / KC 顯示
BB 與 KC 以不同方式描述波動:
• 布林通道: 使用標準差,會隨價格波動的擴大和收窄而改變。
• 肯特納通道: 以 EMA 為中心,利用 ATR 建立較平滑的通道,適合觀察趨勢與回調。
BBKC 用統一的配色呈現兩者。較清晰的水藍色邊界是 KC,較淡的邊界是 BB。淡色填充可幫助觀察兩組通道如何隨價格收縮和擴張,也可選擇顯示整個 KC 範圍。
即使不看反轉標記,這組通道本身也能幫助判斷趨勢。可留意通道斜率、價格主要停留在哪一側,以及價格接近邊界時的反應。
為何 KC 預設倍數是 1.6
KC 預設使用 20 週期 EMA 和 1.6 倍 ATR。現代 KC 指標常見的 ATR 設定是 2.0;BBKC 改用 1.6,讓邊界稍微靠近價格,更容易看到一般回調、邊界測試及價格重新進入通道的情況。這是為了方便讀圖,並不代表 1.6 本身更準確。
倍數可以自行修改。不同市場、時間週期和交易方式可能適合不同寬度,因此 1.6 只是實用的起始設定,並非所有情況下的最佳值。
如何閱讀潛在反轉標記
• 綠色菱形: 多頭潛在反轉。價格從下方邊界回升,並通過已啟用的過濾條件。
• 紅色菱形: 空頭潛在反轉。價格從上方邊界回落,並通過已啟用的過濾條件。
預設會尋找收盤價重新進入 KC 或 BB 邊界的情況。也可加入額外條件:目前或前一根 K 線先觸及/突破 BB,然後目前 K 線收回通道內。
各項過濾器用於減少普通邊界穿越造成的雜訊:
• 波動背景: 前兩根 K 線中,至少一根的收盤價必須曾位於另一組 ATR 波動通道的相應邊界之外。
• RSI 動能: 多頭標記要求 RSI 偏低,空頭標記要求 RSI 偏高;門檻可自行調整。
• Stoch RSI 極端值: 在近期有效期內,至少一根已完成 K 線的平滑 K、D 必須同時進入 90/10 極端區域。有效期可以調整;預設檢查潛在反轉前的兩根 K 線,不包括目前重新進入通道的 K 線。
潛在反轉條件只會在 K 線收盤後確認。另一組 Volatility Channel 即使隱藏,其數值仍可用於過濾;如想直接查看這些邊界,可在設定中顯示它。
標記可能代表甚麼
潛在反轉可能最終發展成主要趨勢反轉,也可能只是一個小型回調、原有趨勢中的短暫停頓,甚至是錯誤提示,之後價格繼續沿原方向運行。這套判斷只能找出價格從波動邊界回頭的跡象,無法預先知道之後會出現哪一種結果。
標記的作用是提醒你多看一眼,而不是叫你立即進場。逆著強勁趨勢出現時,通常需要更多確認;若它出現在明確的支撐、阻力或區間邊緣,而且此前走勢已有明顯延伸,才更值得留意。
實用判讀流程
1. 先閱讀 BB / KC 的斜率及價格位置,判斷目前趨勢與波動狀態。
2. 觀察 BB 正在 KC 內部收縮,還是向 KC 外部擴張。
3. 菱形出現時,先看它是否接近支撐、阻力或區間邊緣,不要只看標記本身。
4. 利用價格行為、趨勢結構、支撐阻力或假突破尋找確認。
5. 配合成交量分布(Volume Profile)、高/低成交量區,以及重要支撐阻力附近的反應。
6. 考慮進場前,先定義失效位置及風險。
警報
如需追蹤,可分別在多頭潛在反轉、空頭潛在反轉,或兩者任一出現時建立警報。警報只會在收盤條件確認後觸發;隱藏圖表上的菱形標記不會影響警報。即時使用時,建議選擇「Once Per Bar Close」。
重要說明
BBKC 是圖表判讀及機會篩選工具。標記只表示經過條件過濾的潛在反轉,不代表任何勝率,也不是必然轉折或完整交易系統。不同市場和時間週期的表現可能不同。使用時仍要結合趨勢、市場結構、成交量、支撐阻力和風險管理。
---
TradingFlow: BB/KC and Potential Reversals (BBKC)
BBKCは、ボリンジャーバンド(BB)とケルトナーチャネル(KC)を1つの見やすいオーバーレイに統合し、バンドへの再進入とモメンタム条件から、強気・弱気の潜在的な反転を表示します。複数の指標を重ねてチャートを複雑にすることなく、ボラティリティ構造、トレンド、収縮、拡大、転換候補を読みやすくすることが目的です。
ひし形のマーカーは、伸びた値動きが反応し始めた、またはモメンタムが弱まりつつある可能性を知らせるヒントです。自動売買の指示ではなく、反転が確定したことも意味しません。
BBとKCを統合した表示
BBとKCは異なる方法でボラティリティを表します。
• ボリンジャーバンド: 標準偏差を使うため、価格のばらつきの変化に反応します。
• ケルトナーチャネル: EMAを中心にATRで幅を作る、より滑らかなチャネルです。トレンドや押し戻りの確認に使えます。
BBKCは両者を共通の配色で整理して表示します。より明瞭なアクア色の境界がKC、薄い境界がBBです。控えめな色付けにより、2つのチャネルが価格の周囲で収縮・拡大する様子を見やすくし、必要に応じてKC全体の範囲も薄く表示できます。
この統合表示は、反転マーカーを使わない場合にも有用です。チャネルの傾き、価格が維持されている側、境界での反応から、トレンドの背景を読み取れます。
KCのデフォルト倍率が1.6である理由
KCは、デフォルトで20期間EMAと1.6倍のATRを使用します。現代的なKCでは2.0倍のATRもよく使われますが、BBKCは境界を価格に少し近づけ、通常の押し戻り、境界テスト、チャネルへの再進入を見やすくするために1.6倍を採用しています。これは見やすさのための設計であり、1.6倍のほうが本質的に正確という意味ではありません。
倍率は調整可能です。銘柄、時間軸、取引スタイルによって適切な幅は異なるため、1.6は実用的な初期値であり、すべての市場に共通する最適値ではありません。
潜在リバーサル・マーカーの見方
• 緑のひし形: 強気の潜在リバーサル。価格が下側のボラティリティ境界から反応し、有効なフィルターを通過した状態です。
• 赤のひし形: 弱気の潜在リバーサル。価格が上側のボラティリティ境界から反応し、有効なフィルターを通過した状態です。
デフォルトでは、終値がKCまたはBBの境界内へ戻る動きを検出します。追加条件では、現在または直前の足がBBに到達・突破し、その後に現在の終値がバンド内へ戻った場合も候補にできます。
各フィルターは、通常の境界通過によるノイズを抑えるために使用します。
• ボラティリティ背景: 直前2本のうち少なくとも1本の終値が、別のATRベースのVolatility Channelの対応する境界より外側であることを要求します。
• RSIモメンタム: 強気ではRSIが下側しきい値未満、弱気では上側しきい値を超えていることを要求します。どちらもしきい値を調整できます。
• Stoch RSIの極端値: 直近の有効期間内で、少なくとも1本の確定足において平滑化されたKとDが同時に90/10の極端ゾーンへ入っていることを要求します。有効期間は調整でき、デフォルトでは潜在リバーサル前の2本を確認します。現在の再進入足は含めません。
潜在リバーサルの条件は足の確定時にのみ成立します。Volatility Channelは非表示でもフィルターに使われ、必要に応じてチャート上に境界を表示できます。
マーカーが意味する可能性
潜在的な反転は、大きなトレンド転換につながる場合もあれば、小さな押し戻り、既存トレンド内の一時停止、または誤ったシグナルとなってそのままトレンドが継続する場合もあります。検出しているのは、フィルターを通過したボラティリティ境界からの戻りです。その後の結果を事前に判断することはできません。
そのため、マーカーは単独のエントリー指示ではなく、チャートを詳しく確認するためのヒントとして使うのが適切です。強いトレンドに逆らうマーカーには、明確な構造水準で伸び切った後に出るマーカーよりも多くの確認が必要です。
実践的な読み方
1. BB / KCの傾きと価格位置から、現在のトレンドとボラティリティ状態を確認します。
2. BBがKCの内側で収縮しているか、外側へ拡大しているかを確認します。
3. ひし形が出たら、重要な市場構造の近くにあるかを確認し、マーカーだけで判断しないようにします。
4. プライスアクション、トレンド構造、サポートとレジスタンス、または失敗したブレイクから確認を探します。
5. ボリュームプロファイル、高・低出来高帯、重要なサポート/レジスタンスでの反応など、独立した情報を組み合わせます。
6. エントリーを検討する前に、無効化水準とリスクを定義します。
アラート
強気、弱気、またはいずれかの方向に潜在リバーサルが現れた場合のアラートを作成できます。どれも同じ足の確定条件で作動し、チャート上のマーカーを非表示にしても機能します。リアルタイムでは「Once Per Bar Close」の使用を推奨します。
重要
BBKCはチャート分析と候補抽出のためのツールです。マーカーはフィルターを通過した潜在的な反転を示すものであり、確率、保証された転換点、または完全な売買システムではありません。銘柄や時間軸によって挙動は異なります。より広いトレンド分析、市場構造、出来高、サポートとレジスタンス、適切なリスク管理と組み合わせて使用してください。
Indikator

VWAP Regime AI [AxeAlgo]OVERVIEW
VWAP Regime AI is an anchored VWAP (Volume-Weighted Average Price) with
standard-deviation bands, enhanced by a native, from-scratch k-means
clustering engine that classifies recent market volatility into three
regimes — Low, Medium, and High — and adapts the indicator's behavior
based on which regime is currently active.
At its foundation this is the same tool institutional desks use every
day: a running volume-weighted average price with bands around it, used
to judge where "fair value" sits and how far price has stretched away
from it. What this script adds on top is a genuine unsupervised machine
learning step that reads the market's own volatility and lets that
reading drive three things: how wide the bands are, which signal logic
is active, and how much the indicator should trust its own regime call
before acting on it.
This script is free and open-source. All calculations happen natively in
Pine Script on your own chart data.
============================================================
FULL TRANSPARENCY ABOUT THE "AI" IN THIS SCRIPT
============================================================
Pine Script cannot call an LLM, a remote model, or any external AI
service — TradingView does not allow outbound network requests from
indicators, and this script makes none. There is no hidden API call,
no "black box," and nothing running outside of what you can read in the
source code.
What "AI" means here specifically: this script implements k-means
clustering — a well-established unsupervised machine learning algorithm
— entirely in native Pine Script math and arrays. It groups a rolling
window of recent ATR (volatility) readings into three clusters by
repeatedly assigning each reading to its nearest cluster center and then
recomputing each center as the mean of everything assigned to it. This
publication states plainly what is and is not happening so nobody
mistakes this for predictive AI, sentiment analysis, or anything that
consults external data or forecasts the future. It classifies what has
already happened; it does not predict what will happen next.
============================================================
HOW IT WORKS
============================================================
VWAP & Standard Deviation Bands
--------------------------------
The core VWAP resets at the start of each new anchor period (Session,
Week, Month, Quarter, or Year — configurable) and accumulates a running
volume-weighted average from there. Standard deviation is calculated
using the same volume-weighted variance formula TradingView's own
built-in VWAP-with-bands tool. Up to three bands can be shown,
each set at a configurable standard-deviation distance from VWAP.
AI Volatility Clustering (K-Means)
------------------------------------
A rolling window of recent ATR readings (length and window size are both
configurable) is periodically re-clustered into three groups — Low,
Medium, High — using k-means. Reclustering happens every N bars rather
than every single bar, purely for performance; the live classification
of the current bar still updates continuously between reclusters.
Alongside the classification, the script computes a Confidence score
(0-100%): how much closer the current reading sits to its nearest
cluster than to its second-nearest one. A reading sitting right on a
cluster's center scores near 100%; a reading sitting on the boundary
between two regimes — an effectively ambiguous call — scores near 0%.
A "Minimum Regime Confidence" input lets you require a minimum score
before the regime is allowed to influence anything else in the script,
so an unconfident, boundary-line classification doesn't silently drive
behavior.
Adaptive Band Width
----------------------
When enabled, the standard-deviation band multipliers are scaled by a
per-regime factor: tighter in Low volatility, wider in High volatility,
instead of one fixed multiplier that's too tight in some conditions and
too loose in others. This only engages once the AI is both ready
(its lookback window has filled and it has run at least once) and
confident, per the Minimum Regime Confidence setting above.
Signal Logic — Mean Reversion, Breakout, or Auto
----------------------------------------------------
Two independent signal styles are built in, both measured off Band 2:
Mean Reversion looks for price crossing back inside the band from
outside (betting an extreme move snaps back toward VWAP); Breakout looks
for price crossing outside the band (betting the move has momentum to
keep running). "Auto" mode lets the detected volatility regime decide
which logic applies bar by bar — Low/Medium volatility defaults to Mean
Reversion, High volatility defaults to Breakout — falling back to Mean
Reversion whenever the AI isn't ready or confident enough to trust.
Three independent, stackable filters reduce noise on top of the raw
band cross:
- Bar-Close Confirmation: a cross only counts once the bar has fully
closed, filtering out intrabar wicks that reverse before the close.
- Signal Cooldown: blocks a new signal, in either direction, for a
configurable number of bars after the last one — aimed directly at
whipsaw (price crossing back and forth across a band repeatedly).
- Band Cross Buffer (hysteresis): requires price to clear a band by a
small extra distance, in standard deviations, rather than an exact
touch, so noise sitting right on the line doesn't keep re-triggering
crosses back and forth.
AI Volume Confirmation Filter
---------------------------------
The same k-means engine used for volatility is optionally reused on raw
volume, classifying each bar's volume as Low, Normal, or High. When
enabled, signals are only allowed on Normal-or-above volume, filtering
out low-conviction moves.
Secondary VWAP
-----------------
An optional second VWAP anchored to a different (typically higher)
period can be plotted alongside the primary one — for example a Weekly
VWAP behind a Session VWAP — for confluence, since multiple VWAP anchors
are commonly watched together rather than trusting a single one in
isolation. It is a reference line only; no bands are drawn for it.
Signal Track Record
-----------------------
An on-chart scorecard tracks, in a simple and fully model-free way, how
the signals have actually performed: each signal opens a virtual
position at that bar's close, and the next opposite-direction signal
closes it out, scored as a win or a loss purely on which way price
moved in between. No target or stop-loss assumption is built into this
score — see the Limitations section below for exactly what this number
does and does not tell you.
Status Table
---------------
An optional on-chart table shows the current regime and its confidence,
the active band scale, the current VWAP value, a "Stretch Score" (see
below), and the Signal Track Record numbers, all in one place.
Stretch Score
----------------
A signed z-score of how many standard deviations price currently sits
from VWAP. Because it's measured in the same standard deviations the
bands are drawn in, it stays consistent with whatever the adaptive band
width currently has in effect — a reading of +2.00 always means "sitting
on Band 2," whether that band is currently tight or wide.
============================================================
HOW TO USE THIS INDICATOR
============================================================
1. Start with the default settings and watch the status table for a
while before changing anything. Let the AI Volatility Clustering
lookback window fill (the table will show "Calibrating..." until it
has enough data) so the regime classification is meaningful.
2. Decide whether you want Mean Reversion, Breakout, or Auto signal
logic. Auto is a reasonable starting point since it adapts to
detected conditions automatically.
3. Watch the Confidence score alongside the regime label. If confidence
is frequently low on your instrument/timeframe, consider raising the
Minimum Regime Confidence input so the indicator falls back to
neutral behavior more readily instead of acting on ambiguous calls.
4. Use the Stretch Score to judge how extended price currently is
relative to VWAP in a way that stays consistent even as band width
adapts.
5. Treat the Signal Track Record as a rough, ongoing sanity check on
signal quality — not a backtest and not a promise (see Limitations).
6. This is a visual/analytical tool, not an auto-trading system. It
does not place trades. Any alerts it can generate are notifications
only.
============================================================
INPUT GROUPS (SUMMARY)
============================================================
VWAP Settings
- Anchor Period (Session / Week / Month / Quarter / Year)
- Source price used for the VWAP calculation
Secondary VWAP (Confluence)
- Show/hide toggle, its own anchor period, and its own color
Standard Deviation Bands
- Independent show/hide and distance (in standard deviations) for
three bands, plus a toggle for the gradient fill shading around them
AI Volatility Clustering (K-Means)
- Enable/disable the clustering engine
- ATR length used as the raw volatility reading that gets clustered
- Clustering lookback window (bars) and reclustering frequency
- Number of k-means refinement iterations per reclustering
- Adaptive band width toggle and the three per-regime scale factors
- Minimum Regime Confidence threshold
Signals
- Show/hide signal markers
- Signal Mode (Mean Reversion / Breakout / Auto)
- Volume confirmation filter toggle
- Bar-close confirmation toggle
- Signal cooldown (bars)
- Band cross buffer (hysteresis, in standard deviations)
Visuals
- Regime background highlight toggle
- Status table toggle and Signal Track Record toggle
- Colors for VWAP, each band, each regime, and each signal direction
============================================================
REPAINTING & REAL-TIME BEHAVIOR
============================================================
This script does not use any higher-timeframe security() calls and does
not look ahead — every value at every historical bar is a function of
data available up to and including that bar. Once a historical bar is
confirmed, its VWAP, bands, regime classification, and signals do not
change on subsequent chart loads or reloads.
Like any real-time indicator, values on the currently forming (unclosed)
bar update as new price/volume ticks arrive, and will settle once that
bar closes — this is standard behavior for any live indicator, not
repainting of historical data. If you want signal markers to appear only
after a bar has fully closed rather than updating intrabar, keep the
"Require Bar Close Confirmation" input enabled (it is on by default).
============================================================
LIMITATIONS — PLEASE READ
============================================================
- The Signal Track Record is a simplified, model-free heuristic, not a
backtest. It ignores commissions, spread, slippage, position sizing,
and any stop-loss/take-profit logic, and it scores a "trade" purely by
whether price was above or below the entry price when the next
opposite signal fired. It exists to give a rough, ongoing sense of
signal direction quality — it is not a performance guarantee and
should not be relied on as one.
- K-means clustering, like any clustering method, can produce a
misleadingly high confidence score if recent volatility (or volume)
readings happen to be nearly constant for an extended window — a rare
condition, more likely on thinly-traded instruments, but worth being
aware of.
- Regime classification and adaptive behavior depend on the Clustering
Lookback window filling with data first; expect "Calibrating..." on a
freshly loaded chart or a short history until then.
- This is a discretionary analysis tool intended to support your own
judgment, not a mechanical, guaranteed-signal system. No combination
of settings eliminates false signals entirely, which is why several
independent, adjustable filters (bar-close confirmation, cooldown,
hysteresis buffer, volume confirmation, regime confidence threshold)
are provided rather than relied on individually.
============================================================
RISK DISCLAIMER
============================================================
This script is provided for educational and informational purposes
only. It is not financial advice, and it is not a recommendation to buy
or sell any security or instrument. Trading and investing involve
substantial risk of loss and are not suitable for every investor. Past
performance — whether real, simulated, or shown via the on-chart Signal
Track Record — is not indicative of future results. Always do your own
research and consider consulting a licensed financial advisor before
making trading decisions. Use this indicator, and any alerts it
generates, entirely at your own risk. Indikator

Expected Move BandsEvery options desk opens the week with the same question: how far is this thing supposed to travel by Friday? The answer is already priced. Implied vol is the market's own estimate of the coming move, and you can read it straight off the chart instead of running the math in your head.
This draws that estimate as bands around price. It anchors to the open of each week, or month, and holds the bands flat across the period, the way a desk marks its expected range on Monday morning and watches price work inside it.
The inner band is one standard deviation. If the market's vol read is right, price closes inside it about two times out of three. The wider band is two sigma, the tail. When price breaks the one-sigma band and holds out there, that is range expansion, the move getting repriced while it happens.
The bands are fed by whichever volatility index belongs to the instrument you are charting -- GVZ if it is gold, OVX for crude, VXN on the Nasdaq, DVOL on bitcoin, VIX on the S&P. The dashboard names the one it picked. That is the only case where implied vol is actually observed.
Where no such index exists, the bands are derived instead: a reference index scaled by the ratio of this instrument's realized vol to the reference's. The level and the event risk still come from a real options series and only the ratio is estimated, and the dashboard marks it DERIVED. It cannot see risk specific to one instrument, such as a single name going into its own earnings.
Where neither is possible nothing is drawn and the dashboard says why. There is no realized-vol fallback, deliberately: a backward-looking estimate diverges from traded implied vol exactly in the regimes you would open this for. Into a known event, implied rises while realized is still asleep. After a shock, realized stays elevated while implied mean-reverts. A band I cannot stand behind does not get drawn.
The dashboard shows the IV source and which tier it came from, the live IV, the expected move in points and percent, and the exact levels. Labels print the prices on the chart. Alerts fire when price closes outside one sigma or tags two.
Read the band correctly: an expected move is a probability statement, not a boundary. Price closing outside the one-sigma band roughly a third of the time is the model working, not failing. The realized-vol ratio behind derived mode is measured on daily bars, so it does not shift when you change chart timeframe. Indikator