
AMAZON
9 - 13 May
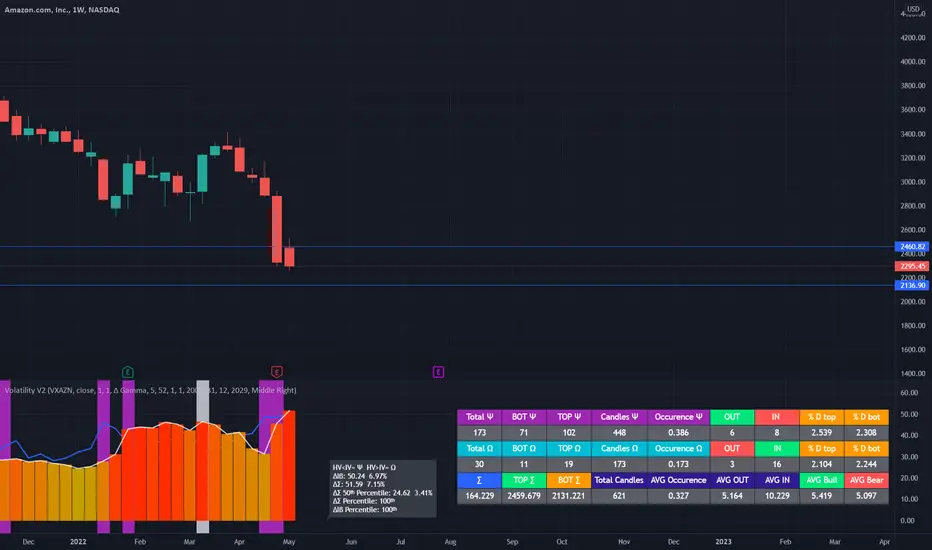
The weekly VXAZN-> Volatility Index for AMAZON
Implied = 50.24
In this we have to standard it for weekly session
39.02 / sqrt(52-> 52 weeks in a year) = 6.97%
My historical product is telling me with 1x coficient that the expected movement for this week
E Volatility = 51.59 / sqrt(52) = 7.15%
With this data, from my calculations, when EV > VIX, there were a 83% chance that the market
stay within the bottom and top created with the ranged from the E Vol
So for next week this range for us is going to be
TOP - 2460
BOT - 2131
9 - 13 May
The weekly VXAZN-> Volatility Index for AMAZON
Implied = 50.24
In this we have to standard it for weekly session
39.02 / sqrt(52-> 52 weeks in a year) = 6.97%
My historical product is telling me with 1x coficient that the expected movement for this week
E Volatility = 51.59 / sqrt(52) = 7.15%
With this data, from my calculations, when EV > VIX, there were a 83% chance that the market
stay within the bottom and top created with the ranged from the E Vol
So for next week this range for us is going to be
TOP - 2460
BOT - 2131

כתב ויתור
המידע והפרסומים אינם מיועדים להיות, ואינם מהווים, ייעוץ או המלצה פיננסית, השקעתית, מסחרית או מכל סוג אחר המסופקת או מאושרת על ידי TradingView. קרא עוד ב־תנאי השימוש.
כתב ויתור
המידע והפרסומים אינם מיועדים להיות, ואינם מהווים, ייעוץ או המלצה פיננסית, השקעתית, מסחרית או מכל סוג אחר המסופקת או מאושרת על ידי TradingView. קרא עוד ב־תנאי השימוש.