
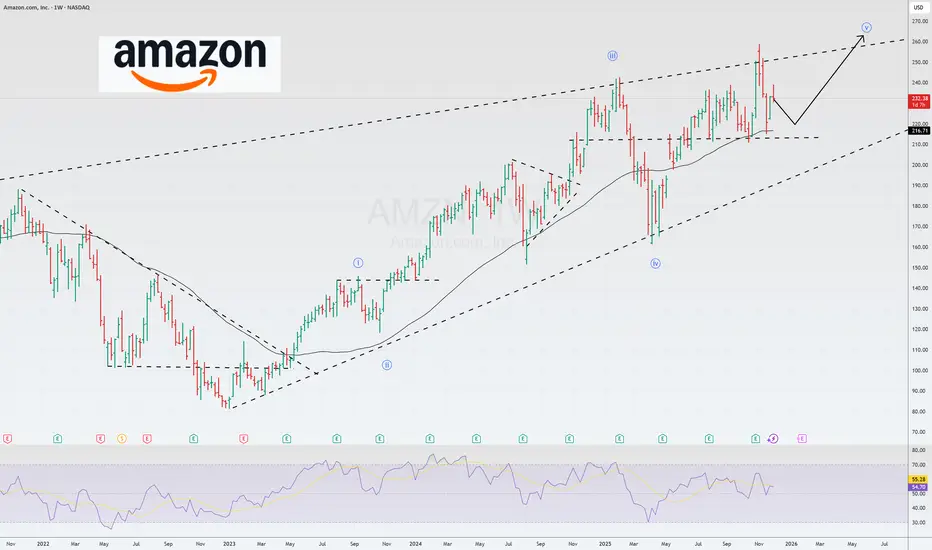
🌎 Amazon After Q3: Strength, Strategy, and Attractiveness
A Crash Against a Background of Strength: Amazon shares experienced a short-lived correction along with the broader market, but this move was driven more by general sentiment than by changes in the company's fundamentals.
Quarterly Results as a Turning Point: The third-quarter report was a powerful catalyst, forcing the market to reassess Amazon's trajectory. The company not only beat expectations on both key metrics, but also did so convincingly: earnings per share were 25% above analyst estimates. Following the results, shares soared more than 13%, reflecting investor optimism about growing profitability.
Growth Engines: Retail Gains Momentum, AWS Accelerates
• AWS Returns to Dynamic Growth: The core cloud division has seen growth accelerate to 20% year-over-year, impressive for a business with annual revenue of ~$130 billion. This signals renewed momentum and strengthens Amazon's position in the race for AI leadership.
• Retail Demonstrates Operational Efficiency: Contrary to previous narratives, retail segments (North America and International) are beginning to make a significant contribution to overall return on investment (ROIC). Their operating margins are growing, creating long-awaited operating leverage. This is the result of years of investment in automation and logistics, which are now reducing unit costs and expanding gross margins.
Strategic Advantages in the Age of Autonomy: Amazon Structurally Benefits from Macro Trends
1. Automation as a Flywheel: The implementation of autonomous systems compresses costs, allowing the company to simultaneously increase margins and reduce prices for the end consumer. This creates a self-sustaining cycle: volume growth, increased operating leverage, EPS growth, and additional investments in efficiency.
2. Vertical Integration: Control over the supply chain from logistics centers to AWS cloud infrastructure creates a unique, difficult-to-replicate barrier to entry for competitors and ensures long-term cash flow stability.
Value Issue: Not Cheap, but Reasonable
Despite the jump in its stock price, Amazon doesn't appear overvalued compared to its peers.
• With a forward P/E of around 38x, the company trades at a significant discount to its five-year average.
• Compared to other Magnificent 7 companies, Amazon represents a reasonable value, especially compared to more expensive NVDA or TSLA.
• High capital expenditures ($116 billion over 12 months) directed at AI infrastructure are temporarily putting pressure on free cash flow. This is an investment in future growth, but investors should consider this factor.
Summarizing the quarter's data and strategic vectors, the positive scenario for Amazon outweighs the risks (regulatory pressure, cyclical spending, cloud competition).
Amazon combines maturity and operational efficiency with acceleration potential thanks to AWS and automation.
We consider Amazon one of the best companies among the M7 and that it will soon show one of the best results in the Magnificent 7.
In our view, the corrective movement of the 4th wave is ending, and the stock will soon be setting new all-time highs.

כתב ויתור
המידע והפרסומים אינם מיועדים להיות, ואינם מהווים, ייעוץ או המלצה פיננסית, השקעתית, מסחרית או מכל סוג אחר המסופקת או מאושרת על ידי TradingView. קרא עוד ב־תנאי השימוש.
כתב ויתור
המידע והפרסומים אינם מיועדים להיות, ואינם מהווים, ייעוץ או המלצה פיננסית, השקעתית, מסחרית או מכל סוג אחר המסופקת או מאושרת על ידי TradingView. קרא עוד ב־תנאי השימוש.