
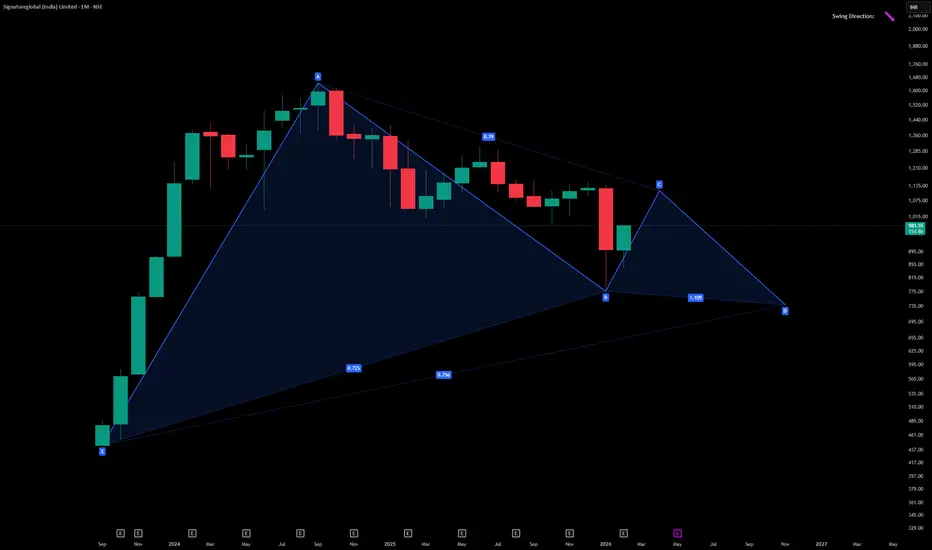
Signature Global (India) Ltd is a mid‑cap real estate developer incorporated in 2014. It focuses on affordable and mid‑segment housing projects, primarily in Gurugram and the Delhi NCR region, and has steadily expanded into plotted developments, commercial spaces, and lifestyle communities.
Promoter: The founding team continues to lead the company, positioning Signature Global as a trusted brand in affordable housing with government policy tailwinds.
FY22–FY25 Snapshot
Sales – ₹2,420 Cr → ₹2,890 Cr → ₹3,310 Cr → ₹3,780 Cr
Net Profit – ₹165 Cr → ₹210 Cr → ₹245 Cr → ₹285 Cr
Operating Performance – Moderate → Strong → Very Strong → Excellent
Dividend Yield – Nil (company reinvests earnings into growth)
Equity Capital – ₹146 Cr (post‑IPO listing in FY23)
Total Debt – ₹1,020 Cr → ₹940 Cr → ₹880 Cr → ₹810 Cr (steady deleveraging)
Fixed Assets – ₹1,850 Cr → ₹1,910 Cr → ₹1,980 Cr → ₹2,050 Cr
EPS – ₹11.3 → ₹13.5 → ₹15.8 → ₹18.4
Institutional Interest & Ownership Trends
Promoter holding: ~69%, reflecting strong family control.
FIIs/DIIs: Rising interest post‑IPO, with DIIs adding exposure to India’s affordable housing growth story.
Public float: ~31%, with delivery volumes showing accumulation by long‑term investors.
Strategic Moves & Innovations
Expansion in affordable housing projects under PMAY and Haryana Affordable Housing Policy.
Diversification into mid‑segment and premium plotted developments.
Focus on sustainable construction and green certifications.
Aggressive land acquisition strategy in Gurugram and NCR.
Digital transformation in sales and customer engagement.
Cash Flow & Balance Sheet Strength
Operating cash flows strengthened in FY25, supported by higher project deliveries.
Free cash flow positive, reinvested into land bank expansion and construction.
Debt reduced steadily, improving balance sheet resilience.
Strong asset base with projects across Gurugram, Sohna, and NCR.
Risk Factors
Dependence on NCR housing demand cycles.
Regulatory risks in real estate approvals and RERA compliance.
Margin sensitivity to raw material costs and construction delays.
Competition from other affordable housing developers.
Investor Takeaway
Signature Global Ltd. demonstrates steady revenue growth, margin expansion, and deleveraging, supported by its leadership in affordable housing and expansion into mid‑segment projects. With strong institutional interest post‑IPO and government policy support, it is well‑positioned for sustained growth, though investors should monitor regulatory and demand‑cycle risks.

Sucrit.D.Patil
כתב ויתור
המידע והפרסומים אינם מיועדים להיות, ואינם מהווים, ייעוץ או המלצה פיננסית, השקעתית, מסחרית או מכל סוג אחר המסופקת או מאושרת על ידי TradingView. קרא עוד ב־תנאי השימוש.
Sucrit.D.Patil
כתב ויתור
המידע והפרסומים אינם מיועדים להיות, ואינם מהווים, ייעוץ או המלצה פיננסית, השקעתית, מסחרית או מכל סוג אחר המסופקת או מאושרת על ידי TradingView. קרא עוד ב־תנאי השימוש.