מעודכן
Joint-state Kalman Filter (Linear / Extended / Unscented)
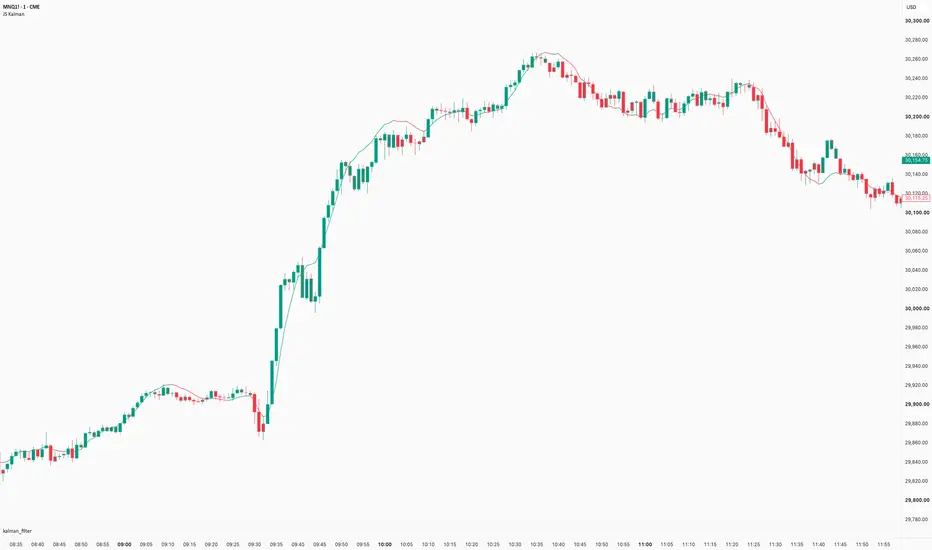
Joint-state Kalman Filter (Linear / Extended / Unscented) · JS Kalman
A joint-state price filter — not a typical 1D random-walk smoother. It estimates coupled [level, velocity] (and optionally acceleration) in one shared covariance, so trend tracking and reversal behaviour move together.
Filter types
State models
Switching filter type reuses the same internal state (you may see a one-bar discontinuity).
On the chart
Settings at a glance
Licence
Indicator and library © igor_sinkovec — Mozilla Public License 2.0.
A joint-state price filter — not a typical 1D random-walk smoother. It estimates coupled [level, velocity] (and optionally acceleration) in one shared covariance, so trend tracking and reversal behaviour move together.
Filter types
- Linear — kinematic Kalman; less lag on trends, can overshoot at sharp reversals (more with C.Accel).
- Extended — same layout with velocity damping v' = v × (1 − damping × |v|); analytic Jacobian.
- Unscented — same nonlinearity via sigma points (falls back to Extended if the covariance square root fails).
State models
- C.Veloc — constant velocity: [level, velocity]
- C.Accel — constant acceleration: [level, velocity, acceleration] (default)
Switching filter type reuses the same internal state (you may see a one-bar discontinuity).
On the chart
- Filtered price — teal while rising, red while falling (optional).
- Candle paint — same trend colours on the bars (optional).
Settings at a glance
- Model — filter type, state model, source, velocity damping (Extended / Unscented).
- Noise — process noise per component and measurement noise.
- Unscented — alpha, beta, kappa (Unscented only).
- UI — show filtered line, paint candles.
Licence
Indicator and library © igor_sinkovec — Mozilla Public License 2.0.
הערות שחרור
UI improvementsAbility to choose plot and candle colors.

כתב ויתור
המידע והפרסומים אינם מיועדים להיות, ואינם מהווים, ייעוץ או המלצה פיננסית, השקעתית, מסחרית או מכל סוג אחר המסופקת או מאושרת על ידי TradingView. קרא עוד ב־תנאי השימוש.
כתב ויתור
המידע והפרסומים אינם מיועדים להיות, ואינם מהווים, ייעוץ או המלצה פיננסית, השקעתית, מסחרית או מכל סוג אחר המסופקת או מאושרת על ידי TradingView. קרא עוד ב־תנאי השימוש.