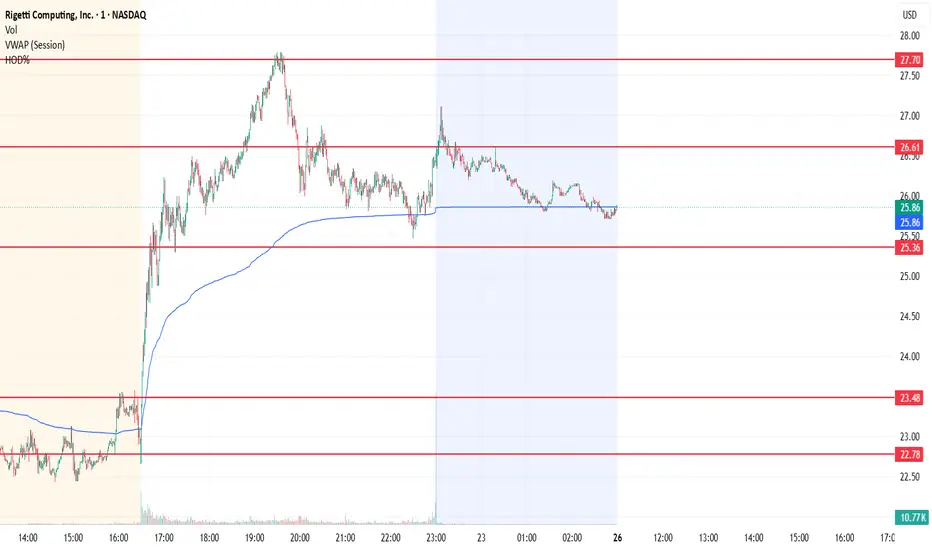
VWAP + Volume Clusters [Pro]Институциональный VWAP и сессионный профиль объёма в одном инструменте — для intraday-трейдинга по логике «цена движется от ликвидности к ликвидности».
Индикатор объединяет два ключевых ориентира внутридневной торговли: VWAP как institutional reference (средняя цена, по которой реально торговали крупные участники) и распределение объёма по уровням как зоны
интереса. Минималистичный визуал, всё настраивается.
Что внутри
1. Session VWAP + полосы σ
VWAP с привязкой к сессии (сброс в начале дня) и полосами стандартных отклонений 1σ / 2σ / 3σ. Полосы включаются по отдельности, множители настраиваются. VWAP — это «справедливая цена» дня: цена выше VWAP =
контроль покупателей, ниже = продавцов. Полосы 2σ/3σ — зоны статистического перерастяжения (потенциальный возврат к среднему).
2. Anchored VWAP
Второй VWAP с ручным якорем (по умолчанию — начало месяца). Удобно мерить среднюю цену от важного события: открытие недели/месяца, экстремум, новостной импульс.
3. Session Volume Profile (кластеры объёма)
Профиль объёма за текущую сессию, до 100 бинов:
- POC — уровень максимального объёма, точка контроля (магнит цены).
- VAH / VAL — границы зоны 70% объёма (Value Area).
- HVN — узлы высокого объёма (зоны принятия цены → поддержка/сопротивление).
- LVN — узлы низкого объёма, «пустоты» в распределении (цена проходит их быстро → зоны отбраковки).
- Гистограмма объёма справа от свечей.
4. Killzones (опционально)
Фоновая подсветка торговых сессий Frankfurt / London / NY (часовой пояс настраивается). По умолчанию выключено.
Алерты
VWAP touch · 2σ extreme · 3σ extreme (reversion zone) · POC test · VWAP reclaim (bull/bear). Каждый — отдельным переключателем, по умолчанию выключены.
На каких инструментах работает лучше
- Фьючерсы (NQ, ES, GER40/DAX и др.) и индексы CME — реальный биржевой объём, поэтому профиль и его уровни максимально надёжны. Основной кейс.
- Forex — VWAP полностью валиден, но профиль строится на tick volume (число тиков, не контракты), поэтому уровни объёма — ориентир, а не истина.
Как использовать
1. Цена у VWAP — точка равновесия, у 2σ/3σ — зона перерастяжения.
2. POC и HVN — уровни притяжения и реакции; LVN — зоны быстрого прохода.
3. Reclaim VWAP — смена внутридневного контроля.
▎ Volume Profile рассчитывается для текущей сессии (исторические профили не отображаются — сделано ради производительности). Индикатор информационный, не является торговым сигналом. אינדיקטור

אינדיקטור

אינדיקטור

RSI Oversold AO - Long StrategyRSI Oversold AO — Long Strategy
🔷 What it does:
This is a long-only DCA strategy that buys oversold dips and continues averaging into them only while the asset stays in the oversold zone. A long entry opens on a lower-timeframe RSI crossing down through 30. Four safety orders then average the position on an aggressive 2× deviation × 2× size ladder — but each one fires only if the lower-timeframe RSI is still below 25 at that moment. No falling-knife averaging into recovering momentum. Exit is a fixed 3% Take Profit from average entry. No trailing, no Stop Loss.
- Single base order with up to four safety orders on a 2× × 2× ladder.
- Dual RSI gating: cross-down entry trigger AND static oversold continuation filter.
- Aggressive size compounding: 60 / 120 / 240 / 480 USDT margins on the four safety orders.
- Fixed Take Profit: 3% above average entry, no trailing.
- Every entry, safety order, and exit emits a webhook-ready JSON alert payload for direct DCA Bot consumption.
🔷 Who is it for:
- Swing traders looking for systematic long exposure on crypto pairs that frequently sweep liquidity into oversold readings.
- DCA-style traders who want averaging gated by momentum continuation, not just price levels — the "no falling knives" guard prevents loading further when momentum has already reversed.
- Bot operators who want to drive a DCA Bot via webhook with per-event JSON payloads tagged for each base / safety order / exit action.
- Traders comfortable with deploying up to ~10% of equity per trade in exchange for a wider 3% profit target.
🔷 How does it work:
Entry RSI Filter (Oversold Cross Down): A 15-minute RSI(7) is sampled via request.security with lookahead disabled. The entry gate fires when RSI crosses down through 30 — momentum has just entered oversold territory. At host-bar close, if no position is open and the cross is fresh, the strategy opens the base order.
Base Order: Sized at 100 USDT default (1% of 10k capital). Configurable as Market (default) or Limit at the bar's close.
Safety Order Ladder (Dual Gate): After the base fill, the strategy monitors two conditions in parallel for each pending safety order: price deviation downward against the position AND a static RSI continuation filter. The k-th safety order fires only when close ≤ base entry × (1 − cumulative deviation) AND the 15-minute RSI(7) is still below 25. Cumulative deviation grows by the step multiplier (default 2×): 1.00%, 3.00%, 7.00%, 15.00%. Each safety order's size grows by the size multiplier (default 2×): 60, 120, 240, 480 USDT.
Why the AO Gate Matters: A pure price-ladder DCA blindly averages into any decline. The RSI < 25 gate stops the averaging if momentum has reversed back above 25 — the asset is no longer oversold by the strategy's definition, and adding to the position would mean buying a recovery, not a dip. This filter trades off some averaging frequency for materially higher average-entry quality.
Exit: A fixed Take Profit at 3% above the running average entry. The strategy closes the moment close ≥ TP target. No trailing, no scaling out, no second-guessing.
🔷 Why it's unique:
- Dual RSI Gating: Most DCA tools gate only the base entry. This strategy gates both the entry (cross-down momentum trigger) and the continuation of averaging (static oversold filter on each safety order).
- Aggressive 2× × 2× Ladder: Most published DCAs use mild 1.05–1.25× compounding. This one doubles both the deviation step and the size each rung — the position gets large fast if all safety orders fill, but only inside a confirmed oversold regime.
- Wide Take Profit (3%): Most scalp DCAs use tight 0.5–1.0% TPs. The 3% target lets the strategy ride the oversold reversal further before locking in, capturing more of the mean-reversion move.
- DCA Bot Integration: Every event (base, AO 1–4, exit) emits a fully-formed JSON alert payload. Connect one alert to a DCA Bot's webhook URL and the strategy drives the bot end-to-end without any glue layer.
🔷 Considerations Before Using the Strategy:
Market & Timeframe: Defaults are calibrated for BINANCE:DOGEUSDT spot on 1h. The dual-RSI logic is portable to other liquid crypto pairs that frequently overshoot oversold, but RSI thresholds and the deviation ladder should be reviewed before redeployment.
Sample Size: The 4-month backtest produced 44 closed trades — below the ≥100 floor typically used for statistical confidence. The strategy generates roughly 11 closed trades per month at default settings, so extending the test window to 12+ months would yield ~130 trades and a more robust sample. The 77.27% win rate and 5.791 profit factor are encouraging but should be re-validated on a longer test period before live deployment.
Commission Calibration: The default 0.18% commission was set conservatively above Binance spot taker rates (~0.1%). Live performance with realistic Binance fees should be modestly better than the published numbers. Update the commission input to match your fee tier for accurate forward expectations.
Strong Downtrends: Like any oversold-buying setup, this strategy is positioned for mean reversions, not waterfall declines. In sustained downtrends the strategy will keep filling the ladder while RSI < 25, then hold the position once RSI recovers. The dual RSI filter limits exposure compared to pure price-ladder DCAs, but a regime shift to sustained selling still produces extended underwater hold time.
Aggressive Compounding: The 2× × 2× ladder is more aggressive than typical published DCAs. If all four safety orders fill, the position scales from 100 USDT base to 1,000 USDT total = 10% of equity at default settings. This is right at the upper edge of TradingView's typical 5–10% per-trade band — comfortable, but no further headroom. Scale base + AO sizes down to dial position risk lower.
No Stop Loss Justification: There is no exit on adverse moves beyond the 4-AO ladder. Per-trade risk is structurally capped by the bounded position-size ladder — at defaults that is 1,000 USDT max deployed = 10% of equity, at the upper edge of the conventional 5–10% per-trade band. If a hard exchange-side stop is required, layer it on the bot directly.
RSI Oversold Continuation: The AO gate uses a static RSI < 25 check, not a cross. This means averaging continues as long as RSI stays below 25 — if RSI dips to 20 and stays there for multiple bars while price drops further, all four AOs can fill in succession. Conversely, a sharp RSI recovery above 25 freezes the ladder mid-position. Test the strategy's behavior on your target asset before live deployment.
Demo Testing: Always demo-test before going live. Past results do not guarantee future performance, especially on a strategy whose profitability hinges on the asset reaching the 3% TP target while still recovering from an oversold print.
🔷 STRATEGY PROPERTIES
Symbol: BINANCE:DOGEUSDT (Spot)
Timeframe: 1H
Test Period: February 1, 2026 — May 28, 2026 (~4 months).
Initial Capital: 10,000 USDT.
Order Size per Trade: 1% of Capital base + 4 safety orders at 2× progression.
Max Capital Deployed: 1,000 USDT per trade (~10% of equity, upper edge of 5–10% band).
Commission: 0.18% per trade.
Slippage: 3 ticks.
Margin for Long Positions: 100%.
Indicator Settings: Default Configuration.
Base Order: 100 USDT, Market by default (Limit toggle available).
Take Profit: 3.0% above average entry (no trailing).
Stop Loss: None — bounded position size is the structural risk cap.
Entry Filter: 15m RSI(7) Crossing Down 30.
AO Gate: 15m RSI(7) Less Than 25 (static continuation filter).
Safety Orders: 4, Deviation 1.0%, Deviation Step 2.0×, Size Multiplier 2.0×.
Strategy: Long Only.
🔷 STRATEGY RESULTS
⚠️ Remember, past results do not guarantee future performance.
Net Profit: +126.22 USDT (+1.26%)
Max Equity Drawdown: 96.05 USDT (0.96%)
Total Closed Trades: 44
Percent Profitable: 77.27% (34 / 44)
Profit Factor: 5.791
🔷 How to Use It:
🔸 Adjust Settings: Open the strategy inputs and review the Base Order Size, the entry RSI filter (timeframe / length / level), the AO gate RSI filter, the 4-AO ladder parameters, and the Take Profit percentage. Defaults are calibrated for DOGEUSDT 2h — recalibrate per asset before deploying.
🔸 Results Review: Run a full-period backtest and confirm Max Drawdown stays inside your personal risk band. Validate that the closed-trade count is statistically meaningful (≥ 100 is a reasonable floor). Update commission and slippage to match your exchange's actual conditions.
🔸 Create alerts to trigger the DCA Bot: Add one alert on the strategy using "Any alert() function call". Paste the DCA Bot's webhook URL into the alert's Webhook field, and fill the Bot ID, Email Token, and Pair inputs on the script. The strategy will emit JSON payloads for entry, each safety order, and exit — formatted for direct DCA Bot consumption.
🔷 INDICATOR SETTINGS
Base Order Size (USDT): USDT amount opened on the long entry.
Use LIMIT for Base: Toggle between Market (default) and Limit at bar close.
Averaging Orders per Trade: Maximum number of safety orders per deal (default 4).
First AO Size (USDT): USDT size of the first safety order; subsequent AOs scale by the Size Multiplier.
Deviation to First AO (%): Distance from base entry at which AO1 becomes eligible.
Deviation Step Multiplier: Ladder factor that widens each subsequent deviation step.
Order Size Multiplier: Factor that grows each subsequent safety order's USDT size.
Entry RSI Timeframe / Length / Level: Lower-timeframe RSI filter that gates the base entry on cross down.
AO Trigger RSI Timeframe / Length / Less Than: Lower-timeframe RSI continuation filter that gates each safety order.
Take Profit (%): Fixed distance above average entry where the long closes for profit.
DCA Bot Webhook: Bot ID, Email Token, and Pair fields injected into every alert payload.
Visualization: Toggle AO Ladder, Avg / TP plot lines, fill labels, status table.
Brand Watermark: Configurable text, position, size, and transparency.
👨🏻💻💭 We hope this tool helps enhance your trading. Your feedback is invaluable, so feel free to share any suggestions for improvements or new features you'd like to see implemented.
__
The information and publications within the 3Commas TradingView account are not meant to be and do not constitute financial, investment, trading, or other types of advice or recommendations supplied or endorsed by 3Commas and any of the parties acting on behalf of 3Commas, including its employees, contractors, ambassadors, etc. אסטרטגייה

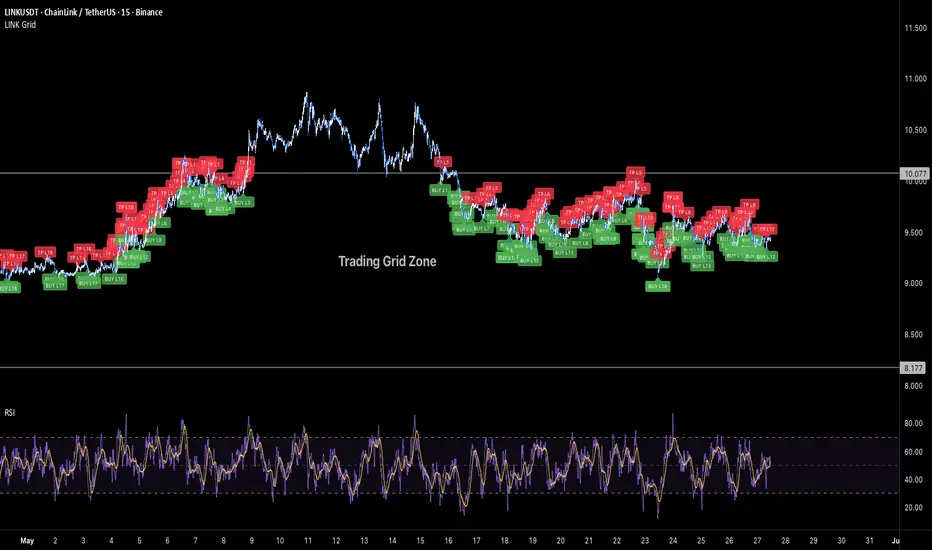
LINK Grid - Long IndicatorLINK Grid — Long Indicator
🔷 What it does:
This is a signal-only indicator that mirrors a price-grid long workflow on LINK / USDT between two fixed bounds. It tracks up to 36 independent virtual slots between a configurable High and Low — each slot fires a webhook-ready buy signal when price crosses down through it, and a paired sell signal when price subsequently crosses up through the slot immediately above. The indicator computes a running average entry, total deployed capital, and open PnL from the live slot ledger and renders all of it on the chart.
- Pre-computes 7–200 grid levels in Geometric (default) or Arithmetic spacing.
- Each slot is an independent ownership flag with its own buy/sell webhook payload.
- Avg entry is derived from fill-by-fill bookkeeping — total cost and total qty are updated on every event.
- Every event emits a webhook-ready JSON alert payload tagged with the specific grid slot.
🔷 Who is it for:
- Swing traders harvesting volatility on LINK in range-bound regimes.
- Bot operators looking for a chart-driven signal source that emits per-slot JSON ready for a DCA Bot configured for grid execution.
- Traders who want to monitor a virtual grid state — avg entry, owned slots, deployed capital, open PnL — directly on the chart without a backtest engine.
- Portfolio operators using a high-trade-count contributor alongside directional strategies.
🔷 How does it work:
Grid Construction: On script load, the indicator computes N price levels between the configured High and Low bounds. In Geometric mode (default), level k is at High × (Low/High)^(k/(N-1)), giving constant percent spacing — approximately 0.6% per step at default settings. In Arithmetic mode, levels are linearly spaced by absolute price.
Per-Slot State Machine: Each grid level is an independent slot tracked by a boolean ownership flag. When close price crosses down through an empty slot's level, the slot is marked owned, virtual cost-basis is added, and the BUY webhook payload is dispatched. When close price crosses up through the level immediately above an owned slot, the slot is marked free, virtual cost-basis is subtracted, and the SELL webhook payload is dispatched.
Honest Virtual Bookkeeping: Total cost and total qty are updated incrementally on each event, so the avg entry, deployed capital, and open PnL displayed in the status table reflect the actual broker-equivalent position state — no shortcuts from base entry, no synthetic averaging.
No Trailing, No Stop Loss: By design, each slot has a fixed exit (the level above). The indicator never trails the exit and never signals a slot-out for a loss — slots that fall below their entry stay owned until price comes back. This is the canonical grid-bot behavior.
🔷 Why it's unique:
- Per-Level Webhook Ledger: Every BUY and SELL emits a fully-formed JSON alert payload tagged with the specific grid slot ("Grid_BUY_L5" / "Grid_TP_L5"). The indicator can drive a DCA Bot configured for grid emulation without any glue layer.
- Fill-by-Fill Avg Entry: The orange avg-entry line is derived from running totals updated on every event — what you see is what the broker-equivalent position would actually have.
- Active Slot Highlighting: Owned grid levels are rendered with a thicker green stroke; empty slots stay dashed gray. Slot density and current loading are visible at a glance.
- Range Box & Bounds Labels: A semi-transparent box spans the configured High/Low range, and crisp HIGH/LOW labels mark the bounds — the grid topology is obvious without zooming.
- Calibrated for LINK 15m: Default bounds, level count, and step size are set against LINK's recent observed range — granular enough to catch frequent 15m round-trips, wide enough to avoid fee churn.
🔷 Considerations Before Using the Indicator:
Market Selection & Range Validity: Grid strategies are most profitable in range-bound, mean-reverting markets. On strong directional trends below the configured Low, slots will keep marking as owned as price falls and won't free until price reverses. The default High/Low (10.07 / 8.17) was set against LINK's recent observed range; update both whenever the regime changes.
Capital Deployment: The default Total Investment of 10,000 USDT is a virtual reference used for the avg-entry and open-PnL computation. The real sizing happens on the bot side — match the indicator's per-slot allocation to your bot's grid configuration to keep the avg-entry display honest.
Cross Detection Granularity: Crossings are detected on bar close, comparing the current close to the previous close. A bar that spikes through a level and returns within the same bar may be missed by design — this prevents over-signaling on intra-bar wicks.
Live vs Historical State: The virtual slot ledger is rebuilt from chart history each time the indicator is recompiled. If the indicator is added mid-deployment or the live bot diverges from the signal stream (manual interventions, partial fills), the indicator state may not match the live bot. Toggle the indicator off and on to reset.
No Stop Loss: There is no exit signal on adverse moves below the lowest grid level. Risk is structurally capped on the bot side by the bounded Total Investment configured at the bot. If a hard stop is required, layer it on the bot side.
Backtesting Note: This is an indicator, not a strategy. There is no built-in P&L tester. For performance metrics over a 3.5-month sample (~1,285 closed trades, 61.79% win rate, 9.96% max drawdown, profit factor 1.621, +14.82% net return), use the companion strategy version on identical parameters.
🔷 How to Use It:
🔸 Add the indicator to a LINK / USDT 15m chart.
🔸 Set the High and Low bounds to a range you expect LINK to respect.
🔸 Pick Geometric (default, recommended) or Arithmetic spacing.
🔸 Set Grid Levels (7–200) and the virtual Total Investment used for avg-entry computation.
🔸 In the DCA Bot Webhook group, paste your Bot ID, Email Token, and Pair (QUOTE_BASE format, e.g., USDT_LINK).
🔸 Create an alert on the indicator with "Any alert() function call". Paste the DCA Bot's webhook URL into the alert's Webhook field. Every grid-level buy and grid-level close will emit a dedicated JSON payload tagged with the slot index, so each level can be tracked independently downstream.
🔷 INDICATOR SETTINGS
High Price: Top of the grid. The highest level a slot can be created from.
Low Price: Bottom of the grid. The lowest level a slot can be created from.
Grid Levels: Number of price levels between High and Low (default 36, range 7–200).
Spacing Mode: Geometric (constant percent step) or Arithmetic (constant absolute step).
Total Investment (USDT): Virtual capital allocated across all slots. Used for the avg-entry and open-PnL computation only.
Bot ID / Email Token / Pair: Webhook fields injected into every alert payload.
Visualization: Toggle grid lines, range box, HIGH/LOW labels, avg entry plot, fill labels, signal triangles, status table.
Brand Watermark: Configurable text, position, size, and transparency.
👨🏻💻💭 We hope this tool helps enhance your trading. Your feedback is invaluable, so feel free to share any suggestions for improvements or new features you'd like to see implemented.
__
The information and publications within the 3Commas TradingView account are not meant to be and do not constitute financial, investment, trading, or other types of advice or recommendations supplied or endorsed by 3Commas and any of the parties acting on behalf of 3Commas, including its employees, contractors, ambassadors, etc. אינדיקטור

LINK Grid Bot - Long StrategyLINK Grid Bot — Long Strategy
🔷 What it does:
This is a long-only price-grid strategy that harvests volatility on LINK / USDT through repeated round-trips on a pre-defined ladder of price levels between two fixed bounds. Each level is an independent slot: when price crosses down through a level, the strategy opens one slot; when price subsequently crosses up through the level immediately above, that slot is closed for a fixed round-trip profit. The grid is generated geometrically by default, so spacing adapts to the price scale.
- Up to 36 simultaneous long slots at default settings, each sized as a fixed fraction of the configured Total Investment.
- No trailing exit, no stop loss — each slot's exit is the level above its entry.
- Per-slot exposure is approximately 2.78% of equity at default settings, comfortably inside the 5–10% per-trade risk band.
- Every fill and close emits a webhook-ready JSON alert payload tagged with the specific grid slot.
🔷 Who is it for:
- Swing traders harvesting volatility on LINK in range-bound regimes.
- Bot operators looking for a chart-driven signal source with per-slot webhook JSON ready to drive a DCA Bot configured for grid execution.
- Traders running a portfolio of low-correlation strategies who want a high-trade-count contributor with bounded per-trade risk.
- Range traders who prefer mechanical execution over discretionary entries.
🔷 How does it work:
Grid Construction: On script load, the strategy computes N price levels between the configured High and Low bounds. In Geometric mode (default), level k is at High × (Low/High)^(k/(N-1)), giving constant percent spacing — approximately 0.6% per step at default settings. In Arithmetic mode, levels are linearly spaced by absolute price.
Per-Slot Logic: Each grid level is an independent slot tracked by a boolean ownership flag. When bar close moves price down through an empty slot's level, a long is opened at that level for one slot's worth of capital (Investment / N). When bar close moves price up through the level immediately above an owned slot, that slot is closed, locking the round-trip profit between the two adjacent levels.
No Trailing, No Stop Loss: By design, each slot has a fixed exit (the level above). The strategy never trails the exit and never stops a slot out for a loss — slots whose entry price is below current market simply wait until price comes back. This is the canonical grid-bot behavior.
Capital Bounds: Total deployed capital cannot exceed the configured Investment. When all 36 slots are filled, no new orders are opened until price rises and starts closing slots. This structural cap is the strategy's primary risk control.
🔷 Why it's unique:
- Per-Level Webhook Ledger: Every fill and close emits a fully-formed JSON alert payload tagged with the specific grid slot ("Grid_BUY_L5" / "Grid_TP_L5"). The strategy can drive a DCA Bot configured for grid emulation without any glue layer.
- Pre-Allocated State: All up to 200 slot ledgers live in fixed-size arrays, so state lookups are constant-time and the chart can render every active slot with no performance overhead.
- Honest Backtest Surface: The avg entry line plotted on the chart and the open PnL displayed in the status table both reflect the actual broker-equivalent position state — derived from fill-by-fill bookkeeping, not synthetic averaging.
- Calibrated for LINK 15m: Default bounds, level count, and step size are set against LINK's recent observed range. The 36-level geometric ladder gives roughly 0.6% per step — granular enough to catch frequent 15m round-trips, wide enough to avoid fee churn.
🔷 Considerations Before Using the Strategy:
Market Selection & Range Validity: Grid strategies are most profitable in range-bound, mean-reverting markets. On strong directional trends below the configured Low, slots will keep loading as price falls and won't close until price reverses. The default High/Low (10.07 / 8.17) was set against LINK's recent observed range; update both whenever the regime changes.
Capital Deployment & Drawdown: The default Investment of 10,000 USDT equals 100% of starting capital — high-conviction setting that assumes the configured range holds. Backtest produced a 9.96% maximum equity drawdown at default settings, right at the upper edge of TradingView's typical 5–10% per-trade band. Per-slot risk remains low (~2.78% of equity), but if price collapses below the Low bound, aggregate unrealized loss can grow further. Scale the Investment input down to match the worst-case drawdown you are willing to absorb in a range-break scenario.
No Stop Loss Justification: There is no exit on adverse moves below the lowest grid level. The strategy's per-trade risk is structurally capped by the per-slot allocation (Investment / N levels) — at defaults that is 278 USDT per slot, well inside the conventional 5–10% per-trade band. The aggregate unrealized exposure is controlled separately via the Investment input.
Trade Volume & Fees: Grid bots on 15m generate a very high number of round-trips. The backtest produced 1,285 closed trades in 3.5 months — exceptional sample size, but also high cumulative fee load. The default commission (0.1% per trade) is calibrated for Binance / Bybit spot taker conditions; any mismatch with your exchange's actual fees will materially shift the results.
Demo Testing: Always demo-test before going live. Past results do not guarantee future performance, especially on a strategy whose profitability is bounded by the chosen High/Low range remaining valid.
🔷 STRATEGY PROPERTIES
Symbol: BINANCE:LINKUSDT (Spot) — strategy is portable to any LINK / USDT pair.
Timeframe: 15M
Test Period: February 11, 2026 — May 27, 2026 (~3.5 months).
Initial Capital: 10,000 USDT.
Total Investment: 10,000 USDT (100% of capital, high-conviction setting).
Order Size per Slot: Investment / 36 ≈ 278 USDT (~2.78% of equity).
Commission: 0.1% per trade.
Slippage: 3 ticks.
Margin for Long Positions: 100%.
Indicator Settings: Default Configuration.
Grid Bounds: High 10.07 / Low 8.17 (range −18.87%).
Grid Levels: 36 (Geometric spacing, ~0.6% per step).
Stop Loss: None — per-slot allocation is the structural risk cap.
Trailing: None.
Strategy: Long Only.
🔷 STRATEGY RESULTS
⚠️ Remember, past results do not guarantee future performance.
Net Profit: +1,482.00 USDT (+14.82%)
Max Equity Drawdown: 1,092.02 USDT (9.96%)
Total Closed Trades: 1,285
Percent Profitable: 61.79% (794 / 1,285)
Profit Factor: 1.621
🔷 How to Use It:
🔸 Adjust Settings: Open the strategy inputs and set the High and Low bounds to a range you expect LINK to respect. Pick Geometric for percent-spaced levels (default, recommended) or Arithmetic. Set Grid Levels (7–200) and Total Investment to match your risk profile.
🔸 Results Review: Run a full-period backtest and confirm Max Drawdown stays within your personal risk band. Validate that the trade count is high enough to be statistically meaningful (≥ 100 closed trades is a reasonable floor — at default settings the strategy typically generates several hundred to over a thousand round-trips per 3-month window on LINK 15m).
🔸 Create alerts to trigger the DCA Bot: Add one alert on the strategy using "Any alert() function call". Paste your DCA Bot's webhook URL into the alert's Webhook field, and fill the Bot ID, Email Token, and Pair inputs on the script. Every grid-level buy and grid-level close will emit a dedicated JSON payload tagged with the slot index, so each level can be tracked independently downstream.
🔷 INDICATOR SETTINGS
High Price: Top of the grid. The highest level a slot can be created from.
Low Price: Bottom of the grid. The lowest level a slot can be created from.
Grid Levels: Number of price levels between High and Low (default 36, range 7–200).
Spacing Mode: Geometric (constant percent step) or Arithmetic (constant absolute step).
Total Investment (USDT): Total capital allocated across all slots. Per-slot size = Investment / Grid Levels.
Bot ID / Email Token / Pair: Webhook fields injected into every alert payload.
Visualization: Toggle grid lines, range box, HIGH/LOW labels, avg entry plot, fill labels, status table.
Brand Watermark: Configurable text, position, size, and transparency.
👨🏻💻💭 We hope this tool helps enhance your trading. Your feedback is invaluable, so feel free to share any suggestions for improvements or new features you'd like to see implemented.
__
The information and publications within the 3Commas TradingView account are not meant to be and do not constitute financial, investment, trading, or other types of advice or recommendations supplied or endorsed by 3Commas and any of the parties acting on behalf of 3Commas, including its employees, contractors, ambassadors, etc. אסטרטגייה

אינדיקטור

Liquidity Gravity Map [PhenLabs]📊 Liquidity Gravity Map
Version: PineScript™ v6
📌 Description
The Liquidity Gravity Map is an advanced, quantitative approach to dynamic support and resistance detection. Rather than simply plotting static lines at prior highs and lows, this indicator treats liquidity as a gravitational force that accumulates, decays, and dynamically shifts based on price action and volume. It builds a real-time, scored “map” of liquidity zones on your chart, quantifying their structural integrity, mitigation behavior, and time-based decay.
It is designed to solve the problem of chart clutter and “false zones.” By continuously scoring and pruning liquidity pools based on their real-time relevance, structural significance, and VWAP acceptance, traders are presented only with the most critical, high-probability areas of interest where price is likely to be attracted or rejected.
🚀 Points of Innovation
Composite Scoring Engine: Zones are not binary. They are graded on a 0-100 scale using 7 distinct metrics: Structure, Revisits, Wicks, VWAP Context, Mitigation, Decay, and Proximity.
Dynamic Memory Allocation: Employs an internal memory cap (Max Zones) and a pruning algorithm to actively remove ancient, low-scoring zones, keeping the chart responsive and clean.
VWAP Acceptance Context: Integrates Session VWAP and Standard Deviation bands. The indicator scores zones higher if their creation aligns with bullish VWAP reclaims or bearish VWAP rejections.
Mitigation & Absorption Tracking: Dynamically evaluates how price interacts with a zone. It tracks volume, penetration depth, and displacement to quantify if a zone is being absorbed (defended) or broken.
Time-Decay Function: Untouched liquidity zones lose their “gravitational pull” over time via an exponential decay function, prioritizing fresh liquidity.
🔧 Core Components
Zone Detection Algorithm: Identifies swing highs/lows and stop-hunt wicks, factoring in equal highs/lows clustering and wick ratios to establish initial structural strength.
Session VWAP Engine: Calculates volume-weighted average price and its standard deviations over configurable sessions (RTH, Day, Week, Month) to gauge macro context and acceptance.
Revisit Tracker: Monitors how many times a zone is tested. A zone’s score adjusts based on its frequency of testing relative to other active zones on the chart.
🔥 Key Features
Live Composite Score (0-100) dynamically updated per zone.
Automatic culling of stale, irrelevant liquidity levels.
Highly customizable lookback, zone sensitivity, and memory caps.
Dynamic gradient coloring based on zone score (Bullish/Bearish).
Toggleable Zone Labels displaying directional bias, score, and revisit count.
🎨 Visualization
Gradient Liquidity Boxes: Visualizes liquidity zones as shaded boxes. The opacity and color temperature (cool to warm) dynamically change based on the zone’s live composite score.
VWAP Bands: Optional visual overlay of the Session VWAP and ±1σ / ±2σ standard deviation bands.
Zone Labels: Small text labels attached to active boxes indicating “BULL” or “BEAR”, the “LG” (Liquidity Gravity) score, and “R” (Revisits).
📖 Usage Guidelines
Core Settings
Lookback Period: (Default: 120) Determines the window for identifying stop-hunts and aging cleanup.
Zone Sensitivity: (Default: 3.0) Controls the width of the generated zones and the tolerance for merging equal highs/lows. Higher values create wider, merged bands.
Max Visible Zones: (Default: 8) The maximum number of top-scoring zones to render on the chart at one time.
Score Decay Rate: (Default: 0.010) The exponential rate at which a zone’s score drops while untouched.
VWAP Acceptance Settings
VWAP Session Type: (Default: Day) Anchor period for the VWAP calculations (RTH, Day, Week, Month).
RTH Session: (Default: 0930-1600) Defines Regular Trading Hours if “RTH” is selected as the session type.
Visual Settings
Color Theme: (Default: Classic) Choose between Classic, Neon, or Monochrome color palettes for the zone gradients.
✅ Best Use Cases
Identifying high-probability reversal areas for mean-reversion trading.
Spotting areas where trapped liquidity (stop-hunts) is likely to act as a strong magnet for price.
Filtering out weak support/resistance levels by relying on the composite score to highlight only structurally significant, defended zones.
⚠️ Limitations
Rapidly changing volatility can cause sudden shifts in zone width, as it is dynamically tied to the Average True Range (ATR).
Because the map limits the number of visible zones to the highest scoring ones, a valid but slightly lower-scoring zone might be hidden from view.
💡 What Makes This Unique
Quantitative Liquidity Modeling: Most indicators draw static boxes at highs/lows. This script dynamically evaluates the “health” of a zone through continuous math—scoring penetration, volume absorption, decay, and VWAP alignment.
🔬 How It Works
1. Detection & Generation:
The script continuously monitors for structural pivots and significant wicks. When detected, a zone is created with an initial strength score based on structural clustering and ATR.
2. Continuous Evaluation:
Every confirmed bar, the script updates active zones. It tracks if price has touched the zone, penetrated it, or been rejected, factoring in relative volume to determine if the liquidity was absorbed or broken.
3. Scoring & Display:
A final 0-100 score is computed using structural integrity, VWAP context, wicks, revisits, decay, and proximity to current price. Only the top “N” scoring zones are dynamically rendered on the chart.
💡 Note: Ensure your chart data provides reliable volume data, as the absorption and VWAP scoring mechanics heavily rely on it for accurate calculations. אינדיקטור

אינדיקטור
Price to Sales Ratio [Gabremoku]Price to Sales Ratio is a valuation indicator designed to help investors analyze how expensive or cheap a stock is relative to its revenue.
The script calculates the P/S ratio using market capitalization divided by total trailing-twelve-month revenue, then enriches that raw valuation with historical averages, rolling Z-score, percentile ranking, 52-week extremes, and sector benchmark comparison. The price-to-sales ratio is commonly used as a revenue multiple, especially for companies where earnings may be weak, negative, or highly variable.
This makes the indicator useful for growth stocks, cyclical companies, and early-stage businesses where price-to-earnings can be less informative than revenue-based valuation.
What it shows
📊 Current P/S Ratio — the live valuation multiple based on:
current stock price
total shares outstanding
trailing-twelve-month revenue
📈 Historical Average — choose between:
Cumulative Average for the full available history
Rolling Average based on a user-defined lookback in years
🧮 Z-Score Mode — switch from raw P/S to a statistical valuation view that shows how far the current ratio is from its rolling average in standard deviations.
📍 Historical Percentile — shows where the current P/S sits within its historical range over the selected lookback.
📅 52-Week High / Low — provides a fast valuation range reference for the last trading year.
🏭 Sector Benchmark — compare the company’s P/S ratio against a benchmark using:
Auto-detected sector
Sector index
Manual sector value
Why P/S matters
The P/S ratio tells you how much investors are paying for each dollar of company revenue. A lower P/S ratio is often considered more attractive when comparing similar companies in the same industry, but sector differences matter a lot.
That last part is important: P/S should not be judged in isolation. Technology companies often trade at much higher revenue multiples than energy, materials, or consumer businesses, so comparing a stock only against a generic threshold can be misleading. Sector-relative comparison is generally more meaningful than absolute comparison.
Benchmark logic
This indicator includes one of its strongest features: sector context.
It can automatically estimate a sector benchmark through:
exact ticker lookup
keyword-based sector detection
manual fallback sector selection
That matters because P/S multiples vary materially by industry, and valuation comparison is most useful when done against companies or sectors with similar economic characteristics.
The script then colors the main P/S line with a practical valuation model:
🟢 Green — P/S below benchmark, potentially undervalued relative to sector
🟠 Orange — P/S above benchmark but below historical average, more neutral / fair-value zone
🔴 Red — P/S above historical average, potentially expensive relative to its own history
Features
✅ Live Price-to-Sales ratio calculation
✅ Uses total shares outstanding and TTM revenue
✅ Cumulative or rolling historical average
✅ Z-score mode for statistical valuation
✅ Historical percentile ranking
✅ 52-week valuation high/low
✅ Sector benchmark comparison
✅ Auto sector detection with hybrid logic
✅ Manual and sector-index benchmark options
✅ Dynamic color coding based on valuation regime
✅ Ultra-smooth gradient fill between current P/S and benchmark
✅ Dashboard with key statistics
✅ Last-value chart label
How to use
A practical way to read the script is:
🔎 Start with the current P/S ratio.
📊 Compare it with the sector benchmark to see whether the stock trades richer or cheaper than its industry.
🧮 Check the Z-score to understand whether the current valuation is stretched versus its own historical behavior.
📍 Use the percentile to see where today’s valuation sits within the selected lookback window.
This approach combines absolute valuation, relative valuation, and historical context in one screen, which is much more useful than reading the raw P/S ratio alone.
Operational suggestion
💡 Suggested workflow
🟢 Value watchlist setup: look for stocks with current P/S below sector benchmark and below their own historical average. A lower P/S relative to peers can indicate more attractive valuation, provided the business quality is not deteriorating.
🟠 Neutral zone: if the stock is above benchmark but still below or near its historical average, it may be in a fairer valuation zone rather than clearly cheap or expensive.
🔴 Stretch zone: if the stock is trading with a high Z-score, high percentile, and above both benchmark and average, it may be priced aggressively relative to its own history and sector context.
📈 Best use case: this indicator is especially useful for companies with unstable earnings, where P/E may be less reliable and revenue multiples can provide a cleaner valuation anchor.
A strong practical rule:
use P/S for initial screening
use sector benchmark for context
use Z-score and percentile for timing
then confirm with margins, growth, debt, and cash flow
Because revenue alone does not tell you whether that revenue is profitable.
Notes
This indicator is best suited for relative valuation analysis, not for making a final investment decision on its own. A low P/S ratio can reflect undervaluation, but it can also reflect weak margins, declining sales quality, or poor business outlook, so it should always be paired with profitability and growth analysis.
Author: Gabremoku אינדיקטור

אינדיקטור

אינדיקטור

אינדיקטור

אינדיקטור

אינדיקטור

% From Open Watermark% From Open Watermark displays the current percentage change from the session open as a large, semi-transparent watermark overlaid on your chart. It calculates the move from the daily, weekly, or monthly open (your choice) to the current close and updates in real time as price moves. The text color shifts automatically, turning green when you're up on the session, red when you're down, and gray when flat. This gives you an at-a-glance read on session performance without having to do mental math or glance at a separate panel.
The watermark is fully customizable. Place it in any of nine positions on the chart (top, middle, or bottom paired with left, center, or right), choose from six text sizes including an auto-scaling option, and adjust the transparency and colors to match your chart theme. You can toggle the leading "+" sign on positive moves and set decimal precision from 0 to 4 places. Because it renders as a positioned table rather than a price-anchored label, it stays put as you scroll and zoom, just like a real watermark. אינדיקטור

NVDAX Grid - Long IndicatorNVDAX Grid — Long Indicator
🔷 What it does:
This is a signal-only indicator that mirrors a price-grid long workflow on NVDAX / USDT between two fixed bounds. It tracks up to 56 independent virtual slots between a configurable High and Low — each slot fires a webhook-ready buy signal when price crosses down through it, and a paired sell signal when price subsequently crosses up through the slot immediately above. The indicator computes a running average entry, total deployed capital, and open PnL from the live slot ledger and renders all of it on the chart.
- Pre-computes 7–200 grid levels in Geometric (default) or Arithmetic spacing.
- Each slot is an independent ownership flag with its own buy/sell webhook payload.
- Avg entry is derived from fill-by-fill bookkeeping — total cost and total qty are updated on every event.
- Every event emits a webhook-ready JSON alert payload tagged with the specific grid slot.
🔷 Who is it for:
- Swing traders harvesting volatility on tokenized equity pairs in range-bound regimes.
- Bot operators looking for a chart-driven signal source that emits per-slot JSON ready for a DCA Bot configured for grid execution.
- Traders who want to monitor a virtual grid state — avg entry, owned slots, deployed capital, open PnL — directly on the chart without a backtest engine.
- Portfolio operators using a high-trade-count contributor alongside directional strategies.
🔷 How does it work:
Grid Construction: On script load, the indicator computes N price levels between the configured High and Low bounds. In Geometric mode (default), level k is at High × (Low/High)^(k/(N-1)), giving constant percent spacing — approximately 0.58–0.85% per step at default settings. In Arithmetic mode, levels are linearly spaced by absolute price.
Per-Slot State Machine: Each grid level is an independent slot tracked by a boolean ownership flag. When close price crosses down through an empty slot's level, the slot is marked owned, virtual cost-basis is added, and the BUY webhook payload is dispatched. When close price crosses up through the level immediately above an owned slot, the slot is marked free, virtual cost-basis is subtracted, and the SELL webhook payload is dispatched.
Honest Virtual Bookkeeping: Total cost and total qty are updated incrementally on each event, so the avg entry, deployed capital, and open PnL displayed in the status table reflect the actual broker-equivalent position state — no shortcuts from base entry, no synthetic averaging.
No Trailing, No Stop Loss: By design, each slot has a fixed exit (the level above). The indicator never trails the exit and never signals a slot-out for a loss — slots that fall below their entry stay owned until price comes back. This is the canonical grid-bot behavior.
🔷 Why it's unique:
- Per-Level Webhook Ledger: Every BUY and SELL emits a fully-formed JSON alert payload tagged with the specific grid slot ("Grid_BUY_L5" / "Grid_TP_L5"). The indicator can drive a DCA Bot configured for grid emulation without any glue layer.
- Fill-by-Fill Avg Entry: The orange avg-entry line is derived from running totals updated on every event — what you see is what the broker-equivalent position would actually have.
- Active Slot Highlighting: Owned grid levels are rendered with a thicker green stroke; empty slots stay dashed gray. Slot density and current loading are visible at a glance.
- Range Box & Bounds Labels: A semi-transparent box spans the configured High/Low range, and crisp HIGH/LOW labels mark the bounds — the grid topology is obvious without zooming.
- Calibrated for NVDAX 15m: Default bounds, level count, and step size are set against NVDAX's observed historical range — granular enough to catch frequent 15m round-trips, wide enough to avoid fee churn.
🔷 Considerations Before Using the Indicator:
Market Selection & Range Validity: Grid strategies are most profitable in range-bound, mean-reverting markets. On strong directional trends below the configured Low, slots will keep marking as owned as price falls and won't free until price reverses. The default High/Low (226.83 / 154.16) was set against NVDAX's observed range; update both whenever the regime changes.
Tokenized Equity Specifics: NVDAX is a tokenized derivative tracking NVDA equity. Off-hours liquidity and gap behavior can differ from spot crypto pairs — review the asset's session profile before relying on the signal stream for live deployment.
Capital Deployment: The default Total Investment of 10,000 USDT is a virtual reference used for the avg-entry and open-PnL computation. The real sizing happens on the bot side — match the indicator's per-slot allocation to your bot's grid configuration to keep the avg-entry display honest.
Cross Detection Granularity: Crossings are detected on bar close, comparing the current close to the previous close. A bar that spikes through a level and returns within the same bar may be missed by design — this prevents over-signaling on intra-bar wicks.
Live vs Historical State: The virtual slot ledger is rebuilt from chart history each time the indicator is recompiled. If the indicator is added mid-deployment or the live bot diverges from the signal stream (manual interventions, partial fills), the indicator state may not match the live bot. Toggle the indicator off and on to reset.
No Stop Loss: There is no exit signal on adverse moves below the lowest grid level. Risk is structurally capped on the bot side by the bounded Total Investment configured at the bot. If a hard stop is required, layer it on the bot side.
Backtesting Note: This is an indicator, not a strategy. There is no built-in P&L tester. For performance metrics over a four-month sample (~542 closed trades, 4.60% max drawdown, profit factor 2.098), use the companion strategy version on identical parameters.
🔷 How to Use It:
🔸 Add the indicator to a NVDAX / USDT 15m chart.
🔸 Set the High and Low bounds to a range you expect NVDAX to respect.
🔸 Pick Geometric (default, recommended) or Arithmetic spacing.
🔸 Set Grid Levels (7–200) and the virtual Total Investment used for avg-entry computation.
🔸 In the DCA Bot Webhook group, paste your Bot ID, Email Token, and Pair (QUOTE_BASE format, e.g., USDT_NVDAX).
🔸 Create an alert on the indicator with "Any alert() function call". Paste the DCA Bot's webhook URL into the alert's Webhook field. Every grid-level buy and grid-level close will emit a dedicated JSON payload tagged with the slot index, so each level can be tracked independently downstream.
🔷 INDICATOR SETTINGS
High Price: Top of the grid. The highest level a slot can be created from.
Low Price: Bottom of the grid. The lowest level a slot can be created from.
Grid Levels: Number of price levels between High and Low (default 56, range 7–200).
Spacing Mode: Geometric (constant percent step) or Arithmetic (constant absolute step).
Total Investment (USDT): Virtual capital allocated across all slots. Used for the avg-entry and open-PnL computation only.
Bot ID / Email Token / Pair: Webhook fields injected into every alert payload.
Visualization: Toggle grid lines, range box, HIGH/LOW labels, avg entry plot, fill labels, signal triangles, status table.
Brand Watermark: Configurable text, position, size, and transparency.
👨🏻💻💭 We hope this tool helps enhance your trading. Your feedback is invaluable, so feel free to share any suggestions for improvements or new features you'd like to see implemented.
__
The information and publications within the 3Commas TradingView account are not meant to be and do not constitute financial, investment, trading, or other types of advice or recommendations supplied or endorsed by 3Commas and any of the parties acting on behalf of 3Commas, including its employees, contractors, ambassadors, etc. אינדיקטור

AetherEdge - Sentiment-Proxy Correlation Mapper🖊️ Overview
A psychology-focused engine that infers crowd emotion without any social or news feed — purely from price action. It builds sentiment proxies — volume anomaly (panic/euphoria), volatility (fear), price velocity (momentum drive), wick asymmetry (greed vs. fear at extremes), and run-length (FOMO / capitulation) — then uses a NeuraLib correlation map to learn how these proxies move together and weighs them into a single Fear ⇄ Greed sentiment score. A self-adapting mapping continuously re-correlates the proxies against realized outcomes, and the engine flags sentiment turning points — the moments crowd emotion flips. Visualization: a chart-background gradient shading the tape from Fear (red) to Greed (green), plus emphasis dots only at the reversals.
🔶 Key Features
Sentiment proxies — five emotion proxies built from price action alone (no external data)
NeuraLib correlation mapping — learns the proxies' joint behavior and fuses them into a Fear⇄Greed score
Self-adapting correlation — continuously re-correlates proxies against realized outcomes (learns which matter)
Turning-point detection — flags fear⇄greed reversals on a zero-line cross with sufficient swing
Sentiment background gradient — shades the chart from fear (red) through neutral to greed (green), intensity by magnitude
Turning-point dots — only the reversal moments are emphasized with dots and labels (noise excluded)
Emotional extreme markers — faint diamonds when sentiment enters a greed/fear extreme zone
Intelligence panel — Fear⇄Greed gauge, each proxy's value and learned correlation strength, and the latest turn
🧠 Technical Architecture
The engine builds five sentiment proxies from price: (1) volume anomaly (volume z-score × candle direction = euphoric buying / panic selling), (2) volatility (ATR ratio = higher is fear/stress), (3) price velocity (ATR-normalized speed of change = momentum), (4) wick asymmetry (lower − upper wick = which side defended the extreme), and (5) run-length (consecutive up/down within the window = FOMO / capitulation).
These feed the NeuraLib correlation map: proxies(5) → hidden(tanh) → sentiment(1, tanh-bounded ), trained by supervision so sentiment correlates with realized forward direction — greed (positive) preceding up-moves, fear (negative) preceding down-moves. After each step, each proxy's contribution to the hidden layer (mean absolute weight) is recomputed as its correlation strength, shown in the panel so you can see which proxy currently dominates emotion.
Sentiment is smoothed into a Fear⇄Greed score. Turning-point detection flags a fear→greed (or reverse) reversal when a zero-line cross's magnitude clears the Turn Sensitivity. The background is colored continuously by color.from_gradient, with intensity proportional to emotional magnitude.
⚙️ Recommended Settings & Tuning Guide
BTC (1H–4H): Volume 20, Volatility 14, Velocity 10, Smoothing 4, Turn Sensitivity 0.20. Standard settings fit well
ETH (1H–4H): As BTC, with Outcome Lookahead 5–8
SOL (15m–1H): High volatility favors Smoothing 5–6 to smooth sentiment, Turn Sensitivity 0.25 to suppress false turns
XRP (1H–4H): Spike-prone; Volume window 15 for sensitive anomaly detection, Extreme Threshold 0.5 for early extremes
Turn Sensitivity: higher makes turns selective (only large emotional reversals); lower detects more frequently
Extreme Threshold: beyond ±this is "extreme greed/fear" — a contrarian guide at 0.5–0.6
Sentiment Smoothing: higher smooths the background and score; lower is more reactive
Background Intensity: lower makes the background more vivid — adjust to taste
💡 How to Use in Practice
Reading the gradient: deep green = greed dominates (possible overheating); deep red = fear dominates (possible capitulation); neutral = balanced — saturation is emotional strength
Using turning-point dots: a "FEAR→GREED" dot marks a flip from fear to greed (possible bottom); "GREED→FEAR" a possible top — a basis for contrarian/trend entries
Contrarian at extremes: at extreme greed (green diamond) beware a pullback from overheating; at extreme fear (red diamond) watch for an oversold bounce — quantifying "be fearful when others are greedy"
Watching proxy correlations: the panel's per-proxy value and correlation strength reveal what drives emotion now (e.g. high volume-anomaly correlation = volume-led sentiment)
Background vs. price divergence: price rising while the background reads fear (bearish sentiment) is an early reversal warning
Multi-timeframe usage: read the big-picture emotional regime on the higher timeframe (4H), then time entries on turning points on the lower one (15m–1H)
⚠️ Important Notes
Nature of proxies: this is not real social/news sentiment but an estimated proxy inferred from price action — an approximation of crowd psychology that differs from external sentiment data
Initial learning period: right after launch the map's buffer is nearly empty and emotion estimates are unstable; treat as low-confidence until it fills (100+ bars)
Learning resets: changing parameters, switching symbol/timeframe, or recompiling reinitializes the map weights and buffer, restarting learning from zero
Danger of contrarianism: extreme emotion can persist (greed runs long in strong trends) — an extreme is not an instant reversal; pair with risk management
On look-ahead: the map's target uses closed-bar realized direction (a standard training construct); current-bar emotion is on confirmed values, but as with any adaptive system, historical and live behavior can differ — always forward-test
Constraints: this is a lightweight implementation operating within Pine's compute budget
🚨 Disclaimer
This indicator is an analytical and educational visualization tool. The sentiment proxies, correlation mapping, Fear⇄Greed score, turning-point detection, and sentiment background are quantitative heuristics computed on-chart from price data — they are not financial advice, buy/sell signals, or any guarantee of future performance. Estimates of crowd psychology can be wrong. Always combine any tool with your own analysis and disciplined risk management. אינדיקטור

אינדיקטור

אינדיקטור

אינדיקטור

NVDAX Grid Bot - Long StrategyNVDAX Grid Bot — Long Strategy
🔷 What it does:
This is a long-only price-grid strategy that harvests volatility on NVDAX / USDT through repeated round-trips on a pre-defined ladder of price levels between two fixed bounds. Each level is an independent slot: when price crosses down through a level, the strategy opens one slot; when price subsequently crosses up through the level immediately above, that slot is closed for a fixed round-trip profit. The grid is generated geometrically by default, so spacing adapts to the price scale.
- Up to 56 simultaneous long slots at default settings, each sized as a fixed fraction of the configured Total Investment.
- No trailing exit, no stop loss — each slot's exit is the level above its entry.
- Per-slot exposure is approximately 1.8% of equity at default settings, comfortably inside the 5–10% per-trade risk band.
- Every fill and close emits a webhook-ready JSON alert payload tagged with the specific grid slot.
🔷 Who is it for:
- Swing traders harvesting volatility on tokenized equity pairs in range-bound regimes.
- Bot operators looking for a chart-driven signal source with per-slot webhook JSON ready to drive a DCA Bot configured for grid execution.
- Traders running a portfolio of low-correlation strategies who want a high-trade-count contributor with bounded per-trade risk.
- Range traders who prefer mechanical execution over discretionary entries.
🔷 How does it work:
Grid Construction: On script load, the strategy computes N price levels between the configured High and Low bounds. In Geometric mode (default), level k is at High × (Low/High)^(k/(N-1)), giving constant percent spacing — approximately 0.58–0.85% per step at default settings. In Arithmetic mode, levels are linearly spaced by absolute price.
Per-Slot Logic: Each grid level is an independent slot tracked by a boolean ownership flag. When bar close moves price down through an empty slot's level, a long is opened at that level for one slot's worth of capital (Investment / N). When bar close moves price up through the level immediately above an owned slot, that slot is closed, locking the round-trip profit between the two adjacent levels.
No Trailing, No Stop Loss: By design, each slot has a fixed exit (the level above). The strategy never trails the exit and never stops a slot out for a loss — slots whose entry price is below current market simply wait until price comes back. This is the canonical grid-bot behavior.
Capital Bounds: Total deployed capital cannot exceed the configured Investment. When all 56 slots are filled, no new orders are opened until price rises and starts closing slots. This structural cap is the strategy's primary risk control.
🔷 Why it's unique:
- Per-Level Webhook Ledger: Every fill and close emits a fully-formed JSON alert payload tagged with the specific grid slot ("Grid_BUY_L5" / "Grid_TP_L5"). The strategy can drive a DCA Bot configured for grid emulation without any glue layer.
- Pre-Allocated State: All up to 200 slot ledgers live in fixed-size arrays, so state lookups are constant-time and the chart can render every active slot with no performance overhead.
- Honest Backtest Surface: The avg entry line plotted on the chart and the open PnL displayed in the status table both reflect the actual broker-equivalent position state — derived from fill-by-fill bookkeeping, not synthetic averaging.
- Calibrated for NVDAX 15m: Default bounds, level count, and step size are set against NVDAX's observed historical range. The 56-level geometric ladder gives roughly 0.58–0.85% per step — granular enough to catch frequent 15m round-trips, wide enough to avoid fee churn.
🔷 Considerations Before Using the Strategy:
Market Selection & Range Validity: Grid strategies are most profitable in range-bound, mean-reverting markets. On strong directional trends below the configured Low, slots will keep loading as price falls and won't close until price reverses. The default High/Low (226.83 / 154.16) was set against NVDAX's observed range; update both whenever the regime changes.
Tokenized Equity Specifics: NVDAX is a tokenized derivative tracking NVDA equity. Off-hours liquidity and gap behavior can differ from spot crypto pairs — review the asset's session profile before relying on the backtest numbers for live deployment.
Capital Deployment: The default Investment of 10,000 USDT equals 100% of starting capital — this is a high-conviction setting that assumes the configured range holds. Per-slot risk remains low (~1.8% of capital), but if price collapses far below the Low bound, the aggregate unrealized loss can be substantial. Scale the Investment input down to match the worst-case drawdown you are willing to absorb in a range-break scenario.
No Stop Loss Justification: There is no exit on adverse moves below the lowest grid level. The strategy's per-trade risk is structurally capped by the per-slot allocation (Investment / N levels) — at defaults that is 179 USDT per slot, well inside the conventional 5–10% per-trade band. The aggregate unrealized exposure is controlled separately via the Investment input.
Trade Volume & Fees: Grid bots on 15m generate a high number of round-trips. The default commission (0.1% per trade) is calibrated for Bybit spot taker conditions; any mismatch with your exchange's actual fees will materially shift the results given the high trade count.
Demo Testing: Always demo-test before going live. Past results do not guarantee future performance, especially on a strategy whose profitability is bounded by the chosen High/Low range remaining valid.
🔷 STRATEGY PROPERTIES
Symbol: BYBIT:NVDAXUSDT (Spot)
Timeframe: 15min
Test Period: January 23, 2026 — May 24, 2026 (~4 months).
Initial Capital: 10,000 USDT.
Total Investment: 10,000 USDT (100% of capital, high-conviction setting).
Order Size per Slot: Investment / 56 ≈ 179 USDT (~1.8% of equity).
Commission: 0.1% per trade.
Slippage: 3 ticks.
Margin for Long Positions: 100%.
Indicator Settings: Default Configuration.
Grid Bounds: High 226.83 / Low 154.16 (range −30%).
Grid Levels: 56 (Geometric spacing, ~0.58–0.85% per step).
Stop Loss: None — per-slot allocation is the structural risk cap.
Trailing: None.
Strategy: Long Only.
🔷 STRATEGY RESULTS
⚠️ Remember, past results do not guarantee future performance.
Net Profit: +662.81 USDT (+6.63%)
Max Equity Drawdown: 468.04 USDT (4.60%)
Total Closed Trades: 542
Percent Profitable: 62.55% (339 / 542)
Profit Factor: 2.098
🔷 How to Use It:
🔸 Adjust Settings: Open the strategy inputs and set the High and Low bounds to a range you expect NVDAX to respect. Pick Geometric for percent-spaced levels (default, recommended) or Arithmetic. Set Grid Levels (7–200) and Total Investment to match your risk profile.
🔸 Results Review: Run a full-period backtest and confirm Max Drawdown stays within your personal risk band. Validate that the trade count is high enough to be statistically meaningful (≥ 100 closed trades is a reasonable floor — at default settings the strategy typically generates several hundred round-trips per 90-day window on NVDAX 15m).
🔸 Create alerts to trigger the DCA Bot: Add one alert on the strategy using "Any alert() function call". Paste your DCA Bot's webhook URL into the alert's Webhook field, and fill the Bot ID, Email Token, and Pair inputs on the script. Every grid-level buy and grid-level close will emit a dedicated JSON payload tagged with the slot index, so each level can be tracked independently downstream.
🔷 INDICATOR SETTINGS
High Price: Top of the grid. The highest level a slot can be created from.
Low Price: Bottom of the grid. The lowest level a slot can be created from.
Grid Levels: Number of price levels between High and Low (default 56, range 7–200).
Spacing Mode: Geometric (constant percent step) or Arithmetic (constant absolute step).
Total Investment (USDT): Total capital allocated across all slots. Per-slot size = Investment / Grid Levels.
Bot ID / Email Token / Pair: Webhook fields injected into every alert payload.
Visualization: Toggle grid lines, range box, HIGH/LOW labels, avg entry plot, fill labels, status table.
Brand Watermark: Configurable text, position, size, and transparency.
👨🏻💻💭 We hope this tool helps enhance your trading. Your feedback is invaluable, so feel free to share any suggestions for improvements or new features you'd like to see implemented.
__
The information and publications within the 3Commas TradingView account are not meant to be and do not constitute financial, investment, trading, or other types of advice or recommendations supplied or endorsed by 3Commas and any of the parties acting on behalf of 3Commas, including its employees, contractors, ambassadors, etc. אסטרטגייה

Risk Manager [SkaleHub]Overview
The ultimate capital preservation tool. This indicator calculates mathematically secure stop-loss placements based on real-time market volatility (ATR) and features a dynamic dashboard that tells you the exact position size to take to protect your account.
The Edge
Amateurs blow accounts by guessing their lot sizes and placing arbitrary stop-losses. This tool professionalizes your risk. By adjusting your position size relative to the asset's current volatility, it ensures that whether you are trading a quiet forex pair or a volatile crypto asset, your monetary risk remains an exact, controlled percentage of your capital.
Key Features:
Volatility-Based Stops: Automatically calculates stop-loss levels using the Average True Range (ATR), ensuring your stop is safely tucked behind the market's natural "noise" to prevent early liquidations.
Auto-Position Sizing: Input your account balance and risk tolerance (e.g., 1%), and the built-in dashboard instantly outputs the exact number of shares or units you should buy.
On-Chart Visual Guardrails: Optionally plots dynamic crosshair lines on the chart so you can visually see exactly where your mathematically optimized stop-loss should be placed before entering a trade.
How to Use
Apply the indicator and open the settings menu. Enter your total account balance and your strict risk percentage (1-2% is highly recommended).
When your Level 3 Momentum Trigger fires an entry signal, look at the Risk Manager dashboard in the corner of your screen.
Execute the trade using the exact "Position Size (Units)" displayed on the dashboard, and immediately set your hard stop-loss at the "Stop Distance" mapped out on the chart.
Author's Note
This is a premium, Invite-Only script. It is Level 4 of the SkaleHub Training System. To gain access, your TradingView username must be explicitly authorized through the SkaleHub Academy. אינדיקטור