24-hour Volumeoppock Curve Multi-Filter is a trend and momentum-based indicator designed to identify potential high-probability Long and Short opportunities. It combines the Coppock Curve with multiple confirmation filters to determine market bias and provides visual Entry, Stop Loss, TP1, TP2 and TP3 levels.
Use the indicator alongside market structure, support/resistance and price action for confirmation. It is designed as a decision-support and risk-management tool, not a guaranteed signal generator. Always apply proper risk management.
If you want, I can also write you a much more professional TradingView publication description with sections like “How It Works,” “Buy Conditions,” “Sell Conditions,” “Risk Management,” and “Settings,” tailored specifically to your script.
אינדיקטור

אינדיקטור

ספרייה

ATK / DEF Multi-Session Volatility DynamicsATK / DEF — Multi-Session Volatility Dynamics is a multi-session market analysis framework built around three market sessions:
**Asia, Europe, and America**
The framework separates market activity by session and combines session identification, price structure, volume-based conditions, liquidity classification, volatility state, and visual reference areas within a unified chart interface.
## Core Features
* Asia Session
* Europe Session
* America Session
* Independent session configuration
* Configurable session start and end times
* Multiple timezone options
* Session-specific visual identification
* Volume-based market condition classification
* Liquidity level classification
* Volatility state classification
* Candle body-to-range measurement
* Session-based Order Block reference areas
* Session-specific Order Block labels
* Adjustable Swing detection parameters
* Configurable display range
* Progress and status table
* Chart status-line measurements
## Multi-Session Framework
The indicator separates three configurable market sessions:
**Asia → Europe → America**
Each session maintains its own identity on the chart, allowing the displayed structures and calculated conditions to remain associated with their corresponding session.
Session settings can be independently enabled or disabled, with configurable opening and closing times.
## Session-Based Market Analysis
Market conditions are evaluated within the configured session environment using a combination of internal calculations based on:
* Volume
* Price position
* Candle body size
* Total candle range
* ATR
* Historical volume averages
* Historical ATR averages
The framework displays calculated states directly on the chart without converting them into trading signals.
## Liquidity Classification
The indicator includes a volume-based liquidity classification using relative volume conditions.
The displayed states are:
* **High Liquidity**
* **Medium Liquidity**
* **Low Liquidity**
These classifications are generated from the indicator's internal volume-ratio calculation and are provided as analytical reference values.
They do not represent a definitive measurement of market liquidity or capital flow.
## Volatility State
Volatility conditions are classified through an ATR-based comparison with its historical average.
The displayed states are:
* **Expanding**
* **Ranging**
* **Contracting**
These states represent the calculated volatility condition of the current data relative to the configured historical reference.
## Market Condition Classification
The framework includes internal classifications such as:
* **Accumulation**
* **Distribution**
* **Shakeout**
* **Normal**
These labels are generated from the indicator's defined combinations of relative volume, candle position, and candle-body conditions.
They are calculation-based analytical classifications and should not be interpreted as definitive identification of institutional activity or market intent.
## Session-Based Order Block Reference
The indicator provides visual reference areas associated with the currently identified market session.
Session labels include:
* **ASIAN**
* **LONDON**
* **NEWYORK**
The session identity is displayed together with the corresponding reference area.
The component is provided strictly for analytical reference. Displayed areas are generated by the indicator's internal calculation framework and do not represent confirmed, absolute, or universally valid classifications.
## Visual Analysis
The chart interface combines session information and calculated market conditions into a visual structure.
## Parameters
Different instruments, chart timeframes, session definitions, timezones, and parameter settings may produce different calculated results. The framework is therefore designed with configurable parameters rather than a single fixed configuration.
## Analytical Purpose
ATK / DEF — Multi-Session Volatility Dynamics is designed **solely for market observation and analysis**.
The indicator does not provide guince, or tra recommendations.
All displayed classifications, session references, measurements, and visual structures are generated from the indicator's internal calculation logic and the user's current parameter settings.
The displayed information is intended for analytical reference only.
**Market analysis only.**
אינדיקטור

אינדיקטור

Relative Volume Breakout Context [Pineify]Relative Volume Breakout Context
Overview
Relative Volume Breakout Context tests an intraday price escape against normal volume at the same exchange-session position, then tracks price acceptance as participation changes.
Problem Definition
Intraday volume has a time-of-day shape: opening, midday and closing bars do not share one natural activity level. A rolling average mixes those positions, making routine opening activity look exceptional or meaningful midday volume look ordinary. A fixed channel break adds price displacement but not time-adjusted participation. A one-bar marker also loses whether price later holds its boundary on sustained or fading volume.
Design Rationale
Each bar is assigned a slot by elapsed minutes from a session start, and volume is compared only with prior observations from that slot. Exponentially weighted statistics let old sessions lose influence, trading stability for responsiveness. A dispersion floor controls unstable Z scores. Price must close beyond a prior range by a minimum ATR fraction. The joint score uses a geometric mean so weak price or volume constrains the result; an additive score could hide that weakness. Freezing the crossed rail adds state, but preserves an auditable acceptance boundary after confirmation.
Key Features
Prior-only same-position volume expectation with sample reliability and a dispersion floor.
ATR-normalized breakout joined with volume surprise in one qualified event.
Frozen acceptance zone, one-shot decay alert, bounded labels and dashboard.
How It Works
Exchange-local bar time becomes elapsed session minutes. On 1-30 minute charts, elapsed time divided by chart interval selects one of 1,440 slots. Each stores a count, exponential volume mean and variance. The current bar reads them before updating, preventing self-inclusion.
After enough samples, dispersion is the larger of observed deviation and a percentage of expected volume. Volume Z is current minus expected volume divided by dispersion, capped at plus or minus five. Relative volume is the current/expected ratio; reliability rises with sample count.
Price rails are the highest high and lowest low of preceding bars. A fresh event closes beyond a rail, exceeds minimum ATR distance and meets volume Z. Volume and distance form a reliability-scaled geometric score with directional sign.
Confirmation freezes the rail. The frontier keeps the greatest high or lowest low while price remains outside. Z falling to the decay threshold creates one thinning alert. Closing through the rail invalidates tracking; age can expire it. Transitions require a completed bar.
How Multiple Indicators Work Together
Slot normalization asks whether participation is unusual now; the prior range asks whether price left an observed boundary; ATR standardizes escape depth; reliability limits warm-up confidence; memory tests later acceptance. Without volume this is a routine breakout, without price it is only RVOL, and without memory it cannot distinguish sustained support from thinning participation.
Trading Ideas and Insights
Treat confirmation as context, not an order. A green or red zone shows accepted extension from the frozen boundary. Amber means price still holds outside while same-position participation has decayed. That can frame questions about consolidation, fragility or absorption, but does not predict failure. Compare events with one instrument, session template and interval.
Unique Aspects
Common RVOL blends unrelated day parts, while common breakout tools stop at the crossing. Here, prior-only per-slot statistics feed a frozen-boundary state. Initiation requires time-adjusted participation and volatility-scaled displacement; continuation separates price acceptance from volume support. The thinning state remains descriptive rather than claiming lower follow-through volume causes reversal.
How to Use
Match session start and length to the regular exchange session and use a standard 1-30 minute chart. Let each slot collect the minimum samples; the dashboard shows WARMING before readiness. Faint lines are candidate rails. A diamond and RVOL label mark confirmation; the band spans frozen rail to frontier. Pane Z explains volume and signed score shows joint context. Set alerts to Once Per Bar Close.
Customization
Short memory adapts faster but is noisier; long memory is steadier but lags change. Minimum samples trades availability for depth. Raise the dispersion floor when quiet history overreacts. Range length and ATR distance control price selectivity; volume Z controls participation. Decay Z sets cooling and event age bounds observation.
Assumptions and Limitations
Bars must align with the configured exchange-local session. Holidays, half days, halts, extended-hours mixing and template errors reduce comparability. Bars use opening minute and may span session end. Missing volume disables scoring; tick volume is not centralized traded volume. Exponential statistics are path-dependent, capped Z is not probability, and ATR or rails lag. The script does not infer order intent, fills, profitability or next direction. Feed revisions and parameters can alter history. Values move intrabar; transitions and alerts commit at close.
Conclusion
This indicator replaces mixed-time RVOL with a session-position benchmark and extends a qualified breakout into an acceptance path. It reports escape, participation and thinning as context, not a forecast.
אינדיקטור

אינדיקטור

Agreed Upon DOLAGREED UPON DOL
Marks the unmitigated fair value gap that price is most likely to reach regardless of
which way the market resolves.
THE IDEA
Most targets require you to be right about direction. An agreed-upon draw on liquidity
does not. It is a gap positioned so that both outcomes route through it:
- if price continues, it runs straight through the gap on its way to the liquidity
beyond
- if price reverses, it must first rebalance the gap before it can deliver the
other way
Either branch touches it. That is what "agreed" means - both directions have agreed on
it. You are not betting on direction, you are collecting the level that gets hit either
way.
THE FOUR CONDITIONS
A gap is marked AGREED only when all four hold on its own timeframe:
1. it is an unmitigated fair value gap
Nothing else qualifies. Not session highs, not previous day levels, not
intermediate highs or lows. Only an untouched three-candle imbalance.
2. unswept liquidity exists BEYOND it, on its own side
The continuation branch needs somewhere to run to.
3. unswept liquidity exists on the OPPOSITE side of price
The reversal branch needs somewhere to run to.
4. the path to it is clear
Nothing between price and the gap - no unswept swing, no other unmitigated gap,
no session or daily level. If something sits in between, that nearer level is
where the market decides, so the far gap is no longer inevitable.
Miss condition 2 or 3 and only one branch exists, so you are back to betting on
direction. Miss condition 4 and the level is simply further away, not inevitable.
ON THE CHART
- a box around the agreed gap, labelled with the timeframe it came from
- dotted lines showing the liquidity pools the test is using
- "swept" tags wherever a pool is taken out
By default only the nearest agreed gap on each side is drawn. Turn on non-agreed gaps
to see what was rejected - the rejections tell you more about whether the logic matches
your read than the acceptances do.
THE PANEL
TF gaps agreed
15m 3 1
30m 2 0
1H 4 1
REASSESS POOL SWEPT
Per timeframe: how many unmitigated gaps are tracked, and how many currently qualify.
A red "!" next to a timeframe means it sits below your chart timeframe and has been
switched off.
The bottom row lights up when the map changes, because it goes stale as the session
runs:
TARGET HIT price reached the level you were pointing at
POOL SWEPT a liquidity pool was taken, so the conditions have shifted
MAP CHANGED a new candle printed a gap, or one was mitigated
New candles manufacture new gaps all session. A read taken at the open is stale within
the hour. Alerts are available for all three.
TIMEFRAMES
Analysis timeframes must be at or above your chart timeframe. request.security cannot
read down - it returns junk instead of erroring, so anything below the chart is disabled
outright and flagged in the panel.
Defaults are 15m / 30m / 1H, which means a 15m chart or lower. Each timeframe is
analysed self-contained: a 15m gap is judged against 15m swings, a 1H gap against 1H
swings. Results are identical on any chart below them, so you can sit on the 1m all
session and still be reading hourly structure.
WHAT THIS IS NOT
Not a bias tool. An agreed DOL has no direction by design - that is the whole point. It
tells you WHERE, never WHICH WAY.
Not an entry signal. It is a target. Two agreed gaps on opposite sides is not a
conflict, it is a range - wait to see which side fires, then trade toward what is left.
Not a filter for reachability. A gap 600 points away can satisfy all four conditions and
still be out of reach in a session. Judge distance yourself.
SETTINGS WORTH TOUCHING
Swing Left / Right defines what counts as a liquidity pool, so it drives
conditions 2, 3 and 4. Counted in bars of the analysis
timeframe, not your chart. If everything shows as agreed,
raise these first.
Require Clear Path condition 4. Turning it off will produce many more signals
and most of them will not be inevitable.
Session / Daily as
Obstacles the strictest part. An unswept London high anywhere in the
path kills the signal. Turn off first if it is too tight.
Only Nearest Each Side off shows every qualifying gap rather than just the closest.
אינדיקטור

Compression Clock (Axiom Multi-TF Adaptive)**Compression Clock (Axiom Multi-TF Adaptive) — Volatility Regime & State Age**
---
### **Description**
#### **Overview**
The **Compression Clock** is a non-directional volatility regime indicator based on the **Axiom quantitative research framework**. Instead of attempting to forecast market direction, it isolates the temporal dimension (**WHEN**) by measuring the duration and depth of volatility compression across any resolution.
Markets do not transition from quiet to expansion instantaneously; they exhibit a survival-rate decay where prolonged low-volatility states exponentially elevate the baseline probability of large physical displacement. The Compression Clock standardizes this process by normalizing rolling volatility and volume percentiles against a physical-time benchmark.
---
#### **Mathematical & Architectural Core**
1. **Dual-Feature Quiet Filter**:
* Evaluates rolling True Range ($\text{ATR}_{24}$) and Traded Volume ($\text{SMA}_{24}$) scaled against an intraday 24-hour physical window:
$$\text{ATR}_{\text{rolling}} = \text{SMA}(\text{TR}, N_{\text{bars}}), \quad \text{Vol}_{\text{rolling}} = \text{SMA}(\text{Volume}, N_{\text{bars}})$$
* Computes the rolling percentile rank of both features across a rolling 180-day baseline distribution.
* A bar qualifies as **Quiet** if and only if both features sit simultaneously in the lower tercile:
$$\text{Quiet}_t = \mathbb{I}\left(\text{Rank}(\text{ATR}_t) \le 33.33\%\right) \land \mathbb{I}\left(\text{Rank}(\text{Vol}_t) \le 33.33\%\right)$$
2. **Physical-Time Normalization**:
* TradingView indicators often suffer from timescale distortion when hardcoding bar-based periods across multiple resolutions.
* This script dynamically translates resolution minutes ($M_{\text{tf}}$) into actual **physical hours**. Whether applied to a 5-minute, 30-minute, or 4-hour chart, the Y-axis consistently represents **elapsed physical hours of continuous compression**.
3. **Regime State Categorization**:
* **S0 (ACTIVE)**: Market is expanding or fluctuating outside the quiet threshold. Compression age resets to 0.
* **S1 (QUIET, < 24 Hours)**: Early-stage compression. Natural volatility dampening without statistical hazard elevation.
* **S2 (MATURE, 24 – 72 Hours)**: Statistically mature compression. Historical survival analysis indicates a significant elevation in large-displacement probability.
* **S3 (DEEP, > 72 Hours)**: Extreme volatility exhaustion. Persistent absence of dispersion indicating imminent volatility expansion.
---
#### **How to Use (Methodological Discipline)**
* **Decoupled Architecture**:
* The Clock dictates **WHEN** (volatility environment), not **WHAT** (direction) or **HOW** (execution).
* Never treat an S2/S3 state as a directional trade signal. A compression state is directionally agnostic—it warns of imminent displacement hazard, but the direction must be governed by external momentum or structural acceptance/rejection models.
* **Multi-Timeframe Scope**:
* Low-scale compression (e.g., 5m/15m entering S3) reflects localized intraday order book exhaustion. It does **not** override a higher-timeframe S0 state. For macro regime filtering, monitor higher physical resolutions (such as 4H).
* **Buffer Safety**:
* Includes a built-in 4,900-bar memory clamp to prevent buffer overflow exceptions on ultra-low timeframes while maintaining valid causal percentile rankings.
---
#### **Inputs**
* **Rolling Feature Duration (Hours)**: Physical length of the short-term smoothing window (Default: 24h).
* **Lookback Days (Days)**: Historical distribution window for empirical percentile rankings (Default: 180 days).
* **Quantile Rank Threshold (%)**: Cutoff for the quiet regime (Default: 33.333% — bottom tercile). אינדיקטור

Pine Script Utility Library [1CG]Pine Script Utilities
Building a Pine script often means writing the same supporting code again: setting up timezone choices, converting prices to ticks or pips, updating chart drawings, or working out which candles belong to a trading session.
Pine Script Utilities brings these everyday tasks into one reusable toolbox. Its purpose is to help script authors spend more time on what makes their indicator useful and less time rebuilding common tools.
This is a library for Pine Script v6. You use it inside your own indicator or strategy; adding the library alone does not produce a chart display. You can use a single helper or combine several parts of the library as your script grows.
Consistent choices for your settings
Give users familiar choices without recreating the same lists in every script. The library supplies reusable options for:
Timezones, including the symbol's exchange timezone.
Hours, minutes, quarter-hour times and common durations.
Line styles, thickness, extension direction and label styles.
Text size and horizontal or vertical alignment.
Session presets and the starting points for session high and low lines.
It also turns these selections into the values Pine needs to use them. Your script still decides which settings to offer and how to arrange them.
Time and timezone tools
Work with clock times, session schedules and chart timing without repeatedly writing the conversion code yourself. Helpers let you build and read time values, convert between clock times and minutes, calculate durations, check session membership and limit processing to a chosen history window.
For example, you can define a session in New York time even when the symbol uses a different exchange timezone. Named timezones allow session boundaries to follow local daylight-saving changes. Overnight schedules are supported, so a session can start in the afternoon and finish the following morning.
Everyday price and quantity conversions
Use the same conversion tools across different scripts:
Convert a price movement into ticks or pips, or convert those distances back into price.
Override the pip size when a broker's price feed needs a different convention.
Read the symbol's price precision, tick value and asset category.
Round quantities down to a chosen increment.
Calculate a position's notional value from quantity, price and the symbol's point value.
For example, a candle-range display could show its size in ticks instead of a raw price difference. These are general conversions; account-risk sizing and risk/reward calculations belong in a separate risk library.
Easier drawing maintenance
Once your script has created a drawing, the library can help keep it up to date. Change the position, appearance or text of lines, labels and boxes, and update existing table cells. Supply the properties you want to change and leave the others as they are.
Cleanup helpers remove groups of lines, labels, boxes or connected-line drawings called polylines. You can also keep a line collection within a chosen size and turn lists of times and prices into points for chart drawings. This gives scripts a common way to manage their chart objects as new data arrives.
Session tracking beyond simple clock checks
For scripts that need session ranges, the library can track the opening price, high, low and latest closing price, along with the times of the highs and lows. Use a preset schedule or define your own, track multiple sessions separately, and retrieve the current session or earlier completed sessions.
It also handles several details that can otherwise produce confusing chart results:
A session can start or finish partway through a candle. Where needed, available one-minute data helps exclude prices from outside the session. For example, a 09:10 start on a 15-minute chart should not include the earlier prices from the 09:00 candle.
Session prices and displayed line lengths stay separate. You can collect prices until noon and keep the resulting levels visible later without changing the session's high or low.
High and low lines can start from the session opening, the session end, or the time each extreme occurred.
When trading reopens after a long closure, eligible line endpoints can carry forward across the missed days. An overnight session interrupted by the closure can resume as the same session, preserving its earlier prices.
Stored sessions can be kept by record count, so a script can retain actual observations instead of treating empty weekend dates as trading sessions.
The session tools use ordinary chart candles where those candles are sufficient. They can request one-minute data for candles that contain a session boundary, and several sessions can share that data.
Building blocks for your own indicators
You could use these tools for a session-range overlay, a candle-size display, a dashboard with consistent text and styles, or an indicator that marks a chosen time window. Time-window helpers provide the opening and closing times and help your script decide when to draw the window.
The companion session example demonstrates how these pieces fit together. It keeps a chosen number of session records, draws the retained history, and updates the current session as prices arrive. Its complete appearance and additional features are choices made in the example; you can build a different display using the same utilities.
Getting started
Import the library into a Pine v6 script and start with the helpers you need. Simple conversions and drawing helpers can be used independently. Session tracking needs a little more setup because your script keeps the session records and decides how to display them. The full guide explains that workflow, while the API reference lists the available functions and their arguments.
A few things to know
Session tracking is intended for standard intraday time-based charts. Its one-minute boundary checks apply to chart timeframes above one minute.
Custom session tracking uses one start and end time, such as 1600-0400. Presets describe regular clock schedules, not complete holiday or lunch-break calendars.
Weekend and closure adjustments happen when reopening data arrives. The library does not predict future market closures.
Accurate ranges depend on available price history. If required one-minute data is missing, the library does not replace it with a whole candle that could contain out-of-session prices; the resulting range may be incomplete.
Pip sizes, quantity increments and contract values can differ between feeds and instruments. Use the appropriate values for your symbol.
Your script controls its drawings, alerts and history limits. TradingView's data and drawing limits still apply.
ספרייה

SPY Position Helper v1adjusted chart view to show more data on 1m timeframeSPY Position Helper v1
SPY Position Helper v1 is a multi-timeframe technical analysis indicator that combines trend, market structure, momentum, and volatility measurements into a rules-based confluence model.
The indicator continuously calculates:
4-hour trend direction using the 200-period Exponential Moving Average (EMA)
1-hour structural highs and lows
Previous day's High, Low, and Close
Average True Range (ATR)
200 EMA
VWAP
Relative Strength Index (RSI)
MACD
Directional Movement Index (+DI / -DI)
Average Directional Index (ADX)
Confirmed swing highs and swing lows using pivot detection
Support and resistance are dynamically derived from the nearest confirmed structural references, including swing pivots, higher-timeframe levels, previous-day levels, VWAP, and the 200 EMA. These levels are converted into adaptive zones whose width is based on current ATR, allowing the zones to expand and contract with changing market volatility.
The indicator evaluates completed candles for breakout and rejection behavior, directional momentum, candle body strength, trend participation, and available structural room relative to calculated risk. ATR-adjusted stop distances and structural targets are calculated to estimate available reward versus risk for each qualifying setup.
Each potential setup is evaluated using a weighted 10-point confluence model consisting of:
Higher-timeframe trend alignment
Structural location
EMA/VWAP confluence
RSI position
MACD confirmation
ADX trend strength
Candle confirmation
Structural reward-to-risk evaluation
Signals are produced only when all required conditions are met and the calculated confluence score satisfies the user-defined minimum threshold.
When a signal is active, the indicator calculates reference entry, stop, and target levels, monitors predefined exit conditions, and displays market context through dynamic chart overlays and an informational dashboard.
Disclaimer
This indicator is intended solely as a technical analysis and decision-support tool. It does not predict future market movements, guarantee profitable trades, or provide certainty regarding market direction. All trading involves risk, and no indicator can eliminate uncertainty or secure profits. Users should exercise independent judgment and apply appropriate risk management before making any trading decisions. אינדיקטור

אינדיקטור

DB Seasonal by Date RangeAbout This Script
This script/indicator was written in the following manner: 'I supplied logic steps through AI prompts and AI did the heavy lifting of code production. I am not a code writer by any standard at all compared to those who freely share their work with the rest of us. I have taken some Pascal classes in college, but never used coding in my career. I would like to thank all code writers who have advanced and shared their tools with the public.'
This description was drafted by Claude Opus 4.5 (Anthropic) as part of the collaborative development process.
What This Indicator Does
DB Seasonal By Date Range analyzes historical price performance within user-defined calendar periods. Set a start month/day and end month/day, and the indicator calculates returns for that window across multiple years—helping you identify recurring seasonal patterns in any asset.
Key Features
📊 Two Information Tables:
Detail Table (Top Left): Year-by-year returns for your specified lookback period (adjustable, default 10 years)
ALL DATA Table (Bottom Right): Summary statistics across all available TradingView history (up to 50 years)
📈 Statistics Provided:
Return % per year
Cumulative total return
Average return
Win rate (% positive years)
Maximum gain/loss
🎨 Visual Highlighting:
Selected date range appears as a shaded overlay on the price chart
⚙️ Customization:
Adjustable lookback period (1-20 years)
Maximum years to analyze (10-100)
Table text size (Tiny/Small/Normal/Large)
Highlight color
How It Handles Holidays & Weekends
The indicator works with actual trading data only. TradingView charts contain no bars for holidays or weekends, so:
Scenario What Happens
Start date = Holiday Uses first available trading day after
End date = Holiday Uses last available trading day before
Holiday within range Simply skipped (no bar exists)
Export as CSV
No manual adjustment needed—returns reflect real market performance during open sessions.
Cross-Year Ranges
You can study periods spanning two calendar years (e.g., November 1 → January 31 for "holiday rally" analysis). When end month < start month, the code automatically extends the end date into the following year. Seasons are labeled by the start year (e.g., Nov 2025 → Jan 2026 = "2025").
Data Anomalies to Watch For
If the ALL DATA table shows unexpected year counts, check the asset's history for:
Privatization periods (e.g., DELL was private 2013-2018)
Ticker changes (e.g., FB → META)
Spin-offs or mergers
Recent IPOs with limited history
The indicator accurately reflects available trading data—gaps in corporate history will appear as fewer years analyzed.
How to Use
Set your Start Month/Day and End Month/Day
Adjust Lookback Years for the detail table
Apply to any chart—the shaded area highlights your seasonal window
Compare year-by-year returns and long-term statistics
Use on different symbols to find assets with consistent seasonal behavior
Example Use Cases
Turn-of-Month Effect: Study last/first trading days of each month
Holiday Rallies: November through January performance
Earnings Seasons: Quarterly patterns around reporting periods
Sector Rotation: Compare seasonal trends across sector ETFs
Disclaimer
This indicator is for educational and informational purposes only. Past seasonal performance does not guarantee future results. Always conduct your own research before making trading decisions.
Acknowledgments
Logic & Concept: dbb
Code Production: Claude Opus 4.5 (Anthropic AI)
Description: Claude Opus 4.5 (Anthropic AI)
Inspiration: The generous TradingView community members who share their work freely
Questions or feedback? Leave a comment below! אינדיקטור

Adaptive Market Volume_Forex_more### Adaptive Market Volume – Forex & Gold
**Adaptive Market Volume** was designed to make volume/activity analysis more useful in markets where the volume displayed by the instrument does not necessarily represent the entire market, such as Forex, Gold, and index CFDs.
In decentralized markets such as Forex, the indicator **does not attempt to convert tick volume into true global volume**. Instead, it uses related centralized futures markets as institutional activity proxies. Each data source is normalized independently and, when available, combined with the instrument's local activity through a **Hybrid model**, producing a relative measure of market participation.
For example, **GBPUSD uses British Pound futures (6B)** as a reference, **EURUSD uses Euro futures (6E)**, and **XAUUSD uses Gold futures (GC)**. Supported index and energy CFDs use their corresponding futures markets as activity proxies as well.
The indicator also applies time-based normalization to reduce distortions caused by different trading sessions and typical intraday volume patterns.
Additional analysis modes include **Relative Momentum, Cumulative Effort, Efficiency, Micro Z-Score, and Micro Contrast**. Micro Contrast is especially useful on lower timeframes such as M1–M5, making differences between low, medium, and high activity easier to visualize without changing the underlying Adaptive Volume calculation.
**Recommended markets:**
**Forex:** EURUSD, GBPUSD, AUDUSD, NZDUSD, USDJPY, USDCHF, and USDCAD.
**Gold:** XAUUSD.
**Supported Indices:** Nasdaq 100, S&P 500, Dow Jones, Russell 2000, Nikkei 225, Hang Seng, DAX, and BRA50/Ibovespa when recognized through supported ticker aliases.
**Energy:** WTI Crude Oil and Natural Gas on supported symbols.
**Crypto, stocks, and futures:** use the native volume available from the instrument's own market/data feed.
**Important:** Adaptive Market Volume represents **relative market activity, not absolute global volume**. Results on Forex and CFDs depend on the availability and quality of both the local data feed and the corresponding futures proxy. Forex crosses without a direct proxy—such as EURJPY, AUDJPY, EURCHF, CADJPY, and CHFJPY—can still be used, but rely primarily on local activity and therefore do not have the same Adaptive coverage as the recommended Forex pairs.
אינדיקטור

DeltaLabs - Equal Highs / Equal LowsDeltaLabs - Equal Highs / Equal Lows is a price action indicator designed to identify active Equal Highs (EQH) and Equal Lows (EQL) directly on the current chart timeframe.
The indicator focuses on repeated structural price levels that may represent resting liquidity. It uses candle bodies only, ignoring wick extensions when identifying equal levels.
For swing highs:
Body High = max(Open, Close)
For swing lows:
Body Low = min(Open, Close)
When two confirmed swing highs occur within the configured tolerance, the indicator creates an Equal High (EQH).
When two confirmed swing lows occur within the configured tolerance, it creates an Equal Low (EQL).
Additional touches are grouped into the same level and displayed as EQH ×2, EQH ×3, EQL ×2, and so on.
The indicator only keeps active liquidity levels on the chart. If an Equal High is violated by the candle body to the upside, it is removed. If an Equal Low is violated by the candle body to the downside, it is removed. Wicks alone do not invalidate the level.
DeltaLabs - Equal Highs / Equal Lows automatically recalculates based on the timeframe currently selected on the chart. A 15-minute chart detects 15-minute structure, a 1-hour chart detects hourly structure, and a 4-hour chart detects 4-hour structure. There is no fixed internal timeframe.
To keep higher-timeframe charts clean, the indicator includes a configurable history window. By default, it analyzes the last 30 days, but users can define a custom number of days.
A separate maximum gap between equal touches setting controls how far apart two matching swing points can occur and still belong to the same EQH or EQL. This can be measured in either days or bars.
Because markets rarely create two swing points at the exact same price, the indicator uses an ATR-based equality tolerance. This allows the detection threshold to adapt to the volatility of the current instrument and timeframe. Lower values create stricter matching, while higher values allow slightly more variation.
Swing sensitivity can also be adjusted using the Swing Left Bars and Swing Right Bars settings. Lower values detect smaller and more frequent structures, while higher values focus on more significant swing points.
Visual settings include separate colors for EQH and EQL, independent label colors, configurable line width, and solid, dashed, or dotted line styles.
Typical use cases include liquidity mapping, price action analysis, sweep identification, structural targets, breakout context, range analysis, and manual trade planning.
An EQH or EQL is not automatically a buy or sell signal. The indicator is designed to highlight repeated structural price levels that may be relevant to future price action.
The goal of DeltaLabs - Equal Highs / Equal Lows is simple:
Keep the chart clean and automatically highlight currently relevant, body-based Equal Highs and Equal Lows.
No old violated levels.
No wick-based noise.
No fixed timeframe.
Just active price action structure on the timeframe being analyzed.
For educational and analytical purposes only. Not financial advice. אינדיקטור

Session Fibs | Falcon AIAuto-draws Fibonacci retracement levels across a trading session's range, anchored to that session's own high and low.
Pick a session window and the script anchors the fib to it, then projects the 0 / 23.6 / 38.2 / 50 / 61.8 / 78.6 / 100% levels, with optional 127.2 and 161.8% extensions.
Two modes. Previous session (the default) fibs the range that has just COMPLETED and projects those levels onto the session now trading, giving you stable references that do not move under you. Current session anchors live to the developing high and low, so the levels update as the range extends. That is useful for watching a session build, but the levels shift intraday. Knowing which of the two you are looking at matters more than the ratios themselves: one is fixed, one is not.
How to read it: the 38.2 / 50 / 61.8% band holds the common pullback zones inside a range, and the 61.8-78.6% area is the classic deep retrace. Extensions are common measured-move targets beyond the range. Reference levels, not signals.
Settings: session window and timezone, previous or current session, flip the 0% and 100% ends, extensions on/off, line width and colours, shade the 61.8-78.6% zone, labels.
Session logic needs an intraday chart. The default window is the standard US index cash session; change it to whatever market you trade.
This script does NOT place trades, does NOT backtest, and contains no entry, stop, or position-sizing logic. It is pure geometry off one session's high and low, with no trend model, pattern model or scoring. Your entry, your risk.
Educational tool only. Not financial advice. Fib levels are reference points, not predictions. אינדיקטור

Risk & Position-Size Calculator | Falcon AIWorks out how many contracts to trade so that being stopped out costs the dollar amount you actually chose to risk.
Enter your account size and risk percentage, set the stop as either a manual point distance or an ATR multiple, and the script returns the contract count. It auto-detects the point value of the symbol you are on, so you are not hand-converting ticks to dollars or mixing up micro and full-size contract multipliers, which is where most sizing mistakes come from.
It also shows a guardrail panel for anyone trading a funded or evaluation account: how many consecutive losing trades at your current size before you hit the daily-loss limit, and how many before a trailing drawdown is breached. Those two numbers are usually the difference between a plan that survives a bad day and one that does not.
Settings: account size, risk per trade (%), stop mode (manual points or ATR-based), ATR length and multiple, max daily loss, trailing drawdown, panel position, text size, accent colour, optional prior-day high/low levels.
This script does NOT place trades, does NOT backtest, and contains no entry or exit logic. It is a calculator that reads your inputs and does the arithmetic. Your entry, your risk.
Educational tool only. Not financial advice. Correct position sizing does not prevent losses, it only makes the size of them deliberate. אינדיקטור

RVOL Candles | Falcon AITints each candle by its relative volume, measured against the average volume for that SAME TIME OF DAY over a rolling window of prior sessions.
That is the part that makes it different from a plain volume average. Intraday volume is seasonal: heavy at the open and into the close, thin around midday. Compare a 10:00 bar against a flat all-day average and every open looks like a spike, because the average is dragged down by the quiet hours. Compare that 10:00 bar only against previous 10:00 bars and you get a like-for-like read, so a genuine surge stands out and a busy-looking open that is merely normal does not.
Candles are shaded across four tiers: below-elevated, Elevated, High and Extreme, each a configurable multiple of that time-slot average. Extreme bars can also carry a marker and an optional RVOL value label.
On daily and higher timeframes there is no time-of-day seasonality to correct for, so the script falls back to a simple rolling volume average.
Settings: lookback in sessions, the three tier multiples, recolor-everything or only-elevated, colours, extreme marker on/off, value label on/off, watermark position.
Notes on honesty: the current forming bar is never pushed into the historical average, so the reading does not contaminate its own baseline. Volume quality depends on your data feed, and symbols with no volume data show no tint.
This script does NOT place trades, does NOT backtest, and contains no entry, stop, target or position-sizing logic. It is a volume study and nothing more. Your entry, your risk.
Educational tool only. Not financial advice. High volume on its own is not a signal. אינדיקטור

אינדיקטור

Pivot Points | Falcon AIDraws Classic and Camarilla pivot levels from the previous period's high, low and close, on a daily or weekly anchor.
Classic pivots give you the central pivot plus three supports and three resistances, derived from the standard published formula. Camarilla uses a tighter multiplier set, so its levels sit closer to price and are read differently: the inner pair as mean-reversion boundaries, the outer pair as breakout markers. Both are drawn from the same prior-period data, so you can see where the two frameworks agree or disagree on a given day.
Levels are drawn as extended lines with optional labels and refresh automatically when a new period begins. You can show either set on its own or both together, and switch the anchor between daily and weekly. Only the current period extends to the right and carries labels, so the chart stays readable as history builds.
Settings: pivot period (Daily / Weekly), method (Classic / Camarilla / Both), include current unclosed period on or off, how many R/S pairs to show, periods of history to keep drawn, colours, widths, label side, info panel.
A note on repainting: by default the levels come from the last CLOSED period and stay fixed all session. Turning on "Include current (unclosed) period" deliberately opts into levels that move as the period develops.
This script does NOT place trades, does NOT backtest, and contains no entry, stop, or position-sizing logic. It draws reference levels and nothing more. Your entry, your risk.
Educational tool only. Not financial advice and not a recommendation to buy or sell. Past price behaviour around any level does not predict future behaviour. אינדיקטור

TP/SL Signals💀 TP/SL Signals & Strategy: Automated Risk Management Tool
⚠️ IMPORTANT: Don't forget to BOOST 🚀 (Like) and FOLLOW for more institutional-grade, open-source Pine Script scripts! Your support keeps this project active and updated!
📌 Overview
💀 TP/SL Signals is a powerful multi-timeframe trading system built to resolve the biggest trader challenge: Discipline and Risk Management.
By filtering price noise with Hull Moving Averages (HMA) across multiple timeframes, this tool identifies key trend pivots and automatically projects your entry, stop-loss, and multi-tier take-profit targets directly onto your chart.
✨ Key Features
🎯 Dynamic Entry Signals: Built on real-time cross-over logic using fast and slow HTF Hull Moving Averages.
🛡️ Automated Risk/Reward Levels: Visualizes exact SL, TP1, and TP2 target lines as soon as a trade opens.
⚖️ Trailing Breakeven: Automatically moves your Stop Loss to the entry price once TP1 is reached to secure a risk-free trade.
📊 Fully Customizable Risk Controls: Adjust percentages for SL, TP1, and TP2 dynamically in settings.
🔔 Instant Alerts: Built-in webhooks & alert conditions for instant Long/Short entry push notifications.
⚙️ How It Works
Trend Identification: The script fetches high-timeframe trend momentum using calibrated 5-minute and 15-minute HMA lines.
Execution Signals:
LONG 🟢: Triggered when 5m HMA crosses above the 15m HMA.
SHORT 🔴: Triggered when 5m HMA crosses below the 15m HMA.
Automated Exit Logic:
Reaching TP1 locks in partial profits and adjusts the stop loss to Breakeven.
Final exit triggers when TP2 is reached or trailing SL is hit.
🛠️ Recommended Setup
Timeframe: 1m, 5m, or 15m charts.
Assets: Crypto (BTC, ETH), Forex Majors, Stocks, or Indices.
Risk Management: Default is set to 1.0% SL, 1.0% TP1, 2.0% TP2. Tune these in the settings menu based on market volatility.
💡 Backtesting & Open Source
This indicator is 100% open-source and completely free to use. Test different parameter setups on historical data to fine-tune win rates for your favorite pairs.
🤝 Join the Community!
If this indicator helps you manage risk better or boosts your win rate:
Hit the Rocket Button 🚀 to boost this post!
Click Follow to never miss future indicator upgrades, strategy updates, and trading scripts.
Drop a comment below with your favorite assets to trade using this system!
Disclaimer: Past performance is not indicative of future results. Always practice proper risk management. אינדיקטור

Cipher B Adaptive v6Cipher B — Adaptive v6
Cipher B — Adaptive is a WaveTrend-style momentum oscillator that re-tunes itself to the coin it is applied to. The same script gives usable overbought/oversold levels and cross signals on BTC daily, a mid-cap alt on 4H or a meme coin on 5 minutes, without changing the settings.
WHY THIS EXISTS
Classic Cipher B oscillators use fixed levels (±53 / ±60) and fixed smoothing (10 / 21). Those numbers were tuned for BTC-like behaviour. On a meme coin the wave regularly runs to ±90, so "overbought" fires far too early and a cross at -55 is not really a dip. On BTC on higher timeframes the wave rarely reaches ±60, so the extreme zones are almost never touched. This script solves that with two independent adaptive layers.
HOW IT WORKS
1. Asset profile (volatility tier)
The script measures annualised realised volatility: the standard deviation of log returns over the lookback, scaled by the number of bars per year for the chart timeframe. Because it is annualised, a 5-minute chart and a daily chart are compared on the same scale. The result is mapped to a 0…1 factor between two thresholds:
• below 75% = Large Cap (BTC / ETH behaviour)
• 75% to 150% = Alt
• above 150% = Meme
The factor stretches the Channel and Average lengths by up to 30% on the noisiest coins, which suppresses whipsaw crosses without adding lag on calm charts. If you disagree with the detection, the Profile input overrides it.
2. Adaptive levels
In Adaptive mode the outer OB/OS levels are the 95th and 5th percentile of WT1 over the last 300 bars, clamped between 40 and 95. The inner levels are the outer level × 0.88, which preserves the original 53/60 geometry. Levels are asymmetric by default: in an uptrend the oversold line sits shallower, so dip signals fire where dips actually end, and the overbought line sits deeper. Turn on Symmetric levels if you prefer mirrored lines. Fixed mode keeps your manual levels and widens them by the profile, up to 35% on meme-tier coins.
3. Waves and money flow
WT1 (blue) and WT2 (dark blue) are the standard WaveTrend pair. The cloud between them is green while momentum is bullish and red while it is bearish; the histogram shows the same distance. The green/red money-flow wave is the Cipher B style RSI-MFI hybrid: sustained green means buying pressure behind the move.
4. Divergence
Pivots are found on the oscillator, not on price. Price is read in the window around each pivot, and a divergence is confirmed once, when the second pivot is confirmed. Markers are drawn on the actual pivot bar and the two pivots are connected with a line. Optional filters: at least one pivot must be inside the OB/OS zone, and the pivots must be within a set number of bars of each other. Hidden (trend-continuation) divergences can be switched on separately.
HOW TO READ THE SIGNALS
• Dim dot: WT1 crosses WT2 in the mid-range. Informational only.
• Solid green / red dot: a cross inside the oversold / overbought zone. This is the classic Cipher B buy / sell dot.
• Gold / orange diamond (STRONG): a zone cross that is either beyond the extreme level or follows a divergence within the last 20 bars.
• Triangle marked DIV: regular divergence. Small triangle marked H: hidden divergence.
• Shaded background: WT1 is beyond the extreme levels.
INFO TABLE
The table shows the detected profile (auto or manual), annualised volatility, the lengths and levels currently in use, WT1 / WT2, zone, momentum and money-flow direction. If a signal looks off on a particular coin, this is where you check what the script decided.
SETTINGS WORTH KNOWING
• Profile: Auto / Large Cap / Alt / Meme.
• Large-cap vol ceiling and Meme vol floor: the tier thresholds. Raise them on very low timeframes if BTC keeps being classed as Alt.
• Max length stretch: set to 0 to disable smoothing adaptation.
• Level mode, Adaptive lookback, Extreme percentile: how the levels are derived. A lower percentile (for example 90) gives more signals.
• Divergence memory: how long a divergence keeps upgrading zone crosses to STRONG.
ALERTS
Ten alert conditions: any cross, zone cross, STRONG signal, regular divergence and hidden divergence, each for both directions.
NOTES
• The first 300 bars of a chart use the fixed levels until enough history exists for the percentile.
• The volatility thresholds and the 365-day annualisation are tuned for crypto. On stocks or forex the profile reads differently; use the Profile override there.
• Cross signals confirm on bar close. Divergence signals confirm a few bars after the pivot (Pivot length), as with any pivot-based method. Nothing is recalculated on past bars after that.
CREDITS
Built on the WaveTrend oscillator by LazyBear and the Cipher B concept popularised by Market Cipher and VuManChu's open-source Cipher B. The volatility profile, percentile levels, tiered signals and pivot-aligned divergence logic are original to this script.
This indicator is an analysis tool, not financial advice. Test it on your own markets and timeframes before relying on it. אינדיקטור

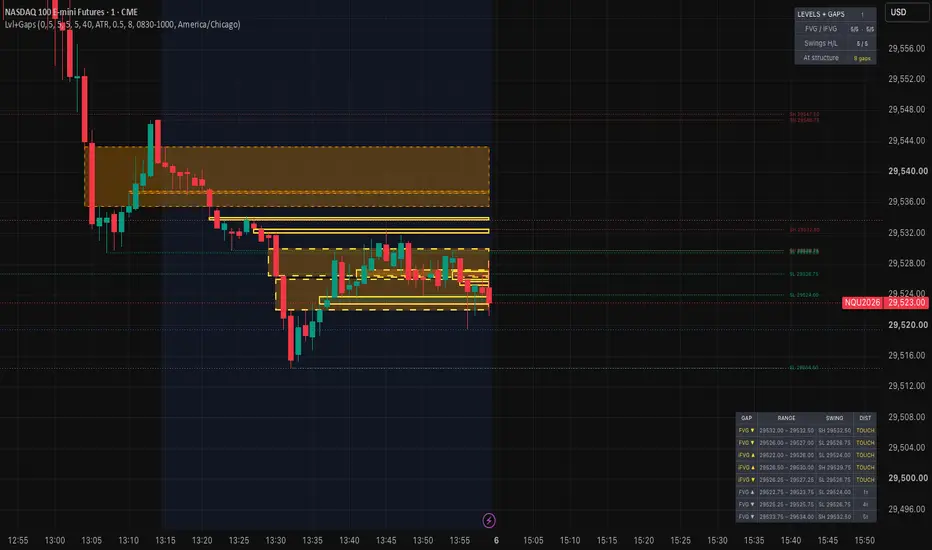
SMT + iFVG Confluence Tool | Dominion ToolsLevels + Gaps
What it does
Marks two things on the chart and shows you where they overlap.
Fair value gaps. A three-candle imbalance where the first and third candles don't overlap. Bullish gaps are drawn from the first candle's high to the third candle's low; bearish gaps are the inverse. The most recent five are kept as active zones, extending right until price interacts with them.
Inverted gaps (iFVG). When a bar closes fully through a gap, the zone doesn't disappear — it flips. A bullish gap closed through to the downside becomes potential resistance; a bearish gap closed through to the upside becomes potential support. Inverted zones move into a separate pool of the last five, so a fresh burst of new gaps won't push an important inverted level off the chart.
Swing levels. The last five confirmed pivot highs and five pivot lows on your current timeframe, drawn as extending rays with price labels.
Gap-at-structure highlighting. Every zone is measured against every swing level. Any gap sitting within your proximity threshold gets a bright border, and a table lists them sorted nearest first — zone type and direction, its price range, which swing it's near, and the distance in ticks. TOUCH means the level runs through the zone.
Why the two are combined
Gap tools and structure tools are common separately. Reading them together usually means eyeballing whether a zone happens to sit on a level. This does that measurement for you and ranks the results, so overlap is something you can see rather than estimate. The separate active/inverted pools exist for the same reason: on lower timeframes gaps form fast, and a single combined list will bury an inverted zone under new ones within minutes.
How to use it
Add to any chart and any timeframe. Everything scales to the instrument automatically.
Set the swing pivot length for the structure you care about — lower values catch more swings, higher values give cleaner levels. Set the proximity threshold in ATR multiples if you switch timeframes often, or in ticks for a fixed measurement on one instrument. Around 0.5 ATR is generous and most nearby zones will highlight; drop toward 0.2 for genuine overlaps only.
Raise the minimum gap size if a fast chart gets cluttered. Adjust how many zones and levels to keep if five isn't right for your workflow.
Optional session shading is included for anyone who wants a visual reminder of a specific window. It's off by default and filters nothing.
Alerts
Four available: gap inverted upward, gap inverted downward, swing high confirmed, swing low confirmed.
Settings
Gap detection: minimum size in ticks, active count, inverted count, colors
Swing levels: pivot length, count kept per side, price labels, ray length, colors
Proximity: ATR multiple or fixed ticks, highlight color, table on/off
Display: status panel, session shading with timezone, confirmed-bars mode
Repainting
Confirmed-bars mode is on by default: zones and levels commit only when a bar closes. Turn it off and you'll see them form earlier, with the tradeoff that an unconfirmed zone can vanish before the bar completes. No higher-timeframe data requests, so there's no request.security lookahead concern.
Pivots confirm after the fact by design. With a length of 5, a swing level appears five bars after the actual high or low. That delay is inherent to pivot detection, not a flaw — but it means levels draw later than the price reaction that created them.
Notes
This is a visualization tool. It draws zones and levels and measures the distance between them. It doesn't produce entries, exits, targets, or directional bias, and the highlighting indicates proximity only, not quality or probability. Nothing here should be read as a trade recommendation. Test any approach thoroughly before risking capital. אינדיקטור