
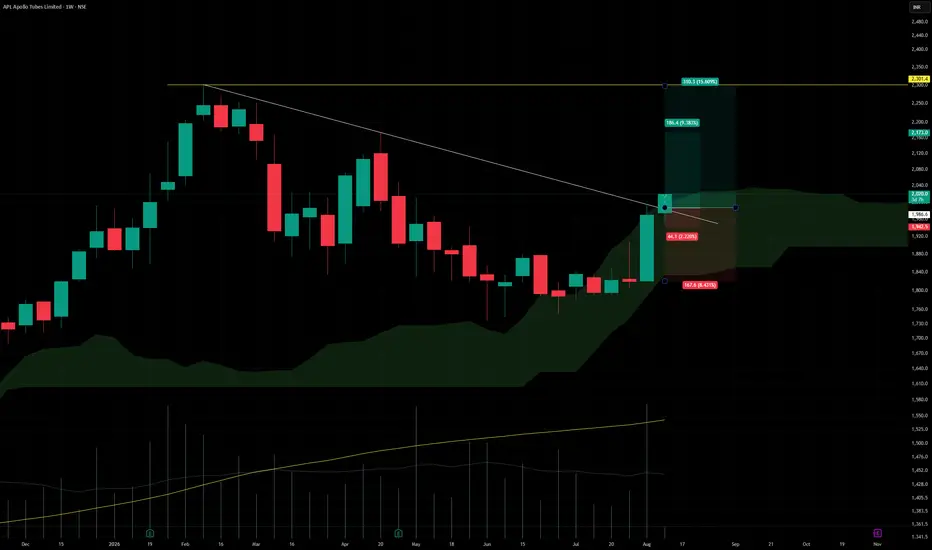
APL Apollo Tubes Ltd. (CMP ₹2,020.00, NSE: APLAPOLLO)
The SmartWay Research Desk | 11 August 2026
A New Delhi‑based steel tubes and structural products manufacturer, incorporated in 1986. APL Apollo is India’s largest producer of structural steel tubes, hollow sections, and value‑added steel products, serving construction, infrastructure, automotive, and industrial sectors.
Promoter Holding (Mar 2026): Sanjay Gupta Family — 29.3% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹22,842 Cr vs ₹20,412 Cr in FY25 (+11.9% YoY). → Good
Net Profit: FY26 PAT ₹1,812 Cr vs ₹1,612 Cr in FY25 (+12.4% YoY). → Good
Operating Margin: FY26 EBITDA ₹3,212 Cr, margin 14.1% vs 13.6% last year (+50 bps). → Good
Equity Capital: Stable, face value ₹2. → Good
Dividend Policy: Dividend ₹8.00/share declared for FY26. → Good
Asset Building: Investments in Raipur plant expansion and value‑added products. → Good
Sales: Strong demand from construction and infra projects. → Good
Expense: Raw material cost pressures (steel, energy) remain. → Neutral/Good
EPS: FY26 EPS ₹60.25 vs ₹53.60 last year (+12.4%). → Good
Institutional Interest & Ownership Trends (Mar 2026)
Promoter Holding: 29.3% (no pledges)
FII Holding: 22.12%
DII Holding: 34.34%
Retail & Others: 14.24%
Strategic Moves & Innovations
Expansion in Raipur mega plant (capacity 4 MTPA).
Focus on value‑added structural steel products.
Partnerships with infra developers and government projects.
Diversification into exports and premium hollow sections.
Cash Flow & Balance Sheet Strength
Market cap ~₹56,800 Cr.
Debt‑to‑equity ratio ~0.42 (moderate leverage).
Book value per share ₹412.00; P/B ~4.9.
EPS (TTM) ₹60.25; P/E ~33.5.
Risk Factors
Moderate P/E ratio ~33.5, valuations expensive.
Dependence on construction and infra demand cycles.
Exposure to commodity price volatility (steel, energy).
Competition from Tata Steel, JSW Steel, and Jindal Steel.
Investor Takeaway
APL Apollo has delivered steady FY26 performance, supported by infra demand, Raipur expansion, and value‑added steel products. With promoter backing, dividend payouts, and leadership in structural steel tubes, APL Apollo remains a large‑cap infra‑linked steel play. At CMP ₹2,020.00, valuations are expensive (P/E ~33.5, P/B ~4.9), reflecting growth expectations but also sectoral risks.
The SmartWay Research Desk | 11 August 2026
A New Delhi‑based steel tubes and structural products manufacturer, incorporated in 1986. APL Apollo is India’s largest producer of structural steel tubes, hollow sections, and value‑added steel products, serving construction, infrastructure, automotive, and industrial sectors.
Promoter Holding (Mar 2026): Sanjay Gupta Family — 29.3% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹22,842 Cr vs ₹20,412 Cr in FY25 (+11.9% YoY). → Good
Net Profit: FY26 PAT ₹1,812 Cr vs ₹1,612 Cr in FY25 (+12.4% YoY). → Good
Operating Margin: FY26 EBITDA ₹3,212 Cr, margin 14.1% vs 13.6% last year (+50 bps). → Good
Equity Capital: Stable, face value ₹2. → Good
Dividend Policy: Dividend ₹8.00/share declared for FY26. → Good
Asset Building: Investments in Raipur plant expansion and value‑added products. → Good
Sales: Strong demand from construction and infra projects. → Good
Expense: Raw material cost pressures (steel, energy) remain. → Neutral/Good
EPS: FY26 EPS ₹60.25 vs ₹53.60 last year (+12.4%). → Good
Institutional Interest & Ownership Trends (Mar 2026)
Promoter Holding: 29.3% (no pledges)
FII Holding: 22.12%
DII Holding: 34.34%
Retail & Others: 14.24%
Strategic Moves & Innovations
Expansion in Raipur mega plant (capacity 4 MTPA).
Focus on value‑added structural steel products.
Partnerships with infra developers and government projects.
Diversification into exports and premium hollow sections.
Cash Flow & Balance Sheet Strength
Market cap ~₹56,800 Cr.
Debt‑to‑equity ratio ~0.42 (moderate leverage).
Book value per share ₹412.00; P/B ~4.9.
EPS (TTM) ₹60.25; P/E ~33.5.
Risk Factors
Moderate P/E ratio ~33.5, valuations expensive.
Dependence on construction and infra demand cycles.
Exposure to commodity price volatility (steel, energy).
Competition from Tata Steel, JSW Steel, and Jindal Steel.
Investor Takeaway
APL Apollo has delivered steady FY26 performance, supported by infra demand, Raipur expansion, and value‑added steel products. With promoter backing, dividend payouts, and leadership in structural steel tubes, APL Apollo remains a large‑cap infra‑linked steel play. At CMP ₹2,020.00, valuations are expensive (P/E ~33.5, P/B ~4.9), reflecting growth expectations but also sectoral risks.

Sucrit.D.Patil
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Sucrit.D.Patil
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.