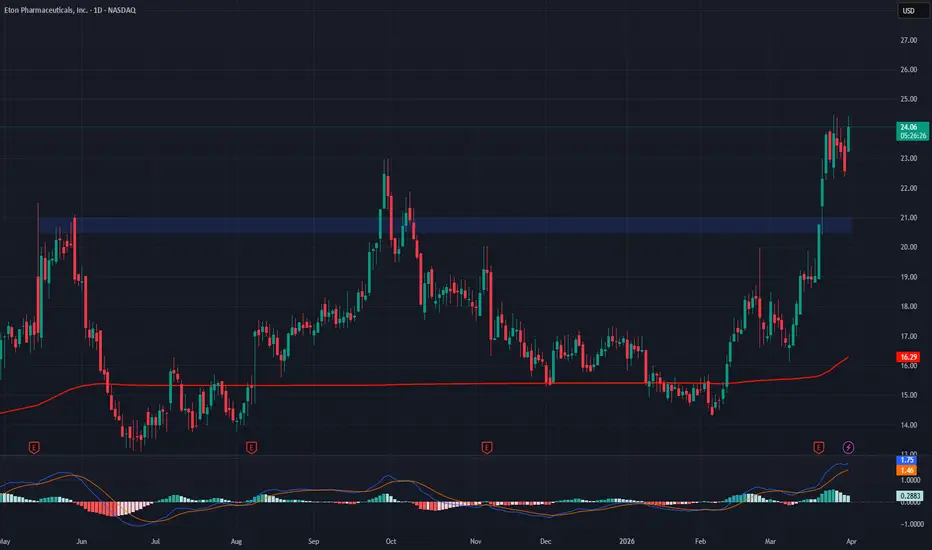
Eton Pharmaceuticals  ETON is a specialty pharma focused on rare disease treatments (notably pediatric and endocrine), offering exposure to high-margin orphan markets where pricing power and limited competition can drive outsized operating leverage.
Key Catalysts
Breakout Revenue Growth: Q4 2025 sales +83% YoY to $21.3M and full-year revenue more than doubled, reflecting strong execution on launches and niche indication expansion.
Portfolio Expansion Adds 2026 Fuel:
DESMODA (oral liquid desmopressin) launch expands the endocrine franchise.
HEMANGEOL acquisition strengthens the commercial base and adds a meaningful revenue contributor into 2026.
Profitability Inflection: 2026 guidance implies $110M+ revenue with 30%+ EBITDA margins, signaling powerful operating leverage as scale builds.
Orphan-Drug Playbook: Focused M&A in underserved rare diseases supports pricing durability, limited competitive pressure, and multiple near-term catalysts.
Investment Outlook
Bullish above: $20.50–$21.00
Upside target: $33.00–$34.00, driven by accelerating product sales, portfolio expansion, and margin expansion into 2026.
ETON is a specialty pharma focused on rare disease treatments (notably pediatric and endocrine), offering exposure to high-margin orphan markets where pricing power and limited competition can drive outsized operating leverage.Key Catalysts
Breakout Revenue Growth: Q4 2025 sales +83% YoY to $21.3M and full-year revenue more than doubled, reflecting strong execution on launches and niche indication expansion.
Portfolio Expansion Adds 2026 Fuel:
DESMODA (oral liquid desmopressin) launch expands the endocrine franchise.
HEMANGEOL acquisition strengthens the commercial base and adds a meaningful revenue contributor into 2026.
Profitability Inflection: 2026 guidance implies $110M+ revenue with 30%+ EBITDA margins, signaling powerful operating leverage as scale builds.
Orphan-Drug Playbook: Focused M&A in underserved rare diseases supports pricing durability, limited competitive pressure, and multiple near-term catalysts.
Investment Outlook
Bullish above: $20.50–$21.00
Upside target: $33.00–$34.00, driven by accelerating product sales, portfolio expansion, and margin expansion into 2026.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.