
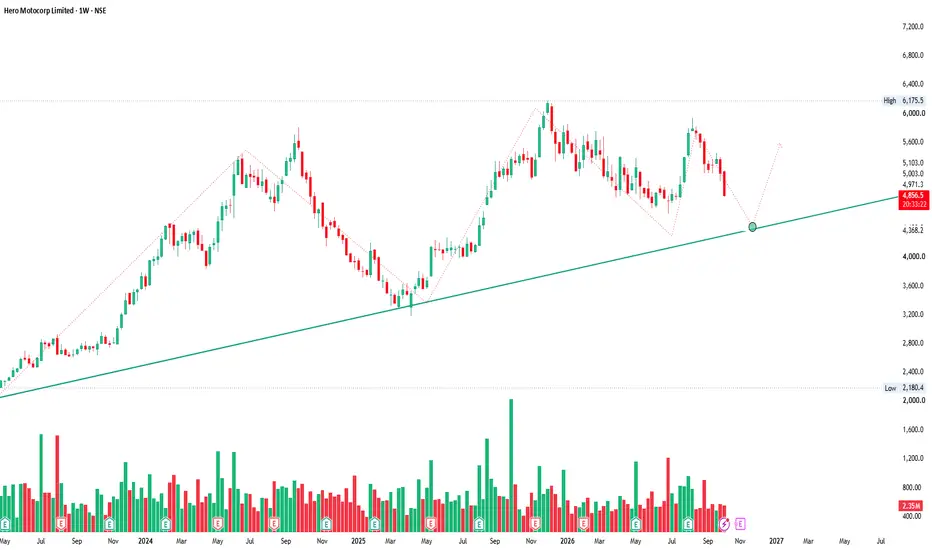
Hero MotoCorp is now approaching a very important technical zone on the weekly chart.
The stock has been respecting a long-term rising trendline since 2023, with multiple significant reactions from this trendline over the past few years.
After making a high around ₹6,175, the stock has entered a corrective phase and is now trading around ₹4,850.
The interesting part?
The long-term trendline is currently converging around the ₹4,400–₹4,500 zone.
That makes ₹4,400 a critical level to watch.
🔎 Why ₹4,400 matters
This isn't just an arbitrary support level.
The rising trendline has previously acted as a major demand zone, and price is now approaching it again after a sizeable correction.
So, from a technical perspective, I'm watching the ₹4,400–₹4,500 zone very closely.
🟢 Bullish scenario
If Hero MotoCorp reaches this zone and we see:
- Strong rejection from support
- Bullish reversal candles
- Increasing buying volume
- Price reclaiming nearby swing levels
then this could potentially turn into an accumulation zone rather than simply another breakdown.
The first confirmation would be a recovery above the recent swing resistance, followed by a higher-high/higher-low structure.
If the stock manages to regain momentum, the ₹5,000–₹5,100 area becomes the first zone to watch, followed by the ₹5,500–₹5,600 region.
A larger bullish move could eventually bring the previous high near ₹6,175 back into focus.
🔴 Bearish scenario
But there is one level I don't want to ignore:
₹4,400.
A decisive weekly breakdown below the long-term trendline, particularly if accompanied by strong volume, would weaken the entire bullish structure that has been developing since 2023.
In that case, I would not blindly treat ₹4,400 as a buying opportunity.
Instead, the market could start looking toward lower historical demand zones around ₹4,000 and ₹3,600.
🧠 The bigger picture
Interestingly, the technical setup is developing while the underlying two-wheeler demand picture remains relatively strong.
Hero reported 7.66 lakh total units in September 2026, up 12% YoY, with particularly strong scooter growth; industry-wide two-wheeler sales also benefited from festive-season demand.
The company had also reported strong FY26 operating performance, including 24% YoY volume growth in Q4 FY26 and a 30% YoY increase in standalone net profit.
So this is an interesting setup where fundamentals aren't necessarily telling the same story as the current price correction.
The stock has been respecting a long-term rising trendline since 2023, with multiple significant reactions from this trendline over the past few years.
After making a high around ₹6,175, the stock has entered a corrective phase and is now trading around ₹4,850.
The interesting part?
The long-term trendline is currently converging around the ₹4,400–₹4,500 zone.
That makes ₹4,400 a critical level to watch.
🔎 Why ₹4,400 matters
This isn't just an arbitrary support level.
The rising trendline has previously acted as a major demand zone, and price is now approaching it again after a sizeable correction.
So, from a technical perspective, I'm watching the ₹4,400–₹4,500 zone very closely.
🟢 Bullish scenario
If Hero MotoCorp reaches this zone and we see:
- Strong rejection from support
- Bullish reversal candles
- Increasing buying volume
- Price reclaiming nearby swing levels
then this could potentially turn into an accumulation zone rather than simply another breakdown.
The first confirmation would be a recovery above the recent swing resistance, followed by a higher-high/higher-low structure.
If the stock manages to regain momentum, the ₹5,000–₹5,100 area becomes the first zone to watch, followed by the ₹5,500–₹5,600 region.
A larger bullish move could eventually bring the previous high near ₹6,175 back into focus.
🔴 Bearish scenario
But there is one level I don't want to ignore:
₹4,400.
A decisive weekly breakdown below the long-term trendline, particularly if accompanied by strong volume, would weaken the entire bullish structure that has been developing since 2023.
In that case, I would not blindly treat ₹4,400 as a buying opportunity.
Instead, the market could start looking toward lower historical demand zones around ₹4,000 and ₹3,600.
🧠 The bigger picture
Interestingly, the technical setup is developing while the underlying two-wheeler demand picture remains relatively strong.
Hero reported 7.66 lakh total units in September 2026, up 12% YoY, with particularly strong scooter growth; industry-wide two-wheeler sales also benefited from festive-season demand.
The company had also reported strong FY26 operating performance, including 24% YoY volume growth in Q4 FY26 and a 30% YoY increase in standalone net profit.
So this is an interesting setup where fundamentals aren't necessarily telling the same story as the current price correction.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.