
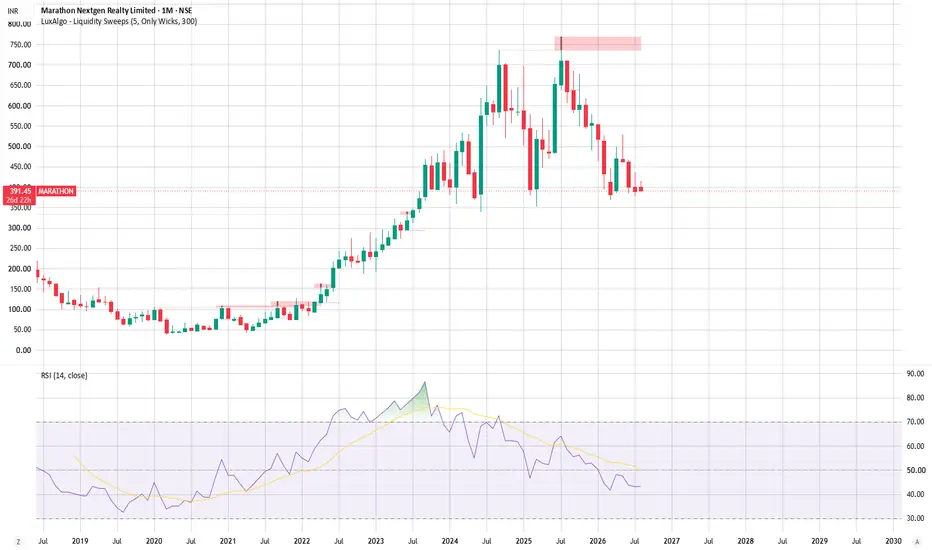
Marathon Nextgen Realty Ltd (NSE: MARATHON) – High Conviction Re-rating Candidate | Potential 2X in 18 Months
🏢 Business Profile
Marathon Nextgen Realty is a Mumbai-focused real estate developer with a strong presence in residential, commercial and redevelopment projects. The company benefits from premium land parcels, asset-light JDA/JV models, and an improving balance sheet. Strategic partnerships and redevelopment opportunities in Mumbai provide a long runway for growth. The company has also expanded its development pipeline through major joint ventures, improving future revenue visibility.
📊 Latest Quarterly Earnings
Q4 FY26 (Mar 2026)
Revenue: ₹114 Cr (weak due to project timing)
Net Profit: ₹46 Cr
EPS: ₹6.63
Profit remained healthy despite lower revenue due to strong other income and lower finance costs.
Q3 FY26 (Dec 2025)
Revenue: ₹125 Cr
Net Profit: ₹33 Cr
EPS: ₹4.80
Q2 FY26 (Sep 2025)
Revenue: ₹117 Cr
Net Profit: ₹67 Cr
Highest quarterly PAT during the year, demonstrating strong project profitability.
Key Observation
Although quarterly revenue has remained volatile (common in real estate), profitability has stayed consistently strong, with quarterly PAT ranging between ₹33–67 Cr, indicating healthy execution and margin resilience.
💰 Valuation
Current Price: ₹391
Market Cap: ₹2,677 Cr
P/E: 13.1x
Industry P/E: 29.1x
PEG Ratio: 0.74
Price to Book: 1.16x
Book Value: ₹337
Debt costs have reduced significantly, supporting future earnings growth.
At only 13x earnings, Marathon trades at a large discount to the sector despite delivering record annual profitability. If earnings continue to improve and valuation merely moves toward the industry average, a meaningful re-rating is possible.
🎯 Investment Thesis – Why I Expect a Potential 2X
✅ Valuation remains inexpensive (13x P/E vs 29x industry)
✅ Price is trading just above book value (P/B 1.16)
✅ Strong profitability despite cyclical revenue recognition
✅ Record annual PAT reflects improving execution
✅ Reduced interest expense boosts future EPS
✅ Mumbai redevelopment pipeline offers long-term growth visibility
✅ Any improvement in real estate sentiment can trigger a valuation re-rating.
My view: The market appears to be pricing Marathon based on quarterly revenue volatility rather than its improving earnings quality and development pipeline. If execution remains on track, a move toward ₹750–₹800 over the next 12–18 months is achievable through a combination of earnings growth and P/E re-rating.
📈 Trading Plan
Accumulation Zone: ₹380–410
Target 1: ₹520
Target 2: ₹650
Target 3: ₹780 (18-month bullish target)
Stop Loss: ₹340 (weekly closing basis)
⚠️ Risks
🏢 Business Profile
Marathon Nextgen Realty is a Mumbai-focused real estate developer with a strong presence in residential, commercial and redevelopment projects. The company benefits from premium land parcels, asset-light JDA/JV models, and an improving balance sheet. Strategic partnerships and redevelopment opportunities in Mumbai provide a long runway for growth. The company has also expanded its development pipeline through major joint ventures, improving future revenue visibility.
📊 Latest Quarterly Earnings
Q4 FY26 (Mar 2026)
Revenue: ₹114 Cr (weak due to project timing)
Net Profit: ₹46 Cr
EPS: ₹6.63
Profit remained healthy despite lower revenue due to strong other income and lower finance costs.
Q3 FY26 (Dec 2025)
Revenue: ₹125 Cr
Net Profit: ₹33 Cr
EPS: ₹4.80
Q2 FY26 (Sep 2025)
Revenue: ₹117 Cr
Net Profit: ₹67 Cr
Highest quarterly PAT during the year, demonstrating strong project profitability.
Key Observation
Although quarterly revenue has remained volatile (common in real estate), profitability has stayed consistently strong, with quarterly PAT ranging between ₹33–67 Cr, indicating healthy execution and margin resilience.
💰 Valuation
Current Price: ₹391
Market Cap: ₹2,677 Cr
P/E: 13.1x
Industry P/E: 29.1x
PEG Ratio: 0.74
Price to Book: 1.16x
Book Value: ₹337
Debt costs have reduced significantly, supporting future earnings growth.
At only 13x earnings, Marathon trades at a large discount to the sector despite delivering record annual profitability. If earnings continue to improve and valuation merely moves toward the industry average, a meaningful re-rating is possible.
🎯 Investment Thesis – Why I Expect a Potential 2X
✅ Valuation remains inexpensive (13x P/E vs 29x industry)
✅ Price is trading just above book value (P/B 1.16)
✅ Strong profitability despite cyclical revenue recognition
✅ Record annual PAT reflects improving execution
✅ Reduced interest expense boosts future EPS
✅ Mumbai redevelopment pipeline offers long-term growth visibility
✅ Any improvement in real estate sentiment can trigger a valuation re-rating.
My view: The market appears to be pricing Marathon based on quarterly revenue volatility rather than its improving earnings quality and development pipeline. If execution remains on track, a move toward ₹750–₹800 over the next 12–18 months is achievable through a combination of earnings growth and P/E re-rating.
📈 Trading Plan
Accumulation Zone: ₹380–410
Target 1: ₹520
Target 2: ₹650
Target 3: ₹780 (18-month bullish target)
Stop Loss: ₹340 (weekly closing basis)
⚠️ Risks

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.