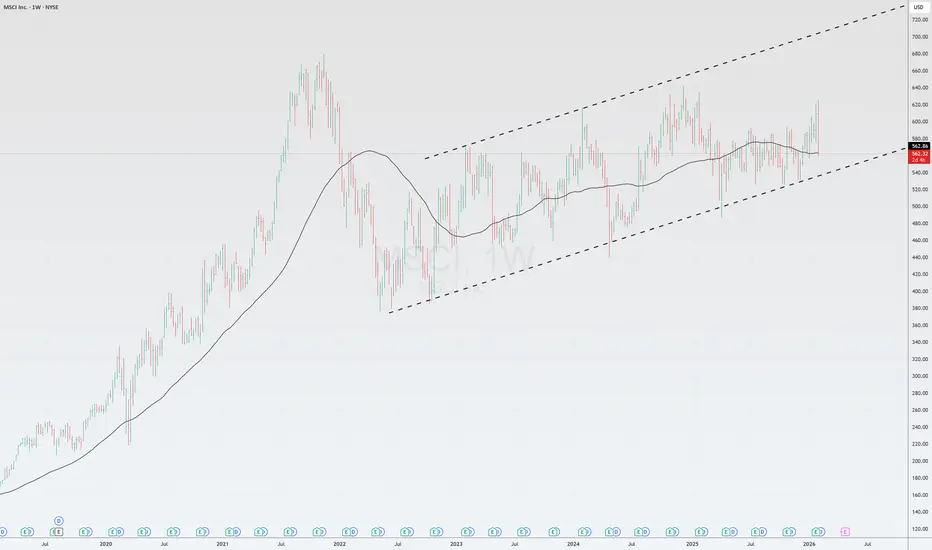
 MSCI has virtually no competitors with the same level of institutional trust, allowing the company to maintain significant pricing power.
AUM Growth: The influx of capital into ETFs and rising equity markets automatically boost MSCI's revenue through asset-based fees.
Moat: Proprietary benchmark datasets are nearly impossible to replicate, establishing a durable, long-term source of monetization.
Strong Q4 2024 Performance: The company exceeded expectations with an EPS of $4.66 (vs. the $4.58 forecast) and revenue reaching $822.5 million.
Capital Allocation: MSCI has repurchased nearly $3.3 billion in shares over the past two years.
AI Integration: Over 120 AI-based projects have been launched to optimize internal processes and develop new products. The AI segment is projected to accelerate earnings growth starting in 2026.
Growth Drivers
🔎

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.