
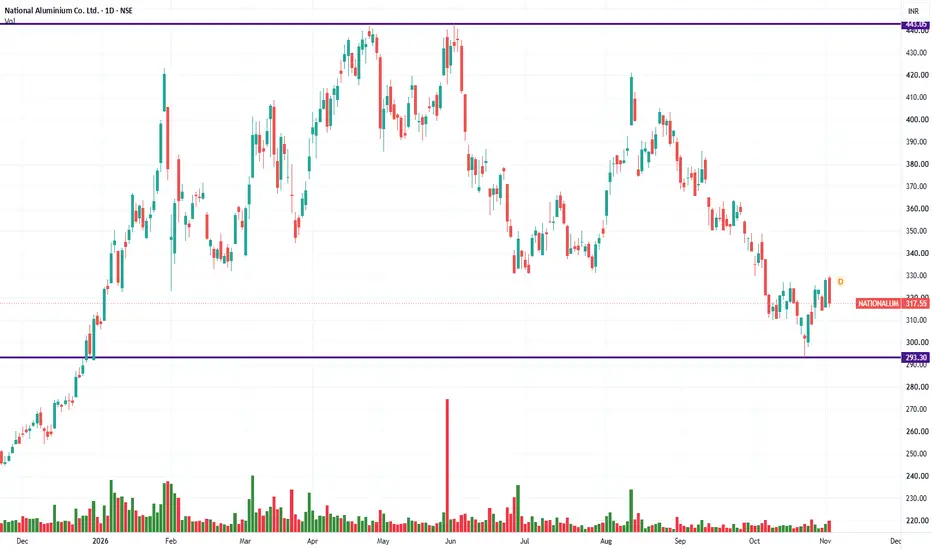
🚀NALCO Q2 FY27 RESULTS: PROFIT JUMPS 28% YoY! Can the Momentum Continue?
National Aluminium Company Ltd. (NALCO) has delivered a strong performance in Q2 FY27, backed by higher alumina realisations, robust aluminium production and improved year-on-year profitability.
However, rising input costs and a sequential decline in margins remain important factors to watch.
📊 Q2 FY27: Key Financial Highlights
📈 Quarter-on-Quarter Performance
Compared with Q1 FY27:
The message is clear: revenue is growing, but higher operating costs are putting pressure on sequential profitability.
🏆 H1 FY27: A Record First Half!
🔥 What Is Driving Growth?
✅ Improved alumina realisations, rising from approximately US$324/tonne in Q1 to US$370–375/tonne in Q2.
✅ Strong aluminium segment performance, with revenue growing approximately 44.6% YoY.
✅ Record H1 aluminium production and domestic sales.
✅ Better operating efficiency and higher sales realisations.
⚠️ Key Challenges to Watch
💡 Management Outlook: What Lies Ahead?
Management expects several factors to support H2 FY27:
💰 **Dividend Announcement**
NALCO has announced an interim dividend of **₹4.50 per share**.
📅 Record date: 6 November 2026
💵 Total declared payout: Approximately ₹826.48 crore
🔍 Overall Assessment
Positives:
Risks:
📌 Final Takeaway
#NALCO #NationalAluminiumCompany #NATIONALUM #Q2FY27Results #StockMarket #IndianStockMarket #QuarterlyResults #EarningsGrowth #Aluminium #MetalStocks #PSUStocks #FundamentalAnalysis #A2ZInvestor
*Disclaimer: This post is for educational and informational purposes only. It is not a buy or sell recommendation. Please conduct your own research before making investment decisions.*
National Aluminium Company Ltd. (NALCO) has delivered a strong performance in Q2 FY27, backed by higher alumina realisations, robust aluminium production and improved year-on-year profitability.
However, rising input costs and a sequential decline in margins remain important factors to watch.
📊 Q2 FY27: Key Financial Highlights
- In Q2 FY27, NALCO reported revenue of ₹5,419 crore, registering a year-on-year growth of 26.3%.
- EBITDA increased by approximately 28% to ₹2,659 crore,
- Net profit rose by 28.3% to ₹1,835 crore.
- The company's earnings per share (EPS) also improved by 28.2%, increasing from ₹7.79 in Q2 FY26 to ₹9.99 in Q2 FY27, reflecting strong year-on-year earnings growth.
📈 Quarter-on-Quarter Performance
Compared with Q1 FY27:
- Revenue increased by 2.2%.
- Net profit declined by 8.4%.
- EBITDA declined by approximately 7.7%.
- Operating margin fell from 51.1% to 44.5%.
The message is clear: revenue is growing, but higher operating costs are putting pressure on sequential profitability.
🏆 H1 FY27: A Record First Half!
- NALCO reported its best-ever first-half financial performance:
- Revenue: ₹10,722 Cr (+32.4%)
- EBITDA: ₹5,539 Cr (approximately +50%)
- Net Profit: ₹3,838 Cr (+54.8%)
- Aluminium cast metal production: Record 2.35 lakh tonnes
🔥 What Is Driving Growth?
✅ Improved alumina realisations, rising from approximately US$324/tonne in Q1 to US$370–375/tonne in Q2.
✅ Strong aluminium segment performance, with revenue growing approximately 44.6% YoY.
✅ Record H1 aluminium production and domestic sales.
✅ Better operating efficiency and higher sales realisations.
⚠️ Key Challenges to Watch
- Raw-material expenses increased approximately 43%.
- Power and fuel costs increased around 23%.
- Other expenses increased approximately 36%.
- Higher caustic soda and calcined petroleum coke prices are pressuring production costs.
- Export logistics disruptions and delays in mine development remain concerns.
- Chemicals segment revenue and profitability declined year-on-year.
💡 Management Outlook: What Lies Ahead?
Management expects several factors to support H2 FY27:
- H2 average alumina realisation target of approximately ₹35,000/tonne.
- Production-cost reduction target of ₹500–₹1,000 per tonne.
- Fifth-stream refinery expansion expected to begin production around late December or early January.
- Potential additional PBT improvement of ₹300–₹350 crore from expansion, efficiency gains and non-recurrence of certain costs.
💰 **Dividend Announcement**
NALCO has announced an interim dividend of **₹4.50 per share**.
📅 Record date: 6 November 2026
💵 Total declared payout: Approximately ₹826.48 crore
🔍 Overall Assessment
Positives:
- Strong year-on-year revenue and profit growth.
- Record H1 performance.
- Healthy cash generation.
- Expansion projects offer long-term growth opportunities.
- Attractive shareholder dividend.
Risks:
- Sequential margin contraction.
- Rising raw-material and energy costs.
- Commodity-price volatility.
- Export and project-execution challenges.
📌 Final Takeaway
- NALCO's Q2 FY27 results are strong on a year-on-year basis, and its record H1 performance reflects favourable market conditions and operational progress.
- However, investors should watch whether management can control input costs, improve margins and successfully commission the refinery expansion.
#NALCO #NationalAluminiumCompany #NATIONALUM #Q2FY27Results #StockMarket #IndianStockMarket #QuarterlyResults #EarningsGrowth #Aluminium #MetalStocks #PSUStocks #FundamentalAnalysis #A2ZInvestor
*Disclaimer: This post is for educational and informational purposes only. It is not a buy or sell recommendation. Please conduct your own research before making investment decisions.*

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.