
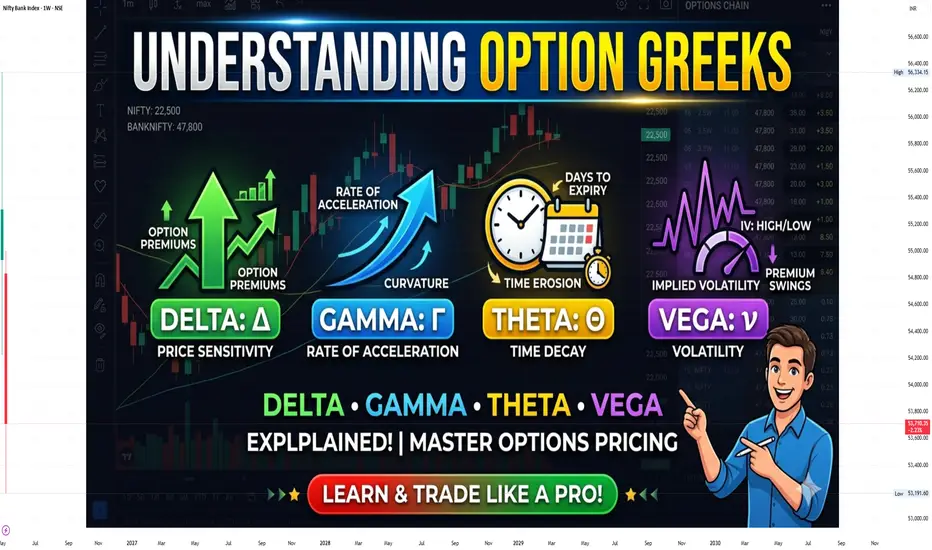
Option Greeks are one of the most important concepts in options trading because they help traders understand how option prices react to different market conditions. Greeks measure the sensitivity of an option’s premium based on changes in price, time, volatility, and market movement.
For every options trader, understanding Greeks is essential because they directly affect profit, loss, and trade management.
The four major Option Greeks are:
Delta
Gamma
Theta
Vega
1. What are Option Greeks?
Option Greeks are mathematical values used to measure how an option contract behaves when market conditions change.
They help traders understand:
How much an option premium may rise or fall
How time affects the option value
How volatility impacts pricing
How quickly option prices react to market movement
In simple words, Greeks explain the risk and behavior of an option contract.
2. Delta – Measures Price Movement
What is Delta?
Delta measures how much the option premium changes when the underlying asset moves by 1 point or ₹1.
It shows the relationship between the stock price and option premium movement.
Understanding Delta in Simple Words
If a Call Option has a Delta of 0.50, it means:
If the stock rises by ₹1
The option premium may rise by approximately ₹0.50
Similarly:
If the stock falls by ₹1
The option premium may fall by approximately ₹0.50
Delta Range
For Call Options
Delta ranges between 0 and +1
Call options gain value when the market rises
For Put Options
Delta ranges between 0 and -1
Put options gain value when the market falls
Example of Delta
Suppose:
Nifty is trading at 24,000
A Call Option premium is ₹100
Delta is 0.60
If Nifty moves up by 100 points:
Option premium may increase by approximately 60 points
New premium may become:
₹160
Importance of Delta
Delta helps traders:
Understand option price movement
Estimate probable profit or loss
Identify directional strength
Choose suitable strike prices
Higher Delta means the option reacts faster to market movement.
3. Gamma – Measures Delta Change
What is Gamma?
Gamma measures how much Delta changes when the underlying asset moves by 1 point.
In simple words:
Delta tells how premium moves
Gamma tells how Delta changes
Understanding Gamma Simply
Suppose:
Delta is 0.50
Gamma is 0.05
If the market rises by 1 point:
Delta changes from 0.50 to 0.55
If the market rises again:
Delta may increase further
This means option sensitivity increases as the market moves.
Importance of Gamma
Gamma becomes very important near expiry because option premiums move very quickly during that period.
High Gamma means:
Faster premium movement
Higher risk and reward
Increased volatility in option pricing
Key Points About Gamma
At-the-money options usually have the highest Gamma
Gamma increases near expiry
Option buyers generally benefit from high Gamma movement
4. Theta – Time Decay
What is Theta?
Theta measures how much option premium decreases with the passage of time.
Time decay is one of the biggest factors in options trading.
Every option loses value as expiry approaches.
Understanding Theta in Simple Words
Suppose:
Option premium is ₹100
Theta is -5
This means:
The option may lose ₹5 in value every day
Even if the market does not move
After one day:
Premium may become ₹95
Why Theta is Important
Time decay affects option buyers negatively because options continuously lose value.
Option sellers often benefit from Theta decay because premiums reduce over time.
Key Points About Theta
Theta increases rapidly near expiry
Out-of-the-money options lose value faster
Time decay works daily
Buyers need quick market movement to overcome Theta loss
5. Vega – Impact of Volatility
What is Vega?
Vega measures how much the option premium changes when implied volatility changes.
Volatility means the expected movement in the market.
Higher volatility generally increases option premiums.
Understanding Vega in Simple Words
Suppose:
Vega is 10
Implied volatility increases by 1%
Then:
Option premium may increase by approximately ₹10
Similarly:
If volatility falls
Option premium may decrease
Why Vega is Important
Volatility plays a major role in options pricing.
Before major events such as:
Budget announcements
Earnings reports
Economic data releases
Volatility usually increases, causing option premiums to rise.
Key Points About Vega
Higher volatility increases premiums
Lower volatility decreases premiums
Vega is higher in long-duration options
Event-based trading strongly affects Vega
6. Relationship Between Greeks
All Greeks work together in options trading.
For example:
Delta measures price movement
Gamma measures Delta change
Theta measures time decay
Vega measures volatility impact
Professional traders always analyze Greeks together instead of depending on only one factor.
7. Why Option Greeks are Important
Option Greeks help traders:
Manage risk properly
Understand option behavior
Select better strike prices
Improve entry and exit timing
Avoid emotional trading decisions
Without understanding Greeks, options trading becomes difficult because premium movement depends on multiple factors, not only market direction.

Pubblicazioni correlate
Declinazione di responsabilità
Le informazioni e le pubblicazioni non sono intese come, e non costituiscono, consulenza o raccomandazioni finanziarie, di investimento, di trading o di altro tipo fornite o approvate da TradingView. Per ulteriori informazioni, consultare i Termini di utilizzo.