
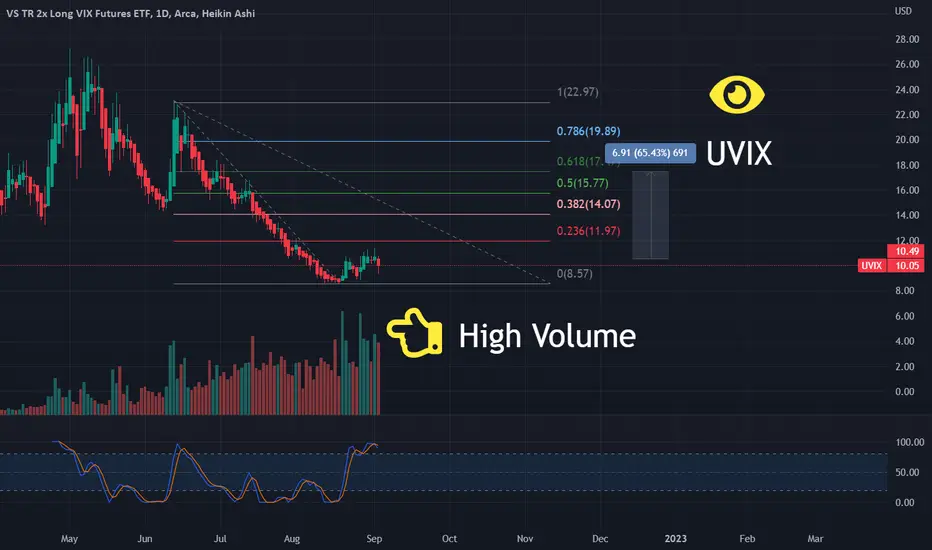
The index measures the daily performance of a portfolio of long positions in first and second month VIX futures contracts. This theoretical portfolio is rolled each day to maintain a consistent time to maturity of the futures contracts. The index is calculated daily at 4:00 p.m. (Eastern time) and at a value calculated from the average price for the futures contracts between 3:45 p.m. (Eastern time) and 4:00 p.m. (Eastern time).
Its that time of the year.
Its that time of the year.

99% of the market trades the noise. I trade the math. Professional divergence hunter and volume tracker. Enter the Seeker Lab:
linktr.ee/DivergenceSeeker
linktr.ee/DivergenceSeeker
Declinazione di responsabilità
Le informazioni e le pubblicazioni non sono intese come, e non costituiscono, consulenza o raccomandazioni finanziarie, di investimento, di trading o di altro tipo fornite o approvate da TradingView. Per ulteriori informazioni, consultare i Termini di utilizzo.