
How to Hedge Bear Markets Using Beta (Real case October 2026)
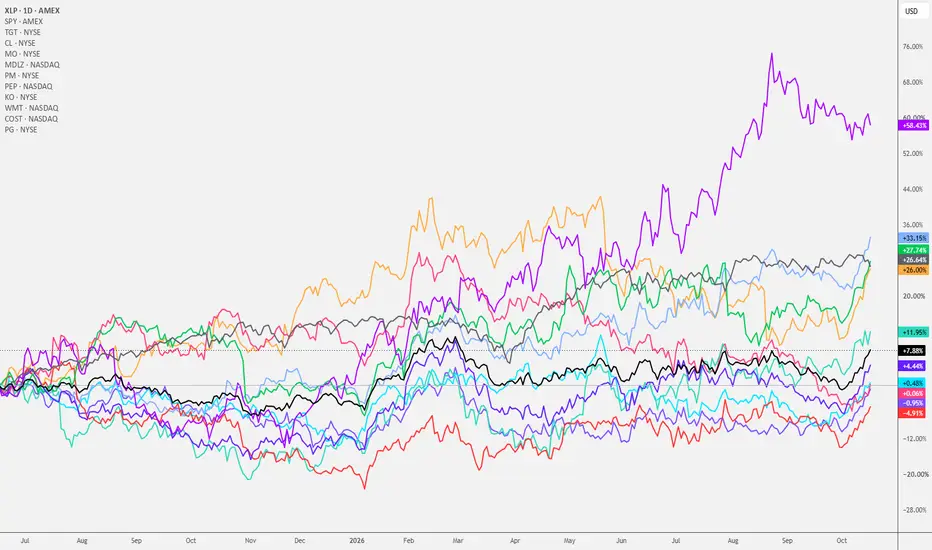
Description:
When market volatility spikes (VIX > 20) and benchmark yields remain elevated (US10Y > 5.0%), most retail traders make the mistake of either freezing or recklessly buying high-beta growth dips.
Institutional capital handles bear markets and sharp pullbacks using two core principles: Beta Allocation and Multi-Asset Performance Tracking.
🛡️ 1. What is Beta and How Does It Protect Your Portfolio?:
Beta measures an asset’s historical sensitivity relative to the broad market (S&P 500):
1.1) High Beta (beta > 1.0): Market Amplifiers (e.g., Semiconductors etf (SMH) beta approx 1.99). If the market drops -2%, high-beta assets can plunge -4% to -6%.
1.2) Low / Neutral Beta (beta < 0.10): Defensive Cushions (e.g., Consumer Staples etf (XLP) beta = 0.10, Coca-Cola (KO) beta = -0.01). These assets remain insulated during broader panics because their earnings depend on non-discretionary consumer needs.
💡 Tactical Takeaway:
When volatility surges, you don't need to exit the market completely. Rotating equity exposure toward Low/Neutral Beta provides an automatic hedge without incurring the time decay (Theta) associated with buying Put options.
📊 2. The Power of Comparative Performance Charts:
Tracking assets across isolated charts hides structural relative strength. Overlaying components on a single % Performance Chart reveals institutional flow instantly:
2.1) Set a Anchor Sector or Index: Use SPY or a broad sector ETF like XLP as a baseline.
2.2) Overlay Individual Holdings: Normalize performance from a shared starting date.
2.3 Visual Diagnosis:
2.3.1) Diverging Upper Curves: Highlight true institutional leaders (e.g., KO$,
 PM$) holding bid while indices decline.
2.3.2) Lagging Lower Curves: Signal weak structure or value traps undergoing forced liquidations.
📌3. Real-World Case Study (October 2026):
3.1) Macro Context: US10Y > 5.0%, VIX approx 20, and High-Beta Tech experiencing sharp liquidations (SMH -12.22% 1W).
3.2) Data Screening: KO displayed a near-zero Beta (beta = -0.01) alongside heavy institutional accumulation in Consumer Staples etf (XLP Rel Vol 1.98x).
3.3) Outcome: Holding neutral-beta leaders like KO delivered positive returns (+7.19% 1W / +34.43% YTD) while broad market indices suffered heavy drawdowns.
When market volatility spikes (VIX > 20) and benchmark yields remain elevated (US10Y > 5.0%), most retail traders make the mistake of either freezing or recklessly buying high-beta growth dips.
Institutional capital handles bear markets and sharp pullbacks using two core principles: Beta Allocation and Multi-Asset Performance Tracking.
🛡️ 1. What is Beta and How Does It Protect Your Portfolio?:
Beta measures an asset’s historical sensitivity relative to the broad market (S&P 500):
1.1) High Beta (beta > 1.0): Market Amplifiers (e.g., Semiconductors etf (SMH) beta approx 1.99). If the market drops -2%, high-beta assets can plunge -4% to -6%.
1.2) Low / Neutral Beta (beta < 0.10): Defensive Cushions (e.g., Consumer Staples etf (XLP) beta = 0.10, Coca-Cola (KO) beta = -0.01). These assets remain insulated during broader panics because their earnings depend on non-discretionary consumer needs.
💡 Tactical Takeaway:
When volatility surges, you don't need to exit the market completely. Rotating equity exposure toward Low/Neutral Beta provides an automatic hedge without incurring the time decay (Theta) associated with buying Put options.
📊 2. The Power of Comparative Performance Charts:
Tracking assets across isolated charts hides structural relative strength. Overlaying components on a single % Performance Chart reveals institutional flow instantly:
2.1) Set a Anchor Sector or Index: Use SPY or a broad sector ETF like XLP as a baseline.
2.2) Overlay Individual Holdings: Normalize performance from a shared starting date.
2.3 Visual Diagnosis:
2.3.1) Diverging Upper Curves: Highlight true institutional leaders (e.g.,
KO$, PM$) holding bid while indices decline.2.3.2) Lagging Lower Curves: Signal weak structure or value traps undergoing forced liquidations.
📌3. Real-World Case Study (October 2026):
3.1) Macro Context: US10Y > 5.0%, VIX approx 20, and High-Beta Tech experiencing sharp liquidations (SMH -12.22% 1W).
3.2) Data Screening: KO displayed a near-zero Beta (beta = -0.01) alongside heavy institutional accumulation in Consumer Staples etf (XLP Rel Vol 1.98x).
3.3) Outcome: Holding neutral-beta leaders like KO delivered positive returns (+7.19% 1W / +34.43% YTD) while broad market indices suffered heavy drawdowns.

Pubblicazioni correlate
Declinazione di responsabilità
Le informazioni e le pubblicazioni non sono intese come, e non costituiscono, consulenza o raccomandazioni finanziarie, di investimento, di trading o di altro tipo fornite o approvate da TradingView. Per ulteriori informazioni, consultare i Termini di utilizzo.
Pubblicazioni correlate
Declinazione di responsabilità
Le informazioni e le pubblicazioni non sono intese come, e non costituiscono, consulenza o raccomandazioni finanziarie, di investimento, di trading o di altro tipo fornite o approvate da TradingView. Per ulteriori informazioni, consultare i Termini di utilizzo.