CNPS24_BASIS MEAN REVERSION
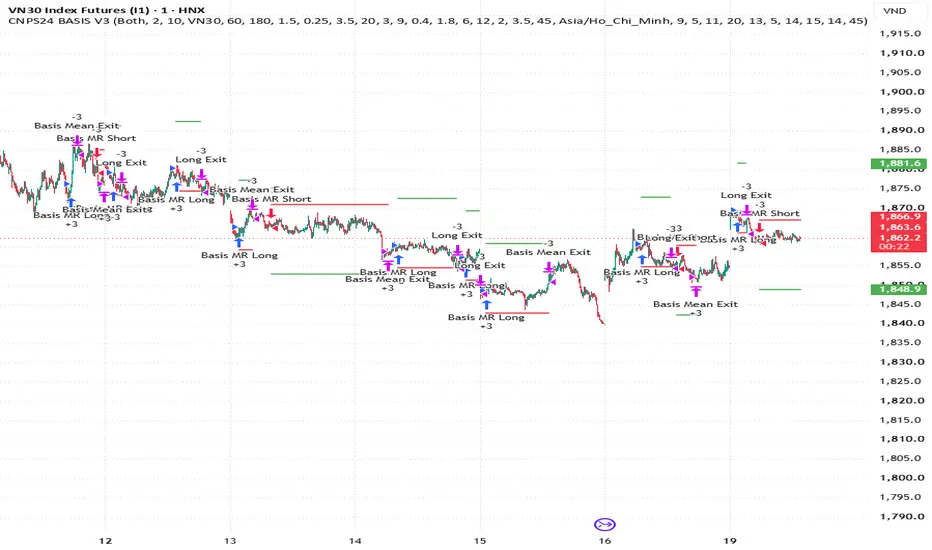
CNPS24 BASIS MEAN REVERSION V3
CNPS24 is a relative-value mean-reversion strategy designed around the price relationship between VN30 futures and the VN30 spot index.
Unlike a conventional directional indicator strategy, the primary signal is derived from the futures-versus-spot basis.
━━━━━━━━━━━━━━━━━━
1. STRATEGY CONCEPT
━━━━━━━━━━━━━━━━━━
The strategy calculates:
Futures Price
−
VN30 Spot Index
=
Intraday Basis
The basis is then standardized using its recent historical mean and volatility.
This produces a Basis Z-Score.
The strategy attempts to identify temporary extreme premiums or discounts and trade their normalization.
━━━━━━━━━━━━━━━━━━
2. REFERENCE MARKET
━━━━━━━━━━━━━━━━━━
Default Spot Reference:
HOSE:VN30
The futures price is taken from the active chart.
The quality and availability of the reference symbol are therefore important to the model.
━━━━━━━━━━━━━━━━━━
3. BASIS MODEL
━━━━━━━━━━━━━━━━━━
Default parameters:
Basis Mean / Z Window: 60 bars
Long Basis Volatility Window: 180 bars
The shorter window estimates the current mean and Z-score.
The longer window is used to evaluate the broader volatility regime of the basis.
━━━━━━━━━━━━━━━━━━
4. LONG SETUP
━━━━━━━━━━━━━━━━━━
A Long setup begins when futures trade at an unusually large discount relative to spot.
Sequence:
Basis Z <= -Entry Z
→ Extreme discount detected
→ Long setup is armed
→ Basis begins to hook upward
→ Price confirmation appears
→ LONG
Default Entry Z:
1.50
The strategy does not automatically buy the most extreme basis print.
It waits for evidence that the spread is beginning to mean-revert.
━━━━━━━━━━━━━━━━━━
5. SHORT SETUP
━━━━━━━━━━━━━━━━━━
A Short setup uses the mirrored process.
Basis Z >= +Entry Z
→ Extreme premium detected
→ Short setup is armed
→ Basis begins to hook downward
→ Price confirmation appears
→ SHORT
The concept is to trade normalization after futures become statistically expensive relative to the spot reference.
━━━━━━━━━━━━━━━━━━
6. EXTREME CONTROL
━━━━━━━━━━━━━━━━━━
The strategy limits how extreme the accepted entry condition can become.
Default Maximum Acceptable Absolute Z:
3.50
This prevents the model from automatically treating every increasingly extreme spread as a better mean-reversion opportunity.
A very large Z-score may instead indicate a regime change, data issue or persistent repricing.
━━━━━━━━━━━━━━━━━━
7. PRICE CONFIRMATION
━━━━━━━━━━━━━━━━━━
Basis normalization alone is not sufficient for entry.
The strategy also evaluates price action.
Default confirmation components include:
EMA Length: 9
Minimum Candle Body / Range: 40%
Previous High / Low Break: ON
EMA Confirmation: ON
This adds directional confirmation to the statistical basis signal.
━━━━━━━━━━━━━━━━━━
8. VOLATILITY REGIME FILTER
━━━━━━━━━━━━━━━━━━
CNPS24 includes a basis-volatility regime filter.
Default:
Enabled
Maximum Short-Term / Long-Term Basis Volatility Ratio:
1.80
The strategy can therefore reject setups when short-term basis volatility becomes unusually unstable relative to its longer-term behavior.
━━━━━━━━━━━━━━━━━━
9. HARD RISK MANAGEMENT
━━━━━━━━━━━━━━━━━━
Default:
Stop Loss: 6 points
Take Profit: 12 points
Theoretical fixed Risk/Reward:
1:2
Position Size:
3 contracts
Pyramiding is disabled.
━━━━━━━━━━━━━━━━━━
10. STATISTICAL EXIT
━━━━━━━━━━━━━━━━━━
The strategy can exit before the fixed Take Profit when the basis has already returned close to its statistical mean.
Default Mean-Reversion Exit:
Absolute Basis Z <= 0.25
However, the statistical exit is only allowed after the trade has reached a minimum open profit.
Default Minimum Profit:
2 points
This prevents the strategy from closing a position at the statistical mean while the directional trade is still unprofitable.
━━━━━━━━━━━━━━━━━━
11. OPTIONAL EMERGENCY CONTROLS
━━━━━━━━━━━━━━━━━━
The strategy includes an optional Z-score emergency stop.
Default:
OFF
An optional time stop is also available.
These controls are not part of the default execution path but can be evaluated during research.
━━━━━━━━━━━━━━━━━━
12. TRADE CONTROL
━━━━━━━━━━━━━━━━━━
Default:
Maximum Trades Per Day: 2
Cooldown After Exit: 10 bars
Break-Even: Not used
The strategy is intentionally cost-aware because spread signals on low timeframes can otherwise generate excessive turnover.
━━━━━━━━━━━━━━━━━━
13. SESSION MANAGEMENT
━━━━━━━━━━━━━━━━━━
Default timezone:
Asia/Ho_Chi_Minh
The strategy uses separate morning and afternoon entry windows.
The final entry time occurs before the end of the futures trading session.
Open positions are force-closed according to the configured session-end rule.
━━━━━━━━━━━━━━━━━━
14. BACKTEST ASSUMPTIONS
━━━━━━━━━━━━━━━━━━
Initial Capital: 100,000,000
Position Size: 3 contracts
Commission: 10,000 VND per contract
Slippage: 3 ticks
Pyramiding: 0
━━━━━━━━━━━━━━━━━━
15. IMPORTANT MODEL CONSIDERATIONS
━━━━━━━━━━━━━━━━━━
CNPS24 is fundamentally different from a standard trend-following system.
Its edge depends on the relationship between two instruments.
Backtesting should therefore pay particular attention to:
• Spot reference availability
• Data synchronization
• Basis behavior across expiries
• Intraday volatility
• Entry Z threshold
• Mean-reversion speed
• Transaction costs
• Structural changes in futures premium / discount
━━━━━━━━━━━━━━━━━━
DISCLAIMER
━━━━━━━━━━━━━━━━━━
This strategy is provided for educational, analytical and backtesting purposes only.
It does not constitute financial advice or a recommendation to trade a relative-value position.
Past statistical relationships may change and do not guarantee future convergence.
Trading futures and leveraged financial instruments involves substantial risk. Users are responsible for all trading and risk-management decisions.
CNPS24 is a relative-value mean-reversion strategy designed around the price relationship between VN30 futures and the VN30 spot index.
Unlike a conventional directional indicator strategy, the primary signal is derived from the futures-versus-spot basis.
━━━━━━━━━━━━━━━━━━
1. STRATEGY CONCEPT
━━━━━━━━━━━━━━━━━━
The strategy calculates:
Futures Price
−
VN30 Spot Index
=
Intraday Basis
The basis is then standardized using its recent historical mean and volatility.
This produces a Basis Z-Score.
The strategy attempts to identify temporary extreme premiums or discounts and trade their normalization.
━━━━━━━━━━━━━━━━━━
2. REFERENCE MARKET
━━━━━━━━━━━━━━━━━━
Default Spot Reference:
HOSE:VN30
The futures price is taken from the active chart.
The quality and availability of the reference symbol are therefore important to the model.
━━━━━━━━━━━━━━━━━━
3. BASIS MODEL
━━━━━━━━━━━━━━━━━━
Default parameters:
Basis Mean / Z Window: 60 bars
Long Basis Volatility Window: 180 bars
The shorter window estimates the current mean and Z-score.
The longer window is used to evaluate the broader volatility regime of the basis.
━━━━━━━━━━━━━━━━━━
4. LONG SETUP
━━━━━━━━━━━━━━━━━━
A Long setup begins when futures trade at an unusually large discount relative to spot.
Sequence:
Basis Z <= -Entry Z
→ Extreme discount detected
→ Long setup is armed
→ Basis begins to hook upward
→ Price confirmation appears
→ LONG
Default Entry Z:
1.50
The strategy does not automatically buy the most extreme basis print.
It waits for evidence that the spread is beginning to mean-revert.
━━━━━━━━━━━━━━━━━━
5. SHORT SETUP
━━━━━━━━━━━━━━━━━━
A Short setup uses the mirrored process.
Basis Z >= +Entry Z
→ Extreme premium detected
→ Short setup is armed
→ Basis begins to hook downward
→ Price confirmation appears
→ SHORT
The concept is to trade normalization after futures become statistically expensive relative to the spot reference.
━━━━━━━━━━━━━━━━━━
6. EXTREME CONTROL
━━━━━━━━━━━━━━━━━━
The strategy limits how extreme the accepted entry condition can become.
Default Maximum Acceptable Absolute Z:
3.50
This prevents the model from automatically treating every increasingly extreme spread as a better mean-reversion opportunity.
A very large Z-score may instead indicate a regime change, data issue or persistent repricing.
━━━━━━━━━━━━━━━━━━
7. PRICE CONFIRMATION
━━━━━━━━━━━━━━━━━━
Basis normalization alone is not sufficient for entry.
The strategy also evaluates price action.
Default confirmation components include:
EMA Length: 9
Minimum Candle Body / Range: 40%
Previous High / Low Break: ON
EMA Confirmation: ON
This adds directional confirmation to the statistical basis signal.
━━━━━━━━━━━━━━━━━━
8. VOLATILITY REGIME FILTER
━━━━━━━━━━━━━━━━━━
CNPS24 includes a basis-volatility regime filter.
Default:
Enabled
Maximum Short-Term / Long-Term Basis Volatility Ratio:
1.80
The strategy can therefore reject setups when short-term basis volatility becomes unusually unstable relative to its longer-term behavior.
━━━━━━━━━━━━━━━━━━
9. HARD RISK MANAGEMENT
━━━━━━━━━━━━━━━━━━
Default:
Stop Loss: 6 points
Take Profit: 12 points
Theoretical fixed Risk/Reward:
1:2
Position Size:
3 contracts
Pyramiding is disabled.
━━━━━━━━━━━━━━━━━━
10. STATISTICAL EXIT
━━━━━━━━━━━━━━━━━━
The strategy can exit before the fixed Take Profit when the basis has already returned close to its statistical mean.
Default Mean-Reversion Exit:
Absolute Basis Z <= 0.25
However, the statistical exit is only allowed after the trade has reached a minimum open profit.
Default Minimum Profit:
2 points
This prevents the strategy from closing a position at the statistical mean while the directional trade is still unprofitable.
━━━━━━━━━━━━━━━━━━
11. OPTIONAL EMERGENCY CONTROLS
━━━━━━━━━━━━━━━━━━
The strategy includes an optional Z-score emergency stop.
Default:
OFF
An optional time stop is also available.
These controls are not part of the default execution path but can be evaluated during research.
━━━━━━━━━━━━━━━━━━
12. TRADE CONTROL
━━━━━━━━━━━━━━━━━━
Default:
Maximum Trades Per Day: 2
Cooldown After Exit: 10 bars
Break-Even: Not used
The strategy is intentionally cost-aware because spread signals on low timeframes can otherwise generate excessive turnover.
━━━━━━━━━━━━━━━━━━
13. SESSION MANAGEMENT
━━━━━━━━━━━━━━━━━━
Default timezone:
Asia/Ho_Chi_Minh
The strategy uses separate morning and afternoon entry windows.
The final entry time occurs before the end of the futures trading session.
Open positions are force-closed according to the configured session-end rule.
━━━━━━━━━━━━━━━━━━
14. BACKTEST ASSUMPTIONS
━━━━━━━━━━━━━━━━━━
Initial Capital: 100,000,000
Position Size: 3 contracts
Commission: 10,000 VND per contract
Slippage: 3 ticks
Pyramiding: 0
━━━━━━━━━━━━━━━━━━
15. IMPORTANT MODEL CONSIDERATIONS
━━━━━━━━━━━━━━━━━━
CNPS24 is fundamentally different from a standard trend-following system.
Its edge depends on the relationship between two instruments.
Backtesting should therefore pay particular attention to:
• Spot reference availability
• Data synchronization
• Basis behavior across expiries
• Intraday volatility
• Entry Z threshold
• Mean-reversion speed
• Transaction costs
• Structural changes in futures premium / discount
━━━━━━━━━━━━━━━━━━
DISCLAIMER
━━━━━━━━━━━━━━━━━━
This strategy is provided for educational, analytical and backtesting purposes only.
It does not constitute financial advice or a recommendation to trade a relative-value position.
Past statistical relationships may change and do not guarantee future convergence.
Trading futures and leveraged financial instruments involves substantial risk. Users are responsible for all trading and risk-management decisions.

Declinazione di responsabilità
Le informazioni e le pubblicazioni non sono intese come, e non costituiscono, consulenza o raccomandazioni finanziarie, di investimento, di trading o di altro tipo fornite o approvate da TradingView. Per ulteriori informazioni, consultare i Termini di utilizzo.
Declinazione di responsabilità
Le informazioni e le pubblicazioni non sono intese come, e non costituiscono, consulenza o raccomandazioni finanziarie, di investimento, di trading o di altro tipo fornite o approvate da TradingView. Per ulteriori informazioni, consultare i Termini di utilizzo.