OPEN-SOURCE SCRIPT
Kalman Regime [Jamallo]
(2025)
Intro
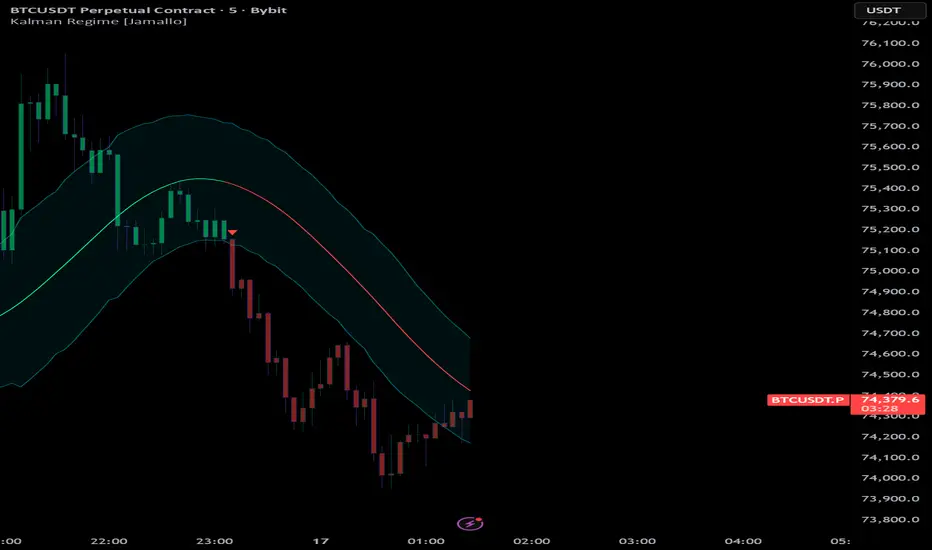
Kalman Regime filters price through two stages — a Gaussian kernel weighted average followed by an adaptive Kalman filter — to produce a smooth, noise-resistant baseline. ATR is used throughout to make the system volatility-aware.
Breakdown
The Gaussian kernel pre-smooths price using a bell-shaped weight profile that blends recency bias (recent bars matter more) with center localization (edge bars contribute less). This pre-smoothed value is then passed into an adaptive Kalman filter, which recursively estimates the "true" price state by balancing how much to trust the new measurement versus the prior state — with that balance dynamically scaled by current ATR.
The resulting baseline drives regime detection through a two-tier state machine. A strong signal fires when price breaks the ATR envelope and the baseline slope confirms direction. A weaker signal fires when price crosses the baseline and slope exceeds an ATR-scaled threshold. This dual-gate structure reduces whipsaws without adding lag.
END
A two-stage price filter combining a Gaussian kernel pre-smoother with an adaptive Kalman filter, using ATR envelopes and slope confirmation for regime detection.
Script open-source
Nello spirito di TradingView, l'autore di questo script lo ha reso open source, in modo che i trader possano esaminarne e verificarne la funzionalità. Complimenti all'autore! Sebbene sia possibile utilizzarlo gratuitamente, ricordiamo che la ripubblicazione del codice è soggetta al nostro Regolamento.

Join the Growing (Econophysics Trading) Community! ⚛️
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
Declinazione di responsabilità
Le informazioni e le pubblicazioni non sono intese come, e non costituiscono, consulenza o raccomandazioni finanziarie, di investimento, di trading o di altro tipo fornite o approvate da TradingView. Per ulteriori informazioni, consultare i Termini di utilizzo.
Script open-source
Nello spirito di TradingView, l'autore di questo script lo ha reso open source, in modo che i trader possano esaminarne e verificarne la funzionalità. Complimenti all'autore! Sebbene sia possibile utilizzarlo gratuitamente, ricordiamo che la ripubblicazione del codice è soggetta al nostro Regolamento.
Join the Growing (Econophysics Trading) Community! ⚛️
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
Declinazione di responsabilità
Le informazioni e le pubblicazioni non sono intese come, e non costituiscono, consulenza o raccomandazioni finanziarie, di investimento, di trading o di altro tipo fornite o approvate da TradingView. Per ulteriori informazioni, consultare i Termini di utilizzo.