
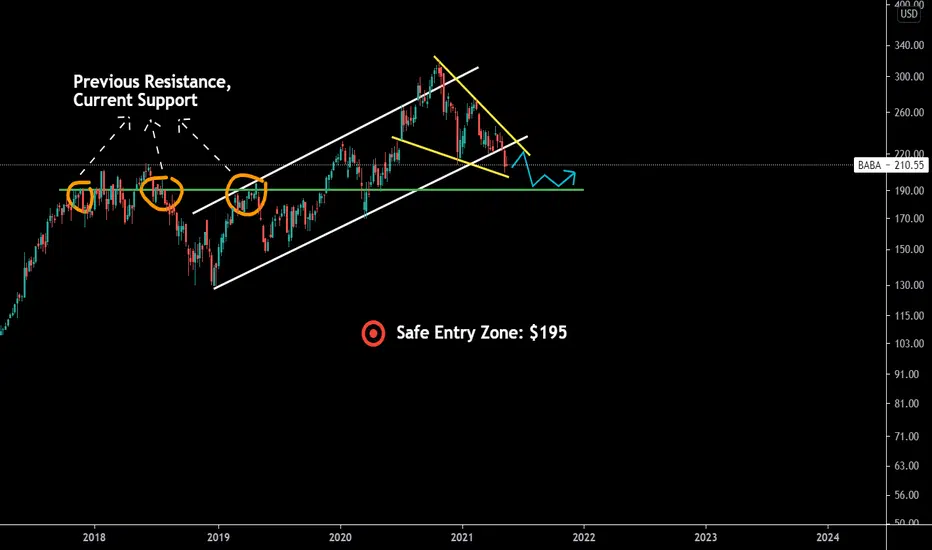
-As of Wednesday, Alibaba is down nearly 33% from its late October peak despite showing robust growth rates.
-The company suffered one of its worst earnings in Q1, with solid performance eclipsed by a hefty Chinese fine.
-From behind a cloud of negative headlines, Alibaba continues to shine as a fast-growing, profitable company with China’s backing.
-The most recent blow was its Q1 earnings report, in which the company reported a roughly $800 million loss, its first-ever as a public company.
-BABA is substantially undervalued and the threats to its success are exaggerated.
Our Opinion:
BABA is oversold but with the given economic volatility and tech sector crash, a safe entry zone can be seen at around $195.

免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。