
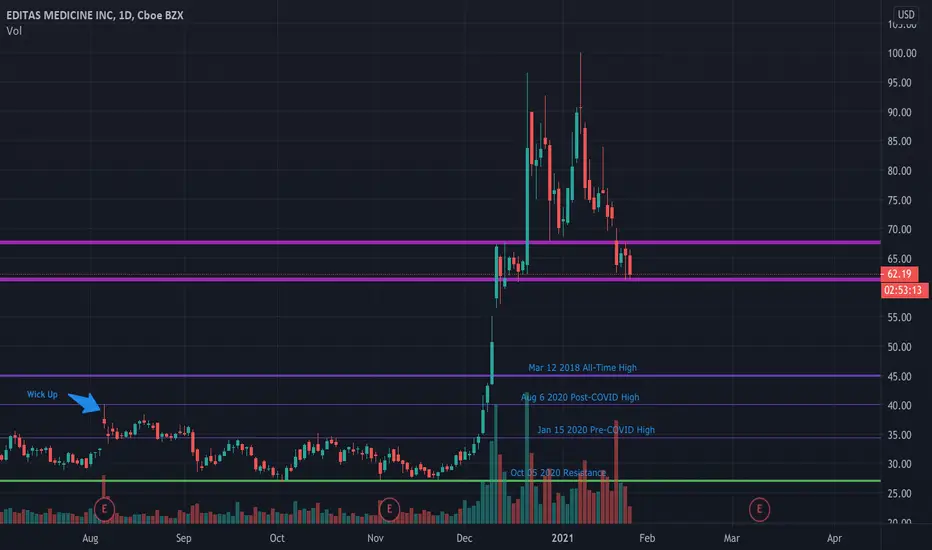
Clearly a lot of value has been lost in the past month. The CSO stepped down and analysts downgraded projected revenue. EDIT has very lucrative candidates in the pipeline treating sickle cell anemia. Long-term, this company will most certainly be profitable, with significant patent protection. This is a short term down draft that is consolidating, for the near term, around a non-speculation, fair price of $63.

免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。