
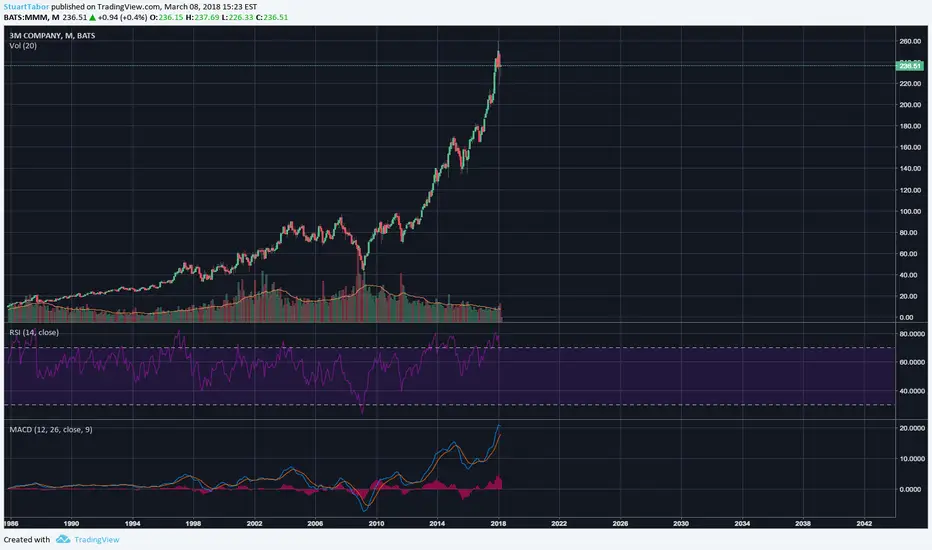
I did a discounted cash flow valuation on 3m assuming a revenue growth rate of 5%, in line with 10, 5, and 3 year historical averages and it produced a valuation of $135. A 41% downside valuation... When I saw this I questioned the legitimacy, but played around with revenue growth rates and found, that, to justify it's current valuation of $236.55, MMM would need to see top-line growth of 12% YoY.
Leave a comment and let me know what your thoughts on MMM are, for now I'm short them, but would love to hear some other view points.
Leave a comment and let me know what your thoughts on MMM are, for now I'm short them, but would love to hear some other view points.
ノート
It's been a great ride so far. Looking forward to more downside for MMM after EPS shrunk by over 50%! Down $15/share today.ノート
I feel as though throughout the quarter, MMM will gain some ground and go to about $220 per share at resistance. You could play this multiple ways.1. Buy calls at 200 so you can exit the short position at this price in the future
2. Cover now and take profits and have had quite the successful trade
3. Hold throughout the quarter and see what happens at the next earnings announcement. It is likely that the company will continue to revert to the market mean PE multiple of 17 which would imply a $140 share price - consistent with my valuation.
ノート
Moreover, analsyts have a target price of $230 and believe the stock to be overweight.
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。