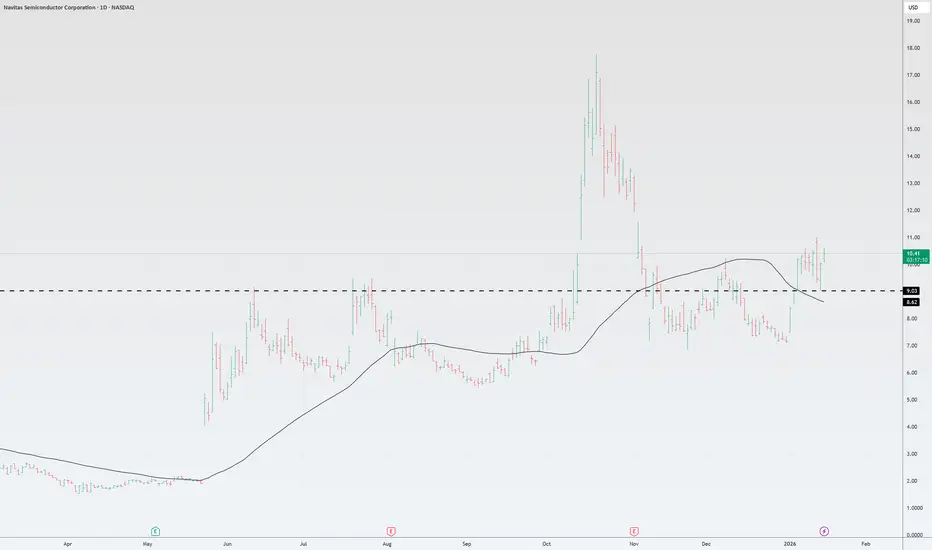
Navitas Semiconductor ( NVTS): Strategy 2.0 & The AI Pivot
Navitas is an ambitious player in the power semiconductor market (GaN & SiC). The company is intentionally disrupting its legacy low-margin mobile charging business to reinvent itself as a high-margin provider for AI data centers and industrial infrastructure.
Strategic Growth Drivers
The "Navitas 2.0" strategy focuses on capturing high-growth sectors using two core technologies:
GaN (Gallium Nitride): Compact, high-frequency solutions for server racks.
SiC (Silicon Carbide): Ultra-high voltage modules for power grids and EV stations.
Key Catalysts:
NVIDIA Partnership: Developing new 800V power supply architectures for AI factories.
Next-Gen Modules: Launch of 2.3 kV and 3.3 kV SiC modules for smart grids and energy storage.
US Manufacturing: Partnership with GlobalFoundries to produce GaN chips in the US, reducing Taiwan dependency and unlocking government contracts.
Strategic Alliance: Collaboration with Cyient for entry into renewable energy and EV infrastructure.
Financial Health & Projections
The company is currently navigating the "bottom" of its transformation. While current revenue is suppressed, the balance sheet remains debt-free.
Latest Financial Snapshot (2025-2026):
Revenue (Q4 2025): ~$7.0M (The projected cyclical bottom).
Cash Position: ~$150M (Zero debt) – providing a solid runway.
Gross Margin (TTM): 24%.
Valuation: P/S ratio remains high ~35 as markets price in future AI-driven growth.
Revenue Roadmap (Estimates):
2025: ~$45M (Transition year)
2026: ~$36M (Finalizing pivot)
2027: ~$66M (+80% YoY) – Projected launch of major AI projects.
2028: ~$130M (+96% YoY) – Expected Break-even / Operational Profit.
Investment Thesis
AI Infrastructure Bet: If Navitas successfully integrates into the hyperscaler supply chain (Amazon, Google, Microsoft) via its NVIDIA partnership, the stock could see explosive growth.
Operational Pivot: The shift from mobile chargers to industrial/AI power solutions significantly improves long-term margin profiles.
Market Sentiment: The primary trigger for a trend reversal will be the end of quarterly revenue declines, signaling that the "Navitas 2.0" transition is complete.
NVTS): Strategy 2.0 & The AI PivotNavitas is an ambitious player in the power semiconductor market (GaN & SiC). The company is intentionally disrupting its legacy low-margin mobile charging business to reinvent itself as a high-margin provider for AI data centers and industrial infrastructure.
Strategic Growth Drivers
The "Navitas 2.0" strategy focuses on capturing high-growth sectors using two core technologies:
GaN (Gallium Nitride): Compact, high-frequency solutions for server racks.
SiC (Silicon Carbide): Ultra-high voltage modules for power grids and EV stations.
Key Catalysts:
NVIDIA Partnership: Developing new 800V power supply architectures for AI factories.
Next-Gen Modules: Launch of 2.3 kV and 3.3 kV SiC modules for smart grids and energy storage.
US Manufacturing: Partnership with GlobalFoundries to produce GaN chips in the US, reducing Taiwan dependency and unlocking government contracts.
Strategic Alliance: Collaboration with Cyient for entry into renewable energy and EV infrastructure.
Financial Health & Projections
The company is currently navigating the "bottom" of its transformation. While current revenue is suppressed, the balance sheet remains debt-free.
Latest Financial Snapshot (2025-2026):
Revenue (Q4 2025): ~$7.0M (The projected cyclical bottom).
Cash Position: ~$150M (Zero debt) – providing a solid runway.
Gross Margin (TTM): 24%.
Valuation: P/S ratio remains high ~35 as markets price in future AI-driven growth.
Revenue Roadmap (Estimates):
2025: ~$45M (Transition year)
2026: ~$36M (Finalizing pivot)
2027: ~$66M (+80% YoY) – Projected launch of major AI projects.
2028: ~$130M (+96% YoY) – Expected Break-even / Operational Profit.
Investment Thesis
AI Infrastructure Bet: If Navitas successfully integrates into the hyperscaler supply chain (Amazon, Google, Microsoft) via its NVIDIA partnership, the stock could see explosive growth.
Operational Pivot: The shift from mobile chargers to industrial/AI power solutions significantly improves long-term margin profiles.
Market Sentiment: The primary trigger for a trend reversal will be the end of quarterly revenue declines, signaling that the "Navitas 2.0" transition is complete.

免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。