
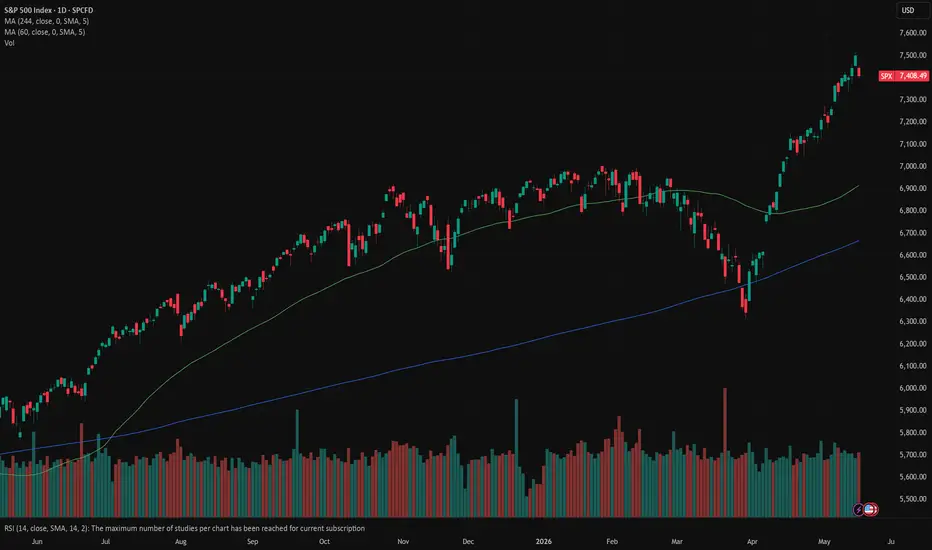
The S&P 500 continued to move in a highly overbought market territory, reaching a new all time highest level at 7.515. Still, a fear from incoming inflation pushed the index toward lower grounds on Friday, closing the week at 7.408, or 1,2% lower from the previous day with only a modest weekly gain.
U.S. macro drivers were standing behind the pullback. Inflation concerns intensified after stronger than expected producers price index and manufacturing data suggested the U.S. economy remains resilient, reducing expectations for Federal Reserve rate cuts. Treasury yields reacted strongly to inflation expectations and Fed potential movements, with 10Y jumping to 4,6% and the 30Y bond yield rising above 5%, levels that increased pressure on equities, especially to sectors with high growth expectations. Investors increasingly shifted toward a “higher-for-longer” interest rate outlook, which weighed on valuations across technology and AI related stocks.
With increasing oil prices, the energy sector was again the best performing. Analysts are noting that this sector extended its 14 week winning streak, the longest on record. High commodity prices also supported the materials sector, including investors expectations for infrastructure and industrial demand in the future period. On the opposite side were information technology, real estate and utilities sectors. The information technology companies were one of the weakest weekly performers especially semiconductors and names like Intel, AMD, Micron and Qualcomm, which saw significant pullbacks after strong recent rallies.
Macro risks currently represent the most significant risks for investors optimism. Modest correction is quite possible in the coming period in equity indexes, especially after a strong rally as seen for the last few weeks. However, for the moment, the outlook remains positive, but it should be kept in mind market sensitivity to any news which might influence correction in investors’ expectations.

関連の投稿
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。