
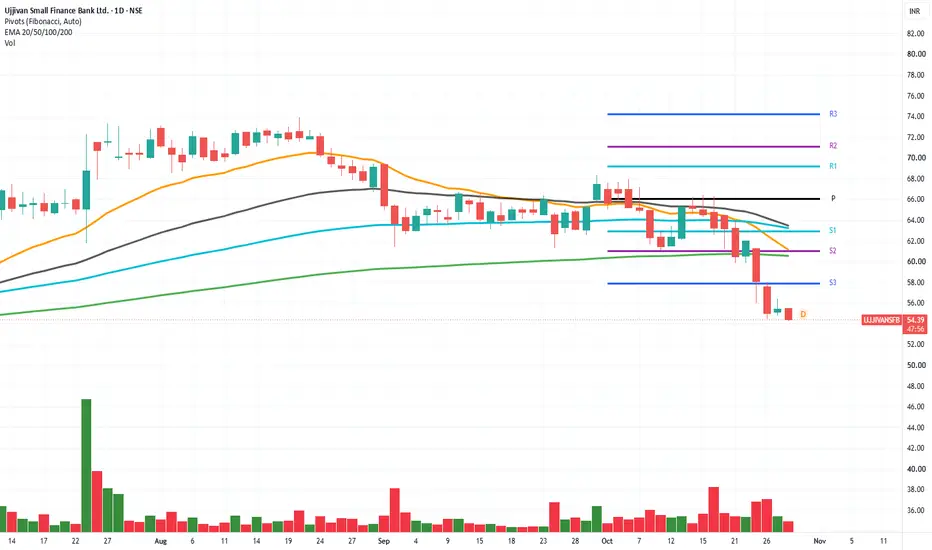
🚨 UJJIVAN SFB FALLS DESPITE RECORD PROFITS! WHY IS THE STOCK UNDER PRESSURE?
📉 **The stock-market puzzle:** Strong quarterly results, but a falling share price. What is worrying investors?
📊 Q2 FY27: Key Financial Highlights
✅ **Net Profit:** ₹365 crore, up approximately 200% YoY.
✅ **Net Interest Income (NII):** ₹1,244 crore, up 35% YoY.
✅ **Loan Book:** ₹45,699 crore, up 32.1% YoY.
✅ **Deposits:** ₹50,643 crore, up 29.2% YoY.
✅ **Gross NPA:** Improved to 2.10% from 2.45% a year ago.
✅ **Net NPA:** Improved to 0.31% from 0.67%.
✅ **Capital Adequacy:** 20.69%.
🔍 Why Is the Share Price Falling?
1️⃣ Margin Pressure
2️⃣ Profit Growth Sustainability
3️⃣ Leadership Uncertainty
4️⃣ Asset Quality Risks
5️⃣ Proposed Capital Raise
6️⃣ Technical Weakness
👀 What Should Investors Watch?
🎯 Final Takeaway
Strong results do not automatically guarantee a rising share price.
#UjjivanSFB #UJJIVANSFB #BankingStocks #QuarterlyResults #SmallFinanceBank #StockMarketIndia #FundamentalAnalysis #TradingView
*Disclaimer: For educational purposes only. Not a buy/sell recommendation. Verify the latest financial disclosures and market prices before making investment decisions.*
📉 **The stock-market puzzle:** Strong quarterly results, but a falling share price. What is worrying investors?
📊 Q2 FY27: Key Financial Highlights
✅ **Net Profit:** ₹365 crore, up approximately 200% YoY.
✅ **Net Interest Income (NII):** ₹1,244 crore, up 35% YoY.
✅ **Loan Book:** ₹45,699 crore, up 32.1% YoY.
✅ **Deposits:** ₹50,643 crore, up 29.2% YoY.
✅ **Gross NPA:** Improved to 2.10% from 2.45% a year ago.
✅ **Net NPA:** Improved to 0.31% from 0.67%.
✅ **Capital Adequacy:** 20.69%.
🔍 Why Is the Share Price Falling?
1️⃣ Margin Pressure
- Management expects NIM to moderate to around 8.35% in H2 FY27.
- Higher deposit costs could restrict future profitability.
2️⃣ Profit Growth Sustainability
- The near-200% profit increase is impressive, but investors will look for sustained core earnings growth as provisions and other factors normalise.
3️⃣ Leadership Uncertainty
- MD Sanjeev Nautiyal retired early in September 2026.
- The appointment of a permanent managing director remains an important monitorable.
4️⃣ Asset Quality Risks
- NPAs have improved, but investors must continue monitoring loan collections, fresh slippages and credit costs.
- Early delinquencies in the newer micro-mortgage portfolio deserve attention.
5️⃣ Proposed Capital Raise
- The proposed ₹409 crore equity issue could support growth and strengthen capital.
- Investors may assess its implications for dilution, book value and future earnings.
6️⃣ Technical Weakness
- The stock has been trading below important moving averages.
- Weak market sentiment and technical selling may be amplifying the decline.
👀 What Should Investors Watch?
- NIM stability and deposit funding costs.
- Loan growth versus asset-quality trends.
- Fresh slippages and credit costs.
- Appointment of a permanent MD.
- Whether the stock stabilises and reclaims important moving averages.
🎯 Final Takeaway
Strong results do not automatically guarantee a rising share price.
- Ujjivan SFB has delivered impressive profit growth, stronger NII and improving NPAs. However, margin pressure, leadership uncertainty and technical weakness are creating concerns about future performance.
- The key question is whether the bank can sustain earnings growth while controlling funding costs and credit risk.
- Do not mistake a falling price for an automatic buying opportunity.
*Focus on fundamentals, valuation and evidence of stabilisation.
#UjjivanSFB #UJJIVANSFB #BankingStocks #QuarterlyResults #SmallFinanceBank #StockMarketIndia #FundamentalAnalysis #TradingView
*Disclaimer: For educational purposes only. Not a buy/sell recommendation. Verify the latest financial disclosures and market prices before making investment decisions.*

免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。