OPEN-SOURCE SCRIPT
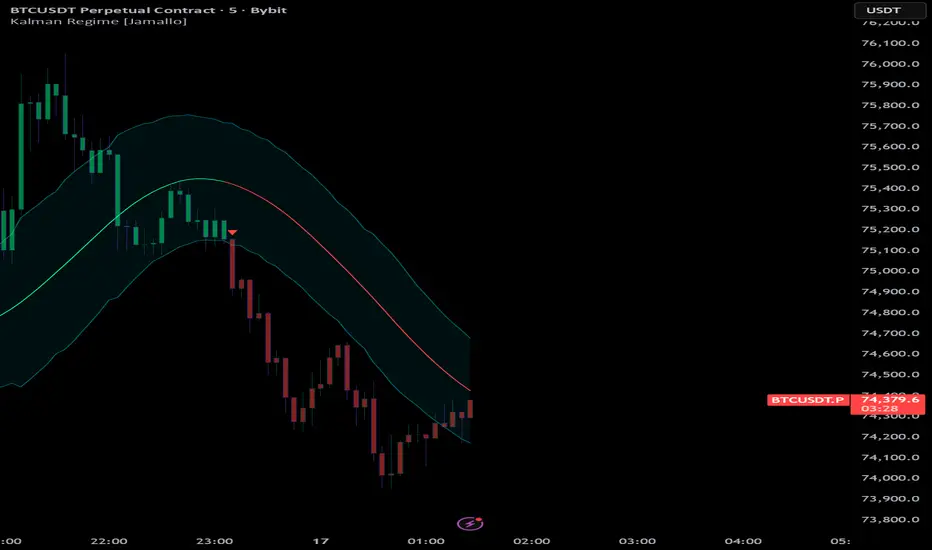
Kalman Regime [Jamallo]
(2025)
Intro
Kalman Regime filters price through two stages — a Gaussian kernel weighted average followed by an adaptive Kalman filter — to produce a smooth, noise-resistant baseline. ATR is used throughout to make the system volatility-aware.
Breakdown
The Gaussian kernel pre-smooths price using a bell-shaped weight profile that blends recency bias (recent bars matter more) with center localization (edge bars contribute less). This pre-smoothed value is then passed into an adaptive Kalman filter, which recursively estimates the "true" price state by balancing how much to trust the new measurement versus the prior state — with that balance dynamically scaled by current ATR.
The resulting baseline drives regime detection through a two-tier state machine. A strong signal fires when price breaks the ATR envelope and the baseline slope confirms direction. A weaker signal fires when price crosses the baseline and slope exceeds an ATR-scaled threshold. This dual-gate structure reduces whipsaws without adding lag.
END
A two-stage price filter combining a Gaussian kernel pre-smoother with an adaptive Kalman filter, using ATR envelopes and slope confirmation for regime detection.
オープンソーススクリプト
TradingViewの精神に則り、このスクリプトの作者はコードをオープンソースとして公開してくれました。トレーダーが内容を確認・検証できるようにという配慮です。作者に拍手を送りましょう!無料で利用できますが、コードの再公開はハウスルールに従う必要があります。

Join the Growing (Econophysics Trading) Community! ⚛️
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。
オープンソーススクリプト
TradingViewの精神に則り、このスクリプトの作者はコードをオープンソースとして公開してくれました。トレーダーが内容を確認・検証できるようにという配慮です。作者に拍手を送りましょう!無料で利用できますが、コードの再公開はハウスルールに従う必要があります。
Join the Growing (Econophysics Trading) Community! ⚛️
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。