OPEN-SOURCE SCRIPT
アップデート済 Volatility Adjusted EMA - by Crunchster
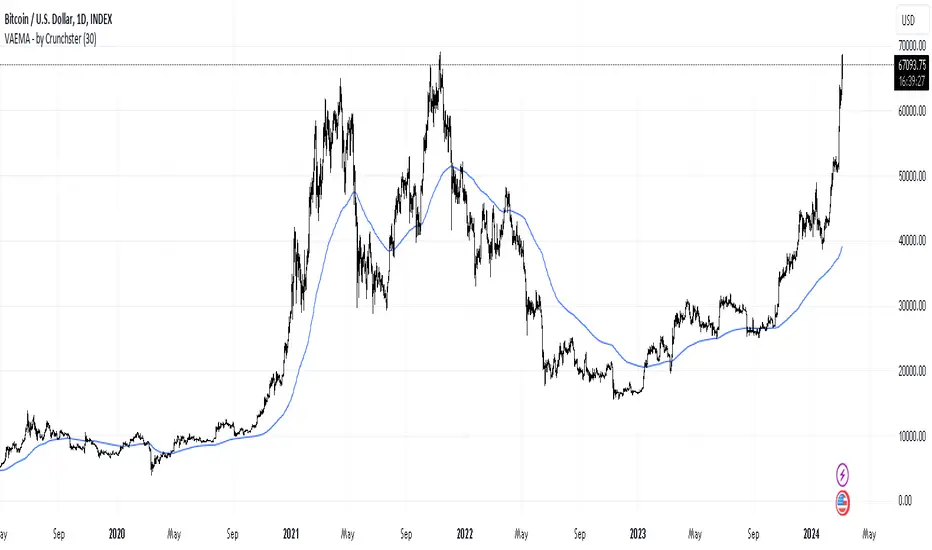
Applies recent volatility adjustment to the exponential moving average, where the smoothing factor is 2/(N + 1) - N being the lookback period or span
Volatility of recent 30 days returns is calculated using standard deviation with a thirty day lookback.
Increased smoothing compared to a standard EMA, which also adjusts to market conditions, as first described by Chande in 1991.
Volatility of recent 30 days returns is calculated using standard deviation with a thirty day lookback.
Increased smoothing compared to a standard EMA, which also adjusts to market conditions, as first described by Chande in 1991.
リリースノート
Minor code updateオープンソーススクリプト
TradingViewの精神に則り、このスクリプトの作者はコードをオープンソースとして公開してくれました。トレーダーが内容を確認・検証できるようにという配慮です。作者に拍手を送りましょう!無料で利用できますが、コードの再公開はハウスルールに従う必要があります。

Join me on Mizar.com and trade my strategies
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。
オープンソーススクリプト
TradingViewの精神に則り、このスクリプトの作者はコードをオープンソースとして公開してくれました。トレーダーが内容を確認・検証できるようにという配慮です。作者に拍手を送りましょう!無料で利用できますが、コードの再公開はハウスルールに従う必要があります。
Join me on Mizar.com and trade my strategies
免責事項
これらの情報および投稿は、TradingViewが提供または承認する金融、投資、取引、またはその他の種類の助言もしくは推奨であることを意図したものではなく、またこれらに該当するものでもありません。詳細は利用規約をご覧ください。