
AMAZON
9 - 13 May
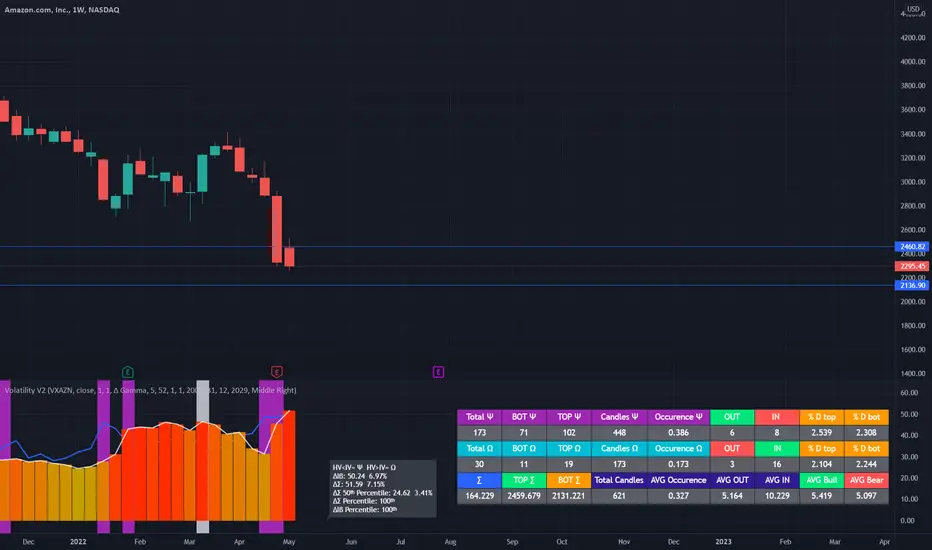
The weekly VXAZN-> Volatility Index for AMAZON
Implied = 50.24
In this we have to standard it for weekly session
39.02 / sqrt(52-> 52 weeks in a year) = 6.97%
My historical product is telling me with 1x coficient that the expected movement for this week
E Volatility = 51.59 / sqrt(52) = 7.15%
With this data, from my calculations, when EV > VIX, there were a 83% chance that the market
stay within the bottom and top created with the ranged from the E Vol
So for next week this range for us is going to be
TOP - 2460
BOT - 2131
9 - 13 May
The weekly VXAZN-> Volatility Index for AMAZON
Implied = 50.24
In this we have to standard it for weekly session
39.02 / sqrt(52-> 52 weeks in a year) = 6.97%
My historical product is telling me with 1x coficient that the expected movement for this week
E Volatility = 51.59 / sqrt(52) = 7.15%
With this data, from my calculations, when EV > VIX, there were a 83% chance that the market
stay within the bottom and top created with the ranged from the E Vol
So for next week this range for us is going to be
TOP - 2460
BOT - 2131

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.