
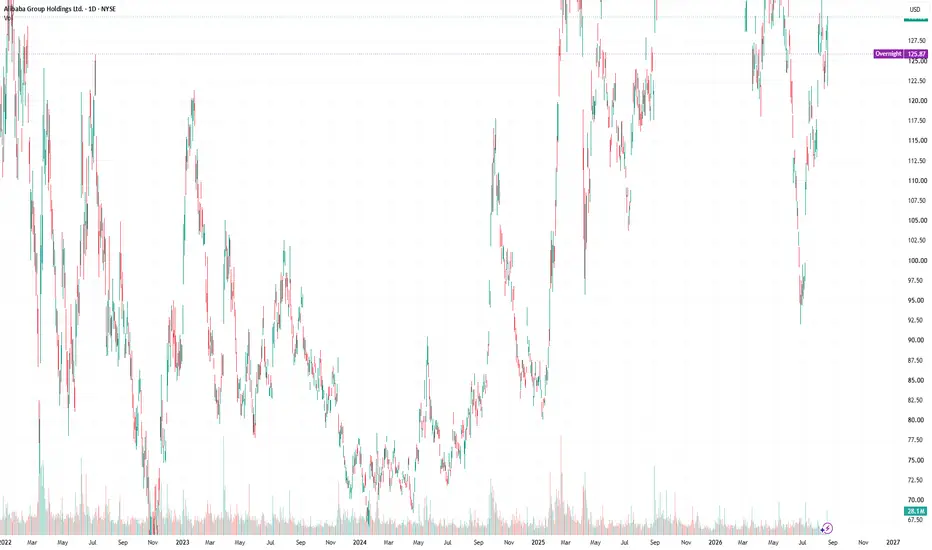
BABA offers an attractive risk/reward profile, with a target price of $170, implying approximately 37% upside from the current level.
Company Overview
Alibaba Group (BABA) is one of China’s largest technology companies, with operations spanning e-commerce, cloud computing, digital services, and payments.
The company operates some of the world’s largest online marketplaces, including Alibaba.com in B2B commerce, Taobao in C2C commerce, and Tmall in B2C retail. Through its affiliate Ant Group, Alibaba is also closely associated with Alipay, one of the world’s largest digital payment platforms, serving more than 1 billion users.
BABA
Share price at the time of analysis: $124.40
Target price: $170.00
Upside potential: 36.7%
Investment Thesis
1. Cloud and AI Could Become a Major Growth Catalyst
Alibaba’s Cloud and AI business remains one of the most underappreciated potential catalysts for the stock.
Management has outlined an ambitious long-term growth strategy for the segment, targeting a significant increase in annual revenue alongside improving profitability. Although the market appears skeptical about the scale of these targets, the risk/reward profile is becoming increasingly attractive.
Global demand for AI computing infrastructure continues to expand rapidly. At the same time, tighter U.S. restrictions on access to advanced AI technologies could encourage greater adoption of Chinese AI models and infrastructure, particularly in markets where cost efficiency is a priority.
Chinese AI models are also steadily narrowing the performance gap with leading U.S. alternatives while often competing aggressively on price. This creates a credible opportunity for Alibaba Cloud to gain market share and could ultimately support a higher valuation for the company’s Cloud and AI operations.
2. Potential Policy Support for Chinese Consumption
A renewed slowdown in China’s economic growth could increase the likelihood of additional government measures aimed at stimulating domestic consumption.
Alibaba, as the operator of one of China’s leading e-commerce ecosystems, would be a direct beneficiary of stronger consumer spending.
Recent stimulus measures have increasingly focused on categories such as household appliances and consumer electronics, both of which are important segments within Alibaba’s e-commerce ecosystem.
Additional policy support could therefore support GMV growth, improve monetization, and lead to upward revisions to revenue and earnings expectations.
3. A More Rational Competitive Environment
Alibaba could also benefit from Beijing’s efforts to curb excessive competition across China’s e-commerce and food-delivery industries.
A shift away from aggressive price competition and costly promotional activity would support the profitability of Alibaba’s core businesses.
If competitive intensity continues to moderate, Alibaba could see higher margins, stronger free cash flow generation, and greater earnings visibility over the coming quarters.
Conclusion: We maintain a bullish view on BABA. Alibaba’s current valuation does not appear to fully reflect the potential earnings contribution from its Cloud and AI operations, a recovery in China’s consumer environment, or the prospect of more rational competition across its core markets.
With a target price of $170, BABA offers approximately 37% upside from the current level. A sustained recovery in Cloud growth and profitability could become a key catalyst for a broader re-rating of the stock.

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.