
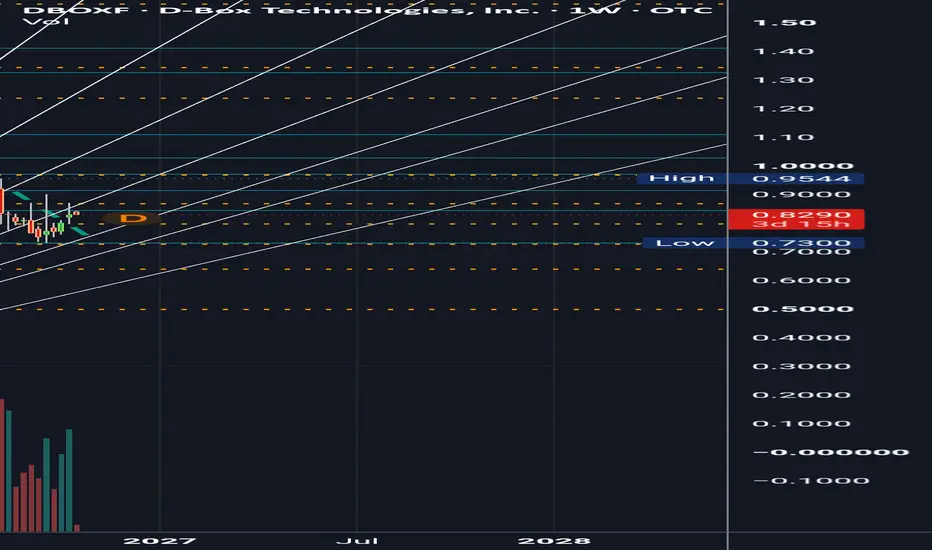
DBOXF is one of those rare early-cycle small-cap opportunities where share-price appreciation is supported by an actual operating transformation vs. speculation about a future product.
The company has moved from selling motion systems toward monetizing a growing installed base through recurring royalties, and fly wheel economics is starting to tell a different story. Revenue is expanding, operating leverage is becoming visible, and the balance sheet is substantially stronger.
The stock has appreciated ~180% over the past year but this should be a validation of the thesis, not a counterfactual. The underlying business is in the early stages of an earnings expansion cycle.
I'm comfortable with a 5 year price target of $80/sh, which puts the market cap at $18B. Current capex is funded entirely by royalty revenue. This is the precise formula for a small cap growing into a mid cap.

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.