
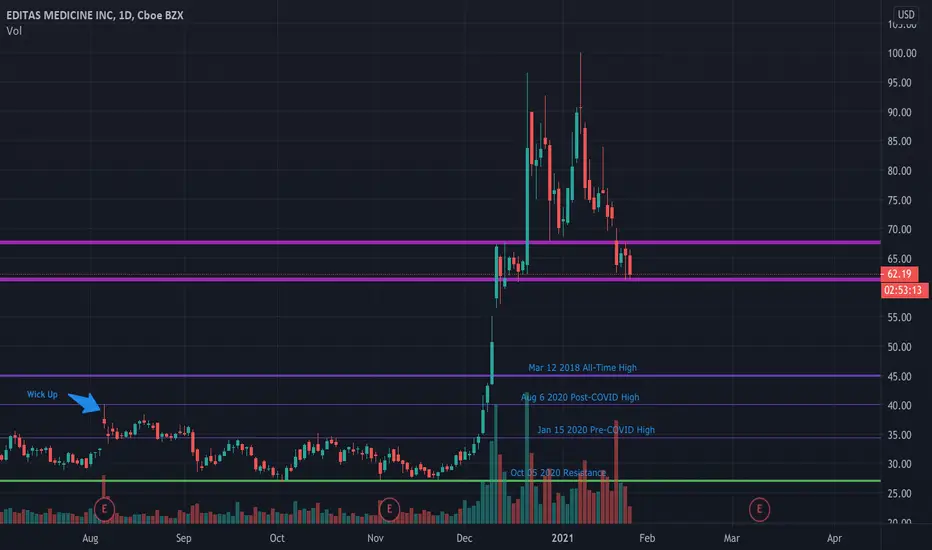
Clearly a lot of value has been lost in the past month. The CSO stepped down and analysts downgraded projected revenue. EDIT has very lucrative candidates in the pipeline treating sickle cell anemia. Long-term, this company will most certainly be profitable, with significant patent protection. This is a short term down draft that is consolidating, for the near term, around a non-speculation, fair price of $63.

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.