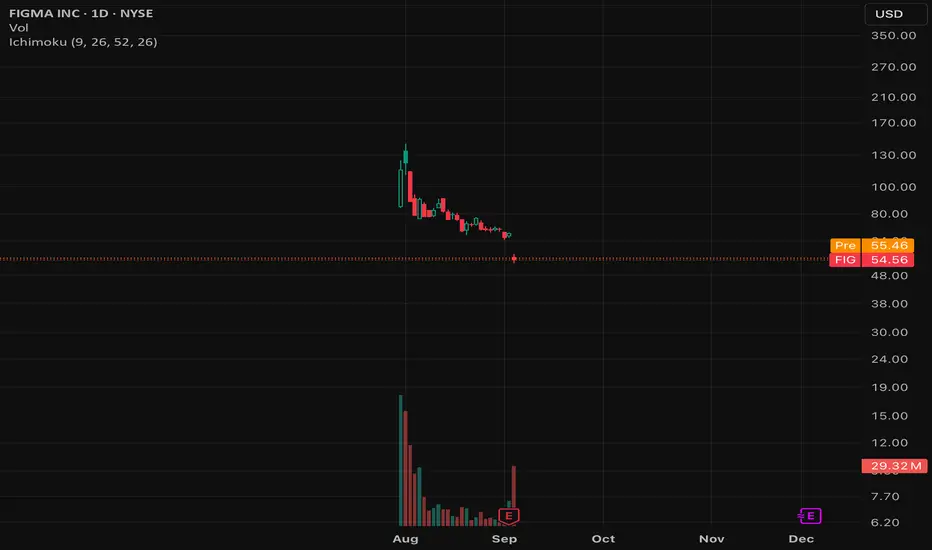
- Similar to  ASAN ,
 FIG has a good product, customer friendly, good UI/UX, easy to use.
- Valuation is out whack because IPO frenzy
- Things I like is their growth which 40%+ yoy but my concern is that the technical addressable market isn't huge for design space in general.
- Their are three broad archetype of users:
1. Who doesn't know design at all (majority) : these people use Canva or AI tool for quick designs and ideally these people want free tool.
2. Freelancers to Early professionals: This is the figma's core base where low learning curve help these customers to get started early and prototype faster.
3. Mid career professionals: These folks are open to using new tools if it makes their life easier.
4. Hardcore professionals with years of experience : This segment want heavy editing capability and are mostly ADBE hardcore users. They know ins and out of ADBE suite. They might not easily switch to FIG because FIG feature capability isn't extensive enough what a full blown ADBE product offers.
FIG has strong foothold in type 1-3 is going after type 4. But my concern is even if I combine all the types market isn't large enough as the majority ( say noobs ) will always prefer a free tool and ideally some sort of AI generated edits
ASAN , FIG has a good product, customer friendly, good UI/UX, easy to use. - Valuation is out whack because IPO frenzy
- Things I like is their growth which 40%+ yoy but my concern is that the technical addressable market isn't huge for design space in general.
- Their are three broad archetype of users:
1. Who doesn't know design at all (majority) : these people use Canva or AI tool for quick designs and ideally these people want free tool.
2. Freelancers to Early professionals: This is the figma's core base where low learning curve help these customers to get started early and prototype faster.
3. Mid career professionals: These folks are open to using new tools if it makes their life easier.
4. Hardcore professionals with years of experience : This segment want heavy editing capability and are mostly
ADBE hardcore users. They know ins and out of ADBE suite. They might not easily switch to FIG because FIG feature capability isn't extensive enough what a full blown ADBE product offers. FIG has strong foothold in type 1-3 is going after type 4. But my concern is even if I combine all the types market isn't large enough as the majority ( say noobs ) will always prefer a free tool and ideally some sort of AI generated edits노트
For me, I like the company but it's not a buy for me at these levels as fundamentals are out of whack. It has good earning growth but that would come down sharply as technical addressable market isn't huge. As of now, they are eating low hanging ADBE customers. 노트
I will think about it if it goes below $30 bucks or they expand their TAM by adding new products which gives me confidence that high double digit growth is sustainable for the next 5 years노트
Insiders have yet to unload their shares which they are holding. Almost all insiders had stock based compensation which has paper money for years. Their stock selling window is getting opened which will keep pressure on stock price imo노트
Already -20% from the call out if you thought that was the bottom노트
Earnings on Nov 6, 2025 was okay but the valuation is still very rich. FIG IPO was so fluffed up노트
-25% down from the call out노트
- Fig makes 1 billion per year as revenue, net income is negative i.e they operate in loss.- Current, market cap ~ 19 B
- Fair market cap should be max of 8 billion

노트
- FIG market cap is around $14.65B on Jan 17, 2026 and closing share price $29.59노트
- FIG is high percentage grower therefore 8-10x revenue is fair for the stock which puts it at around $8-10B market cap company. - That means bottom is most likely -31-42% lower than $29.59
- Fair value of the stock $17-20
노트
- Almost 50% down from the point I alerted거래청산: 스탑 닿음
Closing short @ 28.xx노트
Almost 50% profit노트
We are long since the sub 20s which we accumulated during saasoclypse!
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.