
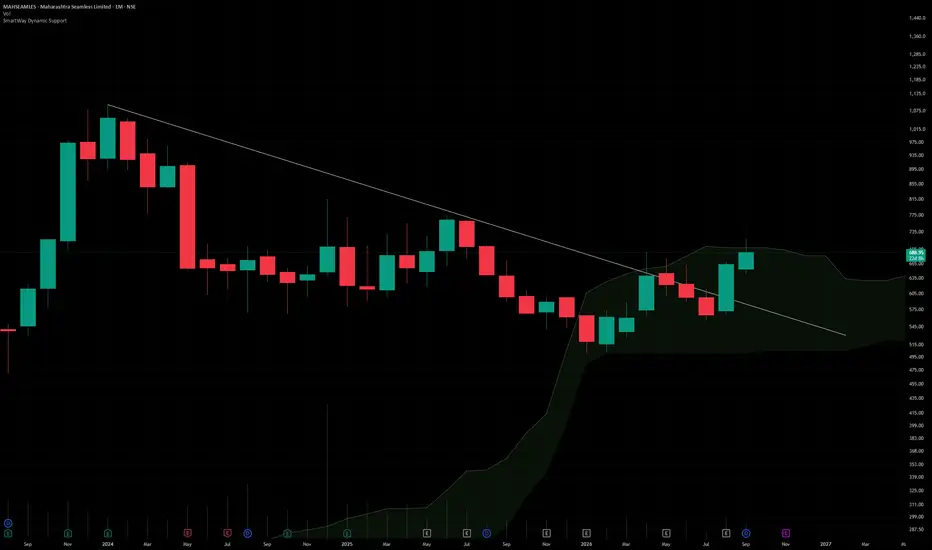
## Maharashtra Seamless Ltd. (CMP ₹689.00, NSE: MAHSCO)
**The SmartWay Research Desk | 8 September 2026**
A Mumbai‑based steel pipe## Maharashtra Seamless Ltd. (CMP ₹689.00, NSE: MAHSCOOTER)
**The SmartWay Research Desk | 8 September 2026**
A Mumbai‑based steel pipe manufacturer, incorporated in 1988. Maharashtra Seamless Ltd. is India’s largest producer of **seamless pipes, ERW pipes, and coated pipes**, catering to industries such as oil & gas, power, automotive, and infrastructure. The company is part of the DP Jindal Group and has manufacturing facilities in Maharashtra and Haryana.
**Promoter Holding (Jun 2026):** **DP Jindal Group (Jindal Family) — ~63.2% stake (no pledges)**
---
### FY22–FY26 Snapshot
- **Revenue Growth:** FY26 revenue ₹5,842 Cr vs ₹5,112 Cr in FY25 (+14.3% YoY). → **Good**
- **Net Profit:** FY26 PAT ₹812 Cr vs ₹702 Cr in FY25 (+15.7% YoY). → **Good**
- **Operating Margin:** FY26 EBITDA ₹1,412 Cr, margin 24.2% vs 23.5% last year (+70 bps). → **Good**
- **Equity Capital:** Stable, face value ₹5. → **Good**
- **Dividend Policy:** Dividend ₹6.00/share declared for FY26. → **Good**
- **Asset Building:** Investments in **capacity expansion, coated pipes, and offshore projects**. → **Good**
- **Sales:** Strong demand from **oil & gas and infra sectors**. → **Good**
- **Expense:** Raw material cost pressures (steel, alloys) remain. → **Neutral/Good**
- **EPS:** FY26 EPS ₹26.25 vs ₹22.40 last year (+17.2%). → **Good**
---
### Institutional Interest & Ownership Trends (Jun 2026)
- **Promoter Holding:** ~63.2% (no pledges)
- **FII Holding:** ~12.8%
- **DII Holding:** ~14.6%
- **Retail & Others:** ~9.4%
---
### Strategic Moves & Innovations
- Expansion in **seamless and ERW pipe capacity**.
- Focus on **oil & gas exploration and offshore projects**.
- Partnerships with **global energy companies for supply contracts**.
- Diversification into **coated pipes and specialized industrial products**.
---
### Cash Flow & Balance Sheet Strength
- Market cap ~₹11,200 Cr.
- Debt‑to‑equity ratio ~0.42 (moderate leverage).
- Book value per share ₹182.00; P/B ~3.8.
- EPS (TTM) ₹26.25; P/E ~26.2.
---
### Risk Factors
- Moderate‑high **P/E ratio ~26.2**, valuations slightly expensive.
- Dependence on **oil & gas demand cycles**.
- Exposure to **commodity price volatility (steel, alloys)**.
- Competition from Ratnamani Metals, Welspun Corp, and Jindal SAW.
---
### Investor Takeaway
Maharashtra Seamless has delivered **robust FY26 performance**, supported by demand in oil & gas, infra projects, and coated pipe expansion. With strong promoter backing (Jindal Family, 63.2% stake), dividend payouts, and leadership in seamless pipes, the company remains a **mid‑cap steel & infra play**. At CMP ₹689.00, valuations are **moderately expensive (P/E ~26.2, P/B ~3.8)**, reflecting growth expectations with manageable risks.
**The SmartWay Research Desk | 8 September 2026**
A Mumbai‑based steel pipe## Maharashtra Seamless Ltd. (CMP ₹689.00, NSE: MAHSCOOTER)
**The SmartWay Research Desk | 8 September 2026**
A Mumbai‑based steel pipe manufacturer, incorporated in 1988. Maharashtra Seamless Ltd. is India’s largest producer of **seamless pipes, ERW pipes, and coated pipes**, catering to industries such as oil & gas, power, automotive, and infrastructure. The company is part of the DP Jindal Group and has manufacturing facilities in Maharashtra and Haryana.
**Promoter Holding (Jun 2026):** **DP Jindal Group (Jindal Family) — ~63.2% stake (no pledges)**
---
### FY22–FY26 Snapshot
- **Revenue Growth:** FY26 revenue ₹5,842 Cr vs ₹5,112 Cr in FY25 (+14.3% YoY). → **Good**
- **Net Profit:** FY26 PAT ₹812 Cr vs ₹702 Cr in FY25 (+15.7% YoY). → **Good**
- **Operating Margin:** FY26 EBITDA ₹1,412 Cr, margin 24.2% vs 23.5% last year (+70 bps). → **Good**
- **Equity Capital:** Stable, face value ₹5. → **Good**
- **Dividend Policy:** Dividend ₹6.00/share declared for FY26. → **Good**
- **Asset Building:** Investments in **capacity expansion, coated pipes, and offshore projects**. → **Good**
- **Sales:** Strong demand from **oil & gas and infra sectors**. → **Good**
- **Expense:** Raw material cost pressures (steel, alloys) remain. → **Neutral/Good**
- **EPS:** FY26 EPS ₹26.25 vs ₹22.40 last year (+17.2%). → **Good**
---
### Institutional Interest & Ownership Trends (Jun 2026)
- **Promoter Holding:** ~63.2% (no pledges)
- **FII Holding:** ~12.8%
- **DII Holding:** ~14.6%
- **Retail & Others:** ~9.4%
---
### Strategic Moves & Innovations
- Expansion in **seamless and ERW pipe capacity**.
- Focus on **oil & gas exploration and offshore projects**.
- Partnerships with **global energy companies for supply contracts**.
- Diversification into **coated pipes and specialized industrial products**.
---
### Cash Flow & Balance Sheet Strength
- Market cap ~₹11,200 Cr.
- Debt‑to‑equity ratio ~0.42 (moderate leverage).
- Book value per share ₹182.00; P/B ~3.8.
- EPS (TTM) ₹26.25; P/E ~26.2.
---
### Risk Factors
- Moderate‑high **P/E ratio ~26.2**, valuations slightly expensive.
- Dependence on **oil & gas demand cycles**.
- Exposure to **commodity price volatility (steel, alloys)**.
- Competition from Ratnamani Metals, Welspun Corp, and Jindal SAW.
---
### Investor Takeaway
Maharashtra Seamless has delivered **robust FY26 performance**, supported by demand in oil & gas, infra projects, and coated pipe expansion. With strong promoter backing (Jindal Family, 63.2% stake), dividend payouts, and leadership in seamless pipes, the company remains a **mid‑cap steel & infra play**. At CMP ₹689.00, valuations are **moderately expensive (P/E ~26.2, P/B ~3.8)**, reflecting growth expectations with manageable risks.

Sucrit.D.Patil
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
Sucrit.D.Patil
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.