
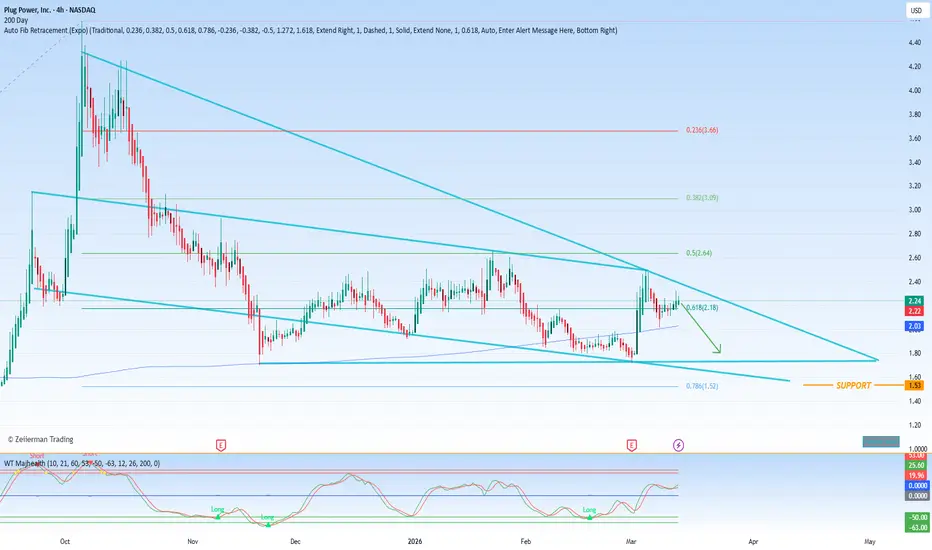
Plug Power Inc. (NASDAQ: PLUG), a pioneering force in the hydrogen fuel cell industry, finds itself at a critical juncture as it navigates a complex landscape of strategic transformation, mixed financial results, and external market pressures. The Latham, New York-based company, founded in 1997, has long been a bellwether for the clean energy sector's promise and peril. Recent developments, however, paint a picture of a company in transition—shifting its business model, showing signs of operational improvement, yet still facing significant skepticism from Wall Street and volatility from global events.
Analyst Actions: A Tale of Two Outlooks
The contrasting opinions from two major financial institutions perfectly encapsulate the uncertainty surrounding Plug Power's future.
On one hand, BMO Capital Markets struck a decidedly cautious tone. On March 3, following the release of Plug Power's fourth-quarter results, BMO analyst Ameet Thakkar lowered the firm's price target on PLUG to $1.00 from $1.30. The analyst maintained an Underperform rating, signaling a belief that the stock will likely lag behind the broader market. This downgrade reflects a nuanced view of the company's evolving strategy. BMO noted that Plug Power is pivoting away from its previous ambition of being a primary merchant of green hydrogen. Instead, it is repositioning itself as a more focused hydrogen application provider, concentrating on its core strengths in fuel cell systems and electrolyzer technology for specific use cases like material handling. While this strategic refocusing could lead to a more sustainable business model, BMO's price target cut suggests the market is still waiting for tangible proof of profitability. However, the analyst did acknowledge a potential silver lining: management's indication that asset sales and a significant reduction in capital expenditures planned for 2026 should help alleviate the persistent pressure to seek additional, and potentially dilutive, equity financing.
Conversely, Wells Fargo offered a slightly more optimistic, albeit still guarded, perspective. On March 4, the firm increased its price target on Plug Power to $2.00 from $1.50 while maintaining an Equal Weight rating. This adjustment came on the heels of what the firm described as a "mixed" quarterly report. The optimism was fueled by a clear beat on top-line revenue expectations and, crucially, a return to positive gross margins during the fourth quarter—a key metric that signals improving fundamental economics. However, this positive news was tempered by the company's outlook for 2026. Wells Fargo noted that Plug Power's revenue growth guidance for the coming year came in below consensus expectations, suggesting that while the company is making progress on operational efficiency, the pace of top-line expansion may be slower than the market had hoped for.
Financial Health: A Story of Improvement and Cautious Guidance
The underlying financial results from Plug Power's fourth-quarter and full-year 2025 report provide the context for these analyst moves. The company reported that revenue for 2025 increased by approximately 13% compared to the prior year, a growth trajectory driven primarily by robust demand in its legacy material handling business (GenDrive) and its newer, high-growth electrolyzer segment (GenEco).
The fourth-quarter results were particularly noteworthy for their year-over-year improvements in profitability metrics:
Revenue: The company posted Q4 revenue of $225.2 million, comfortably beating consensus estimates of $217.4 million.
Earnings Per Share (EPS): On a GAAP basis, the net loss per share narrowed significantly to negative $0.63, a dramatic improvement from the negative $1.48 reported in the same period of 2024. Even more striking was the adjusted EPS, which improved to a loss of just negative $0.06 from a loss of negative $0.29, indicating that core operational losses are shrinking rapidly.
Gross Margin: The company highlighted a massive 125 percentage-point improvement in gross margin, a testament to the cost-cutting and pricing power initiatives enacted under its internal efficiency program.
Looking ahead, Plug Power's management has laid out a roadmap that prioritizes financial discipline and a path to profitability over explosive growth. The company expects 2026 revenue growth to remain broadly in line with the 13% achieved in 2025, once again led by material handling and electrolyzer sales. The real focus, however, is on the bottom line. Management has reiterated its ambitious target of achieving positive EBITDA (earnings before interest, taxes, depreciation, and amortization) in the fourth quarter of 2026. This is a critical milestone on a broader roadmap that aims for operating profitability by 2027 and full, sustainable profitability by 2028.
These targets are underpinned by the company's ongoing Project Quantum Leap, a sweeping cost reduction and operational optimization initiative. The company reported that in 2025, this project delivered significant results, including workforce streamlining, facilities consolidation, successful price increases, and a reduction in working capital requirements. Further initiatives are planned for 2026 to accelerate the path to profitability and strengthen the company's financial foundation.
The Market's Mood: Geopolitics and Short Squeezes Create Volatility
Despite the fundamentally improving story, Plug Power's stock remains a playground for volatile trading, heavily influenced by factors beyond the company's direct control.
Most recently, shares have been under pressure due to escalating geopolitical tensions. A flare-up in the Middle East, including reports of Iranian drone attacks on regional energy infrastructure and heightened military posturing, has injected a fresh wave of risk-off sentiment into global markets. This environment typically hits high-beta, speculative names like Plug Power the hardest, as investors flee to the safety of traditional assets. The uncertainty surrounding energy prices and global stability can quickly overshadow company-specific progress for stocks in the nascent clean energy sector.
This recent downturn stands in stark contrast to the price action seen just days earlier, following the earnings report. In early March, PLUG stock experienced a sharp surge. This rally was fueled by a combination of the positive earnings news and a classic short squeeze. With more than a quarter of the company's tradable float sold short, the positive earnings report forced many bearish investors to rush and cover their positions, rapidly accelerating the stock's upward momentum.
Over the past 12 months, Plug Power's share price has been a study in extremes. It has swung from a low of around $0.70 in the spring of 2025 to a peak near $4.13 in the fall, before pulling back again. As of mid-March, the stock appeared to be in a period of consolidation, trading near its key moving averages. However, the most recent geopolitical news sent shares down 3.76% to $2.05 on a recent Monday, a stark reminder of the stock's sensitivity to both internal progress and external shocks.
In summary, Plug Power is a company making genuine strides in operational efficiency and narrowing its strategic focus. It has a clear, if gradual, path toward profitability. However, it remains at the mercy of a skeptical Wall Street, a highly shorted float, and a global macroeconomic environment that can turn on a dime. The coming quarters will be critical in determining whether the company's "Quantum Leap" can finally translate into consistent, long-term shareholder value.

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.