
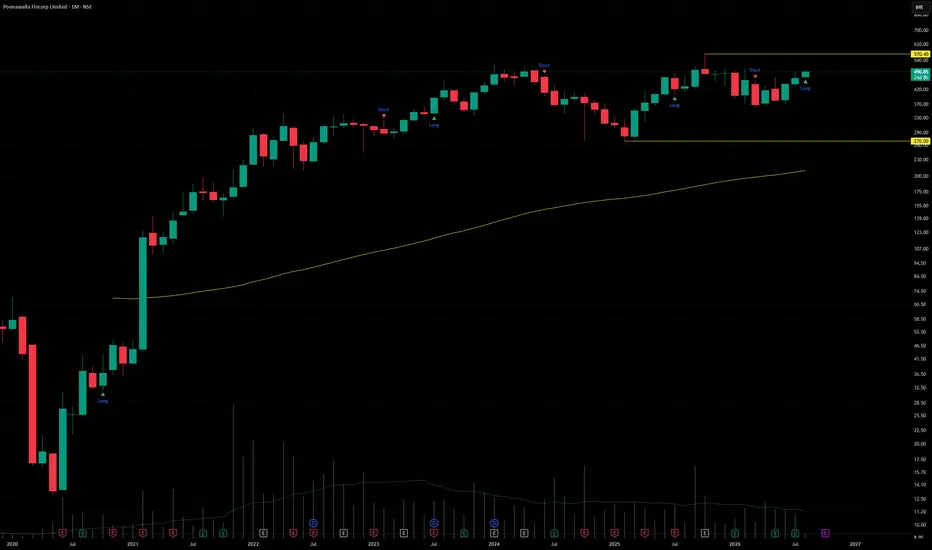
Poonawalla Fincorp Ltd. (CMP ₹490.00, NSE: POONAWALLA)
The SmartWay Research Desk | 7 August 2026
A Pune‑based NBFC, incorporated in 1984 (formerly Magma Fincorp, rebranded after acquisition by the Poonawalla Group). The company operates across consumer loans, MSME financing, personal loans, business loans, and digital lending solutions, with a strong focus on technology‑driven retail credit.
Promoter Holding (Mar 2026): Cyrus Poonawalla Group — 62.9% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹3,842 Cr vs ₹3,212 Cr in FY25 (+19.6% YoY). → Good
Net Profit: FY26 PAT ₹1,012 Cr vs ₹842 Cr in FY25 (+20.2% YoY). → Good
Operating Margin: FY26 EBITDA ₹1,812 Cr, margin 47.2% vs 46.0% last year (+120 bps). → Good
Equity Capital: Stable, face value ₹2. → Good
Dividend Policy: Dividend ₹6.00/share declared for FY26. → Good
Asset Building: Investments in digital lending platforms and AI‑driven credit scoring. → Good
Sales: Strong demand from personal loans and MSME financing. → Good
Expense: Credit costs remain under control; GNPA ~1.5%. → Neutral/Good
EPS: FY26 EPS ₹24.25 vs ₹20.15 last year (+20.3%). → Good
Institutional Interest & Ownership Trends (Mar 2026)
Promoter Holding: 62.9% (no pledges)
FII Holding: 14.12%
DII Holding: 15.34%
Retail & Others: 7.64%
Strategic Moves & Innovations
Expansion in digital lending and fintech partnerships.
Focus on MSME financing and personal loan growth.
Partnerships with banks and fintechs for co‑lending.
Diversification into secured loans and credit cards (pilot stage).
Cash Flow & Balance Sheet Strength
Market cap ~₹38,200 Cr.
Debt‑to‑equity ratio ~3.2 (typical NBFC leverage).
Book value per share ₹182.40; P/B ~2.7.
EPS (TTM) ₹24.25; P/E ~20.2.
Risk Factors
Moderate P/E ratio ~20.2, valuations fair.
Dependence on retail credit demand and interest rate cycles.
Exposure to regulatory changes in RBI norms for NBFCs.
Competition from Bajaj Finance, Aditya Birla Capital, and L&T Finance.
Investor Takeaway
Poonawalla Fincorp has delivered robust FY26 performance, supported by digital lending expansion, MSME financing, and strong credit discipline. With promoter backing, dividend payouts, and leadership in retail NBFC space, Poonawalla Fincorp remains a mid‑cap financial services growth play. At CMP ₹490.00, valuations are reasonable (P/E ~20.2, P/B ~2.7), offering balanced risk‑reward.
The SmartWay Research Desk | 7 August 2026
A Pune‑based NBFC, incorporated in 1984 (formerly Magma Fincorp, rebranded after acquisition by the Poonawalla Group). The company operates across consumer loans, MSME financing, personal loans, business loans, and digital lending solutions, with a strong focus on technology‑driven retail credit.
Promoter Holding (Mar 2026): Cyrus Poonawalla Group — 62.9% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹3,842 Cr vs ₹3,212 Cr in FY25 (+19.6% YoY). → Good
Net Profit: FY26 PAT ₹1,012 Cr vs ₹842 Cr in FY25 (+20.2% YoY). → Good
Operating Margin: FY26 EBITDA ₹1,812 Cr, margin 47.2% vs 46.0% last year (+120 bps). → Good
Equity Capital: Stable, face value ₹2. → Good
Dividend Policy: Dividend ₹6.00/share declared for FY26. → Good
Asset Building: Investments in digital lending platforms and AI‑driven credit scoring. → Good
Sales: Strong demand from personal loans and MSME financing. → Good
Expense: Credit costs remain under control; GNPA ~1.5%. → Neutral/Good
EPS: FY26 EPS ₹24.25 vs ₹20.15 last year (+20.3%). → Good
Institutional Interest & Ownership Trends (Mar 2026)
Promoter Holding: 62.9% (no pledges)
FII Holding: 14.12%
DII Holding: 15.34%
Retail & Others: 7.64%
Strategic Moves & Innovations
Expansion in digital lending and fintech partnerships.
Focus on MSME financing and personal loan growth.
Partnerships with banks and fintechs for co‑lending.
Diversification into secured loans and credit cards (pilot stage).
Cash Flow & Balance Sheet Strength
Market cap ~₹38,200 Cr.
Debt‑to‑equity ratio ~3.2 (typical NBFC leverage).
Book value per share ₹182.40; P/B ~2.7.
EPS (TTM) ₹24.25; P/E ~20.2.
Risk Factors
Moderate P/E ratio ~20.2, valuations fair.
Dependence on retail credit demand and interest rate cycles.
Exposure to regulatory changes in RBI norms for NBFCs.
Competition from Bajaj Finance, Aditya Birla Capital, and L&T Finance.
Investor Takeaway
Poonawalla Fincorp has delivered robust FY26 performance, supported by digital lending expansion, MSME financing, and strong credit discipline. With promoter backing, dividend payouts, and leadership in retail NBFC space, Poonawalla Fincorp remains a mid‑cap financial services growth play. At CMP ₹490.00, valuations are reasonable (P/E ~20.2, P/B ~2.7), offering balanced risk‑reward.

Sucrit.D.Patil
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
Sucrit.D.Patil
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.