
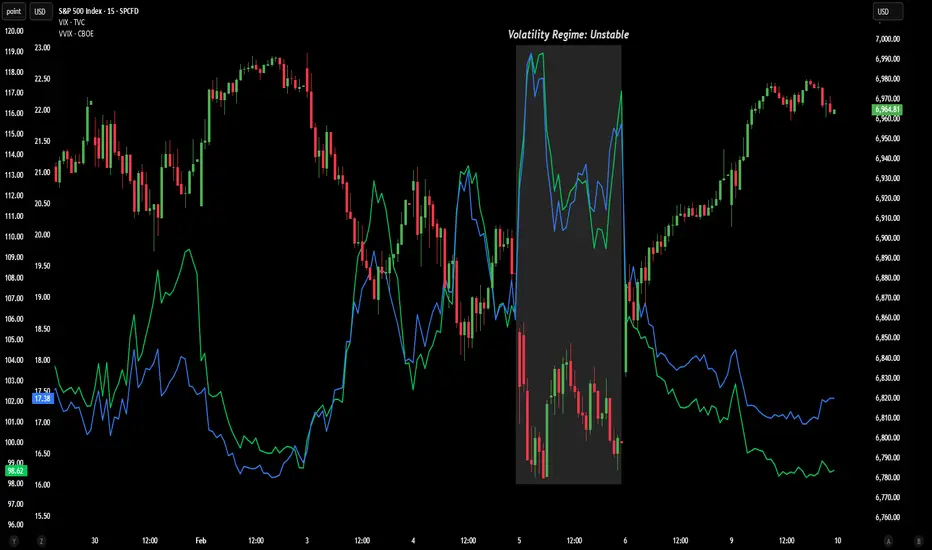
This is the first in a five-part series on volatility, structure, and decision-making in the S&P 500.
Each note focuses on a single principle that governs when participation is justified—not on setups, signals, or trade outcomes.
The intent is not to predict direction, but to clarify eligibility: understanding the conditions under which decisions are worth making at all.
________________________________________________
Most traders treat volatility as a reaction to price.
Institutions treat volatility as a condition for participation.
That distinction explains a large percentage of failed trades.
Volatility answers how the market is behaving, not where it is going.
When VIX is compressing, expansion trades tend to fail—even if direction appears obvious.
When VVIX is rising while VIX is flat, instability is increasing beneath the surface—often before price resolves.
This is why directional bias without volatility context is incomplete.
On the chart, note how price movement that looks impulsive often stalls or reverses when volatility regimes are misaligned. The trade didn’t fail because direction was wrong—it failed because conditions were wrong.
Professional decision-making starts with a simple question:
Is the market in a state that supports participation at all?
Only after volatility conditions are understood does direction become meaningful.
________________________________________
Key takeaway:
Direction without volatility context is guessing.
Volatility defines whether opportunity exists in the first place.

The Volatility Engine. Research notes and tools focused on volatility, market structure, and decision context in the S&P 500. TheVolatilityEngines.com
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
The Volatility Engine. Research notes and tools focused on volatility, market structure, and decision context in the S&P 500. TheVolatilityEngines.com
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.