
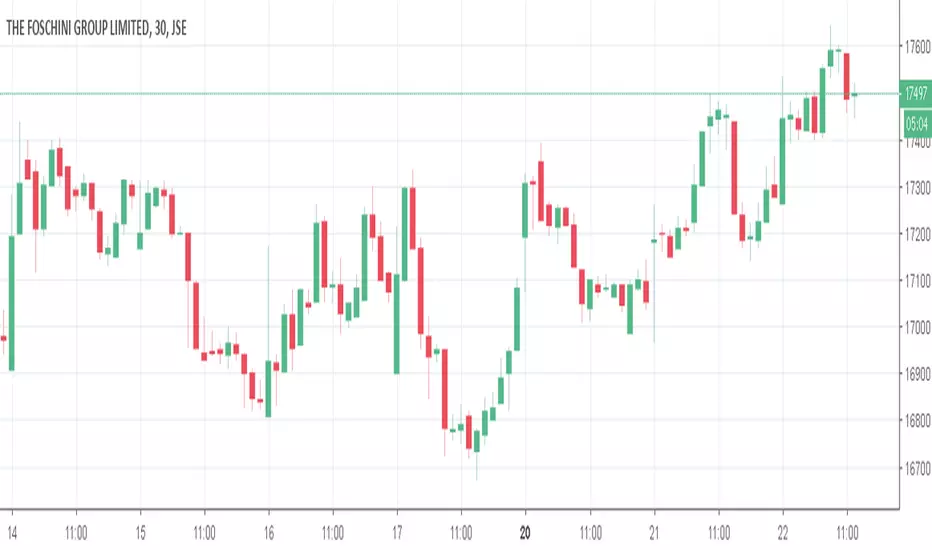
With the petrol price increasing, tax increased this year results on a lot of financial pressure on the south african consumer leaving consumers with a lower disposable income. In time of lower disposable income it is natural in an economic sense that there would be an increase on credit purchases from consumers.
With this being said. I think TFG is best positioned for a long on retailers as they reported 7% increase in credit sales together with a decrease in irrevocable debt. This gives me an indication that TFG does collect most debt and they do it quite fast as they have the highest interests rate on debitors with 19%. This is a risk management strategy they use to collect debt as soon as possible from debitors. The faster they collect debt the stornger the balance sheet and the stronger the share price should be theoretically.
Therefore, I remain bullish on the stock.
Here is what I plan to do:
Buy: 174-176
TP: 190
SL: 169

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.