
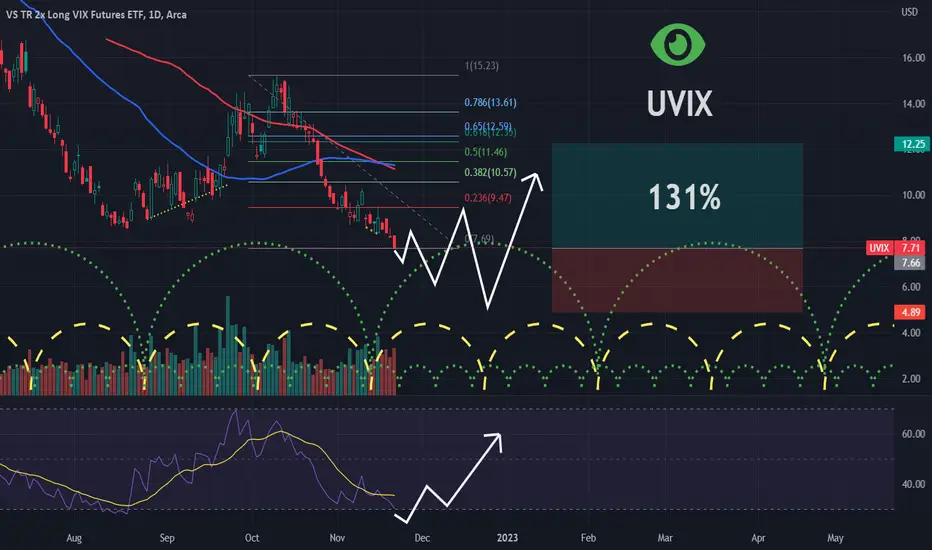
The index measures the daily performance of a portfolio of long positions in first and second month VIX futures contracts. This theoretical portfolio is rolled each day to maintain a consistent time to maturity of the futures contracts. The index is calculated daily at 4:00 p.m. (Eastern time) and at a value calculated from the average price for the futures contracts between 3:45 p.m. (Eastern time) and 4:00 p.m. (Eastern time).
액티브 트레이드
Big move coming from the VIX (Volatility Index)I've played this well with the UVIX ETF (Shares or Options)
Good Luck Traders and Investors!
노트
LOOOOADDDIINNNNGGGGG Time!액티브 트레이드
This chart is still active, but I need to redo after the reverse split last week.
99% of the market trades the noise. I trade the math. Professional divergence hunter and volume tracker. Enter the Seeker Lab:
linktr.ee/DivergenceSeeker
linktr.ee/DivergenceSeeker
관련 발행물
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.