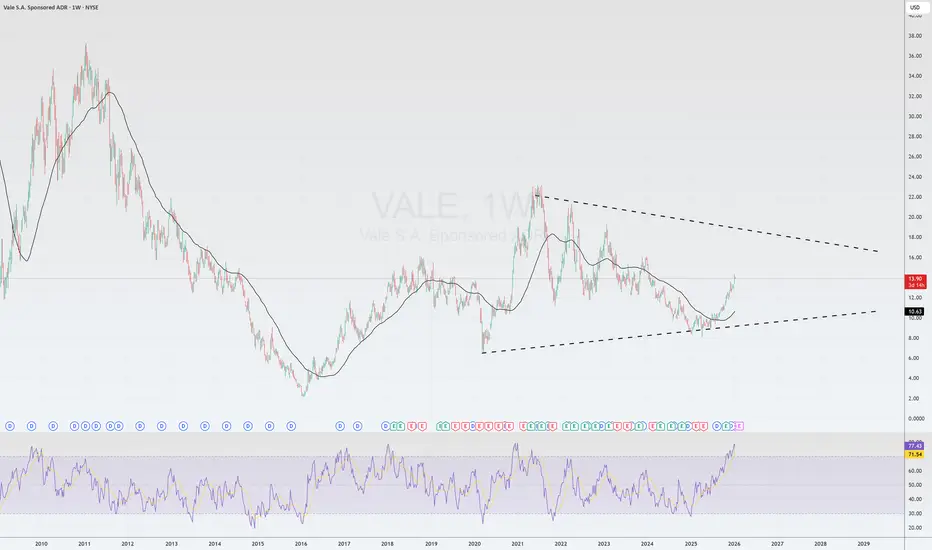
 VALE: Thesis for 2026
1. Strategic Pivot: From Iron Ore Proxy to Base Metals Leader
The most significant development for Vale in 2026 is the transformation of its base metals segment (nickel and copper) from a secondary unit into a primary profit engine.
Nickel Supply Shock: Indonesia, which controls over 50% of global supply, has implemented a 34% production cut for 2026. This has already triggered a >25% price surge within a month.
EBITDA Outperformance: This supply-side pressure could increase Vale’s consolidated EBITDA by ~8%. Current projections suggest the non-ferrous division could exceed $4 billion in EBITDA for 2026, significantly outperforming market consensus of $3 billion.
Copper Growth: Vale’s copper production is forecasted to grow at a 7% CAGR through 2035, outstripping global peers. Strategic moves, such as the Glencore joint venture in the Sudbury Basin, solidify this growth trajectory.
2. Operational Excellence and Cost Leadership
🔎

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.