
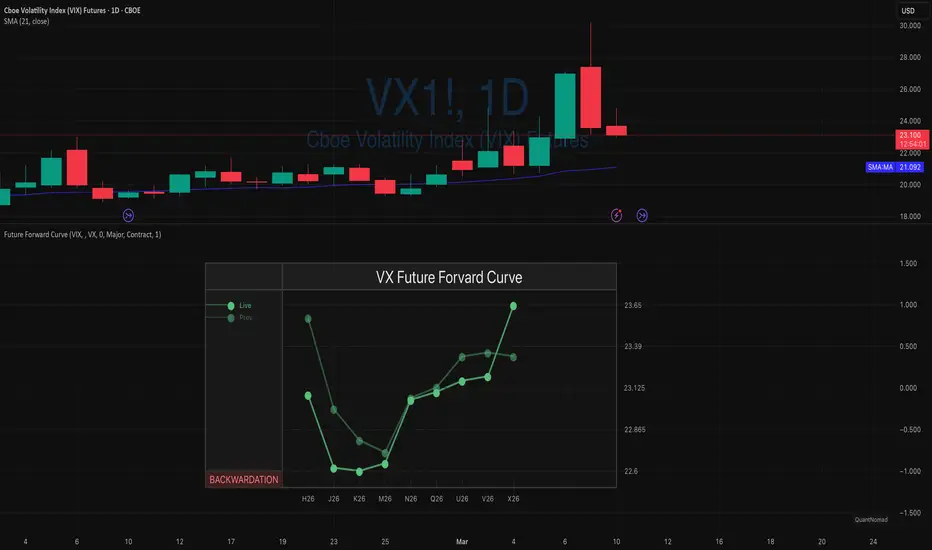
After the sharp spike in volatility, the VX forward curve is gradually returning to a more typical shape.
This kind of rapid normalization often suggests the market is pricing a temporary volatility event rather than a prolonged risk regime.
Disclaimer:
This analysis is for educational purposes only and reflects personal market observations. It does not constitute investment, financial, or trading advice. Always conduct your own research before making trading decisions.
- Back-end futures are already back in contango
- Front-end backwardation compressing quickly as spot VIX declines
This kind of rapid normalization often suggests the market is pricing a temporary volatility event rather than a prolonged risk regime.
Disclaimer:
This analysis is for educational purposes only and reflects personal market observations. It does not constitute investment, financial, or trading advice. Always conduct your own research before making trading decisions.

Quant Developer | Pine Script v6 | Python & R
12+ yrs system. trading, hedge fund experience
Indicators, strategies & screeners
Futures & options
💼 Hire/Consulting:
qntly.com/hire
🎓 Pine Code With AI:
qntly.com/pineai
12+ yrs system. trading, hedge fund experience
Indicators, strategies & screeners
Futures & options
💼 Hire/Consulting:
qntly.com/hire
🎓 Pine Code With AI:
qntly.com/pineai
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.