OPEN-SOURCE SCRIPT
Kalman Trend State [forexobroker]
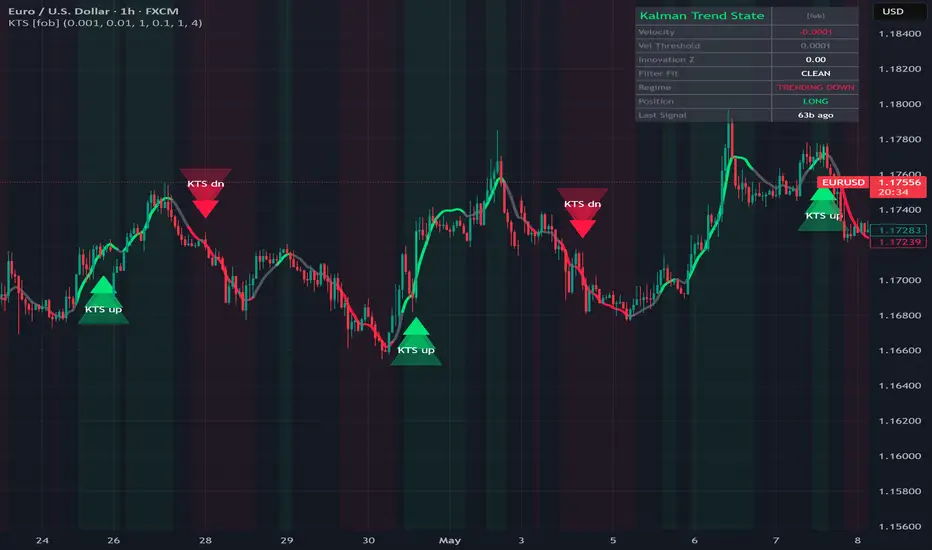
Kalman Trend State applies a recursive Kalman filter to price, treating the unobserved trend as a hidden state with two components: instantaneous price level and per-bar velocity. Unlike a moving average, the filter's smoothing gain updates bar-by-bar from the residuals (innovation), so it adapts to volatility automatically without any length knob.
🔶 ALGORITHM
1. State [px, vx] tracks price and velocity. Transition F = [[1,1],[0,1]] (constant-velocity model).
2. Process noise Q is ATR-adaptive: Q = q_base + q_scale * (ATR / close). Higher volatility = larger Q = faster adaptation.
3. Measurement noise R is fixed (user input). Higher R = filter trusts the model more, smoother output.
4. At each bar: predict (px, P) -> measure close -> update gain K = P_pred * H' / S where S = P_pred[0,0] + R -> correct (px, vx, P).
5. The innovation z-score (close - prediction) / sigma quantifies how well the filter is tracking.
🔶 SIGNAL LOGIC
- Buy: velocity > k * ATR AND |innovation z| <= sigma gate AND close crosses Kalman line up AND not already long AND cooldown elapsed AND barstate.isconfirmed.
- Sell: mirror with velocity < -k * ATR.
- Position-lock state machine prevents same-side over-firing.
🔶 INPUTS
- Process Noise Base Q (default 0.001)
- Q ATR-Pct Scale (default 0.01)
- Measurement Noise R (default 1.0)
- Velocity Threshold x ATR (default 0.10)
- Innovation Sigma Gate (default 1.0)
- Cooldown Bars (default 4)
- Visual: 3-layer glow toggle, Kalman line toggle, dashboard toggle, buy / sell colors
🔶 ALERTS
KTS Buy, KTS Sell, KTS Any Signal, KTS Trend Up Start, KTS Trend Down Start, KTS Clean Fit, KTS Cross Up, KTS Cross Down, KTS Webhook JSON.
🔶 LIMITATIONS
- Kalman is optimal under linear-Gaussian assumptions; price is heavy-tailed, so the filter occasionally lags during regime breaks.
- Warm-up: about 14 bars (ATR seed). Earlier bars have NaN-guarded fallbacks but signals stay flat.
- Defaults tuned for liquid majors and indices on 5m-1H. Re-tune R for tick-driven micro-instruments.
- Velocity threshold scales with ATR but the filter itself does not change shape; for highly seasonal assets, a session-aware variant may help.
오픈 소스 스크립트
트레이딩뷰의 진정한 정신에 따라, 이 스크립트의 작성자는 이를 오픈소스로 공개하여 트레이더들이 기능을 검토하고 검증할 수 있도록 했습니다. 작성자에게 찬사를 보냅니다! 이 코드는 무료로 사용할 수 있지만, 코드를 재게시하는 경우 하우스 룰이 적용된다는 점을 기억하세요.

🔵Gain access to our powerful tools : kestutisbalciunas.com/tradingview/
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
오픈 소스 스크립트
트레이딩뷰의 진정한 정신에 따라, 이 스크립트의 작성자는 이를 오픈소스로 공개하여 트레이더들이 기능을 검토하고 검증할 수 있도록 했습니다. 작성자에게 찬사를 보냅니다! 이 코드는 무료로 사용할 수 있지만, 코드를 재게시하는 경우 하우스 룰이 적용된다는 점을 기억하세요.
🔵Gain access to our powerful tools : kestutisbalciunas.com/tradingview/
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.