OPEN-SOURCE SCRIPT
VWAP Mean Reversion Strategy Range Bound Forex RSI Volume
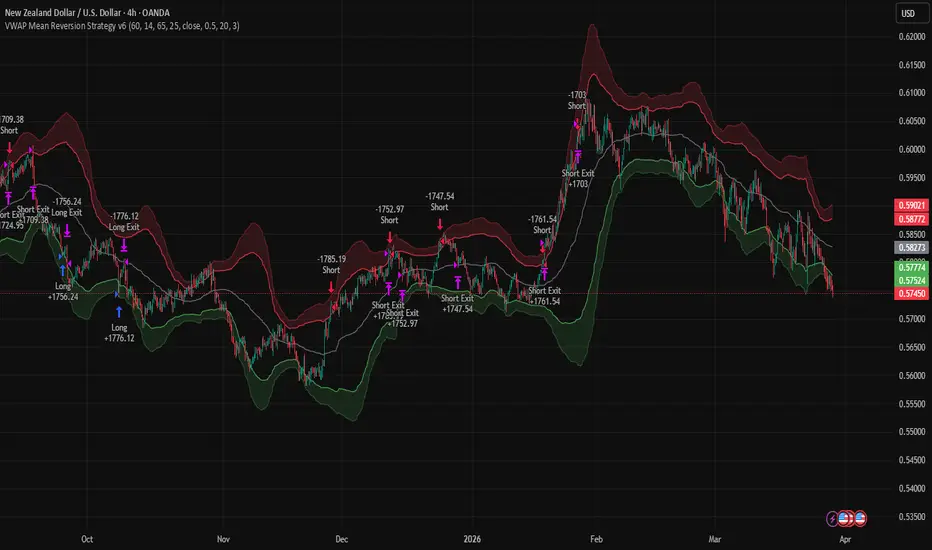
### 🔷 Overview
VWAP Mean Reversion Strategy v6 is a systematic intraday trading model designed specifically for **range-bound forex markets**, where price oscillates around a fair value rather than trending.
The strategy leverages a **custom rolling VWAP (volume-weighted mean)** combined with deviation bands to identify statistically stretched price conditions and execute mean-reversion trades.
---
### ⚙️ Core Logic
This strategy operates on three key principles:
**1. VWAP-Based Mean Reversion**
* Uses a rolling VWAP (not session VWAP) as dynamic equilibrium
* Constructs deviation bands using volume-weighted absolute deviation
* Trades occur when price deviates significantly from fair value
**2. RSI Confirmation Filter**
* Long trades: RSI below oversold threshold
* Short trades: RSI above overbought threshold
* Helps avoid premature entries
**3. Volume Exhaustion Filter**
* Avoids trades during abnormal volume spikes
* Filters out potential breakout conditions (non-mean-reverting environments)
---
### 📊 Entry Conditions
**🔽 Long Setup**
* Price crosses below Lower Band (2σ deviation)
* RSI confirms oversold condition
* No extreme volume spike
**🔼 Short Setup**
* Price crosses above Upper Band (2σ deviation)
* RSI confirms overbought condition
* No extreme volume spike
---
### 🎯 Exit Logic
* **Take Profit:** Return to VWAP (mean reversion target)
* **Stop Loss:** Fixed % risk from entry price
* Designed for **high-probability, small-edge trades**
---
### 💱 Best Use Case (Forex Focus)
This strategy performs best in:
* **Range-bound currency pairs** (e.g., EUR/USD, GBP/USD, USD/JPY)
* **Low to moderate volatility sessions**
* **Non-trending market phases**
Avoid during:
* High-impact news events
* Strong directional trends
* Breakout environments
---
### ⚠️ Strategy Profile
* Type: Mean Reversion
* Market Condition: Sideways / Consolidation
* Frequency: Moderate to High
* Risk: Tight stops, frequent trades
---
### 🧠 Notes
* VWAP length controls sensitivity (shorter = faster signals)
* RSI thresholds can be tightened for higher precision
* Volume filter is critical to avoid false reversals
---
### 📌 Disclaimer
This strategy is for educational and research purposes only.
Not financial advice. Always validate with forward testing and proper risk management.
---
### 🔖 Credits
Concept based on VWAP mean reversion principles and statistical deviation modeling.
Customized into a systematic trading framework for forex markets.
오픈 소스 스크립트
트레이딩뷰의 진정한 정신에 따라, 이 스크립트의 작성자는 이를 오픈소스로 공개하여 트레이더들이 기능을 검토하고 검증할 수 있도록 했습니다. 작성자에게 찬사를 보냅니다! 이 코드는 무료로 사용할 수 있지만, 코드를 재게시하는 경우 하우스 룰이 적용된다는 점을 기억하세요.

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
오픈 소스 스크립트
트레이딩뷰의 진정한 정신에 따라, 이 스크립트의 작성자는 이를 오픈소스로 공개하여 트레이더들이 기능을 검토하고 검증할 수 있도록 했습니다. 작성자에게 찬사를 보냅니다! 이 코드는 무료로 사용할 수 있지만, 코드를 재게시하는 경우 하우스 룰이 적용된다는 점을 기억하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.