Trifactor - Fed Net Dollar Liquidity [FRED]
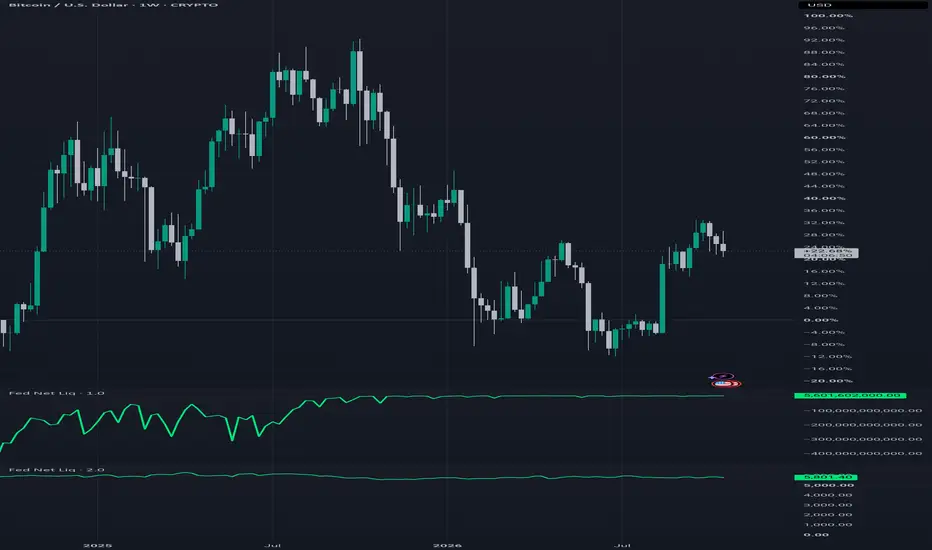
### Overview
The Federal Reserve Net Dollar Liquidity Index tracks the real, structural supply of dollar liquidity circulating within the global banking and financial plumbing.
Standard monetary headlines often focus solely on the Fed Funds target rate. However, risk assets (such as Bitcoin and equities) trade primarily on actual balance sheet liquidity rather than rate commentary.
### Mathematical Formula & Data Sourcing
This open-source indicator queries three official weekly statistical series directly from the Federal Reserve Bank of St. Louis (FRED):
Net Liquidity = WALCL - WTREGEN - RRPONTSYD
1. Fed Total Assets (FRED:WALCL): The aggregate size of the Federal Reserve’s balance sheet (Quantitative Easing vs. Quantitative Tightening).
2. Treasury General Account (FRED:WTREGEN): The U.S. Treasury's checking account held at the Fed. When the Treasury drains cash from markets into the TGA, commercial bank reserves contract.
3. Overnight Reverse Repurchase Agreements (FRED:RRPONTSYD): Cash parked by money market funds at the Fed, effectively sterilizing it from active capital markets.
The result is expressed in Billions of USD ($B).
### How to Use
- Rising Net Liquidity represents structural monetary expansion, easing bank reserves, and providing a fundamental macro tailwind for risk-on assets.
- Falling Net Liquidity reflects monetary contraction and systemic liquidity withdrawal, signaling defensive conditions.
Best viewed on a Weekly (1W) timeframe alongside BTC/USD, Gold, or broader equity indices. Data updated each Thursday as this is when Fed updates it.
---
Disclaimer: Sourced strictly from public St. Louis Fed data for macroeconomic research and educational purposes. Not financial advice. For weekly systematic regime updates and multi-asset rotational research, check author bio.
The Federal Reserve Net Dollar Liquidity Index tracks the real, structural supply of dollar liquidity circulating within the global banking and financial plumbing.
Standard monetary headlines often focus solely on the Fed Funds target rate. However, risk assets (such as Bitcoin and equities) trade primarily on actual balance sheet liquidity rather than rate commentary.
### Mathematical Formula & Data Sourcing
This open-source indicator queries three official weekly statistical series directly from the Federal Reserve Bank of St. Louis (FRED):
Net Liquidity = WALCL - WTREGEN - RRPONTSYD
1. Fed Total Assets (FRED:WALCL): The aggregate size of the Federal Reserve’s balance sheet (Quantitative Easing vs. Quantitative Tightening).
2. Treasury General Account (FRED:WTREGEN): The U.S. Treasury's checking account held at the Fed. When the Treasury drains cash from markets into the TGA, commercial bank reserves contract.
3. Overnight Reverse Repurchase Agreements (FRED:RRPONTSYD): Cash parked by money market funds at the Fed, effectively sterilizing it from active capital markets.
The result is expressed in Billions of USD ($B).
### How to Use
- Rising Net Liquidity represents structural monetary expansion, easing bank reserves, and providing a fundamental macro tailwind for risk-on assets.
- Falling Net Liquidity reflects monetary contraction and systemic liquidity withdrawal, signaling defensive conditions.
Best viewed on a Weekly (1W) timeframe alongside BTC/USD, Gold, or broader equity indices. Data updated each Thursday as this is when Fed updates it.
---
Disclaimer: Sourced strictly from public St. Louis Fed data for macroeconomic research and educational purposes. Not financial advice. For weekly systematic regime updates and multi-asset rotational research, check author bio.

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.