[core convexity] accurate strike -> futures conversion
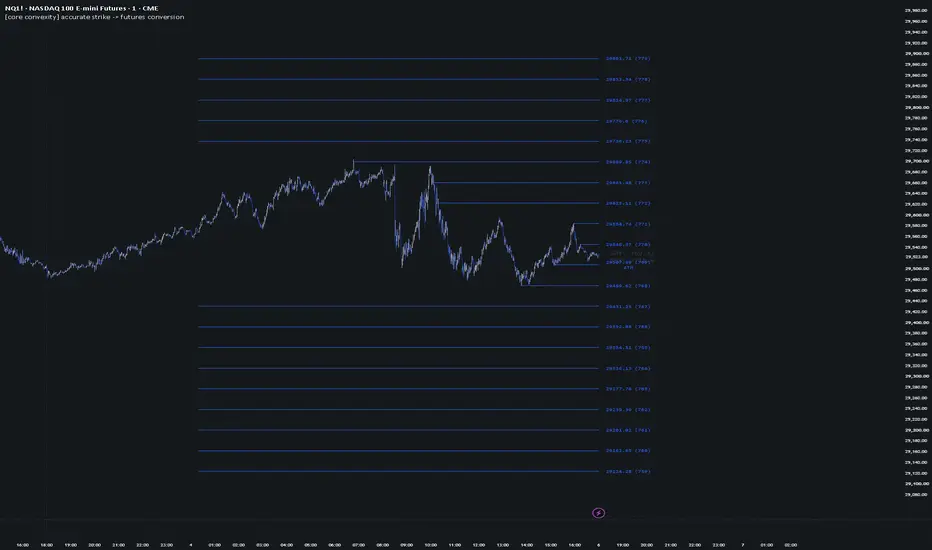
converts etf/index strikes into futures levels using a live smoothed price ratio between the selected cash product and futures contract. presets cover common pairs like es/spx, es/spy, nq/ndx, nq/qqq, gc/gld and si/slv, with manual symbol selection available too.
theory
the conversion is based on the live futures / cash ratio with configurable smoothing, optional tick-size rounding and output precision. extended-session cash data is used so the relationship can continue updating outside regular equity hours.
because its smoothed its better to roughly plot on lower time frames
how to operate it
strikes can be pasted manually or generated automatically around price. batch mode supports optional names in quotes, while auto mode builds a strike grid around the implied cash price using preset or manually defined intervals.
levels can be drawn as lines or boxes (addresses for small deviation that may occur naturally). mitigated mode stops the historical extension where price previously interacted with the level, while full-left mode keeps it extended. styling, box size, labels and positioning are all configurable.
v6 also includes an optional conversion table, live two-symbol monitor and touch alerts for converted lines or zones. lower timeframes generally give the conversion more responsiveness, while higher smoothing produces steadier levels.
please stop taking it down
they keep taking this script down for the description not being good enough (???) i dont know despite me clearly explaining how to work it. anyways enjoy this along with my series of other scripts
theory
the conversion is based on the live futures / cash ratio with configurable smoothing, optional tick-size rounding and output precision. extended-session cash data is used so the relationship can continue updating outside regular equity hours.
because its smoothed its better to roughly plot on lower time frames
how to operate it
strikes can be pasted manually or generated automatically around price. batch mode supports optional names in quotes, while auto mode builds a strike grid around the implied cash price using preset or manually defined intervals.
levels can be drawn as lines or boxes (addresses for small deviation that may occur naturally). mitigated mode stops the historical extension where price previously interacted with the level, while full-left mode keeps it extended. styling, box size, labels and positioning are all configurable.
v6 also includes an optional conversion table, live two-symbol monitor and touch alerts for converted lines or zones. lower timeframes generally give the conversion more responsiveness, while higher smoothing produces steadier levels.
please stop taking it down
they keep taking this script down for the description not being good enough (???) i dont know despite me clearly explaining how to work it. anyways enjoy this along with my series of other scripts

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.