OPEN-SOURCE SCRIPT
Kalman Regime [Jamallo]
(2025)
Intro
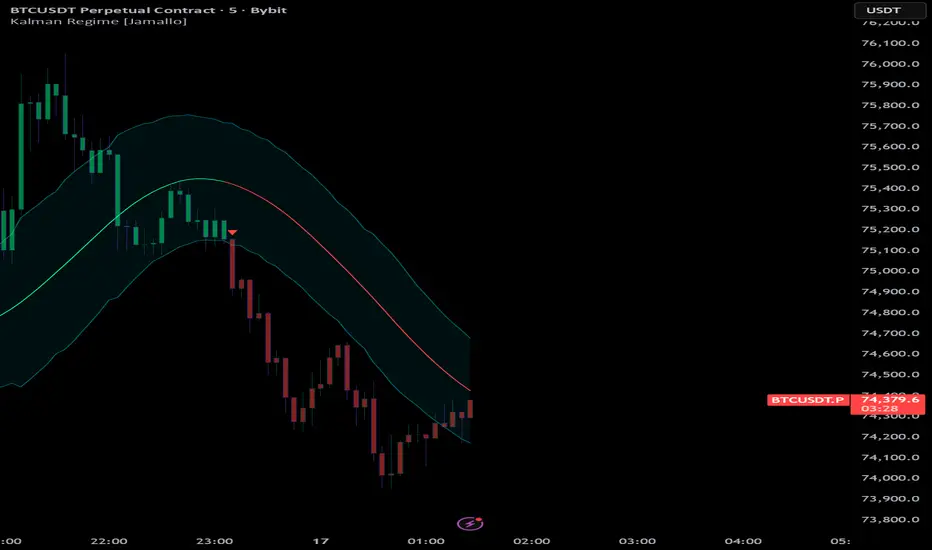
Kalman Regime filters price through two stages — a Gaussian kernel weighted average followed by an adaptive Kalman filter — to produce a smooth, noise-resistant baseline. ATR is used throughout to make the system volatility-aware.
Breakdown
The Gaussian kernel pre-smooths price using a bell-shaped weight profile that blends recency bias (recent bars matter more) with center localization (edge bars contribute less). This pre-smoothed value is then passed into an adaptive Kalman filter, which recursively estimates the "true" price state by balancing how much to trust the new measurement versus the prior state — with that balance dynamically scaled by current ATR.
The resulting baseline drives regime detection through a two-tier state machine. A strong signal fires when price breaks the ATR envelope and the baseline slope confirms direction. A weaker signal fires when price crosses the baseline and slope exceeds an ATR-scaled threshold. This dual-gate structure reduces whipsaws without adding lag.
END
A two-stage price filter combining a Gaussian kernel pre-smoother with an adaptive Kalman filter, using ATR envelopes and slope confirmation for regime detection.
오픈 소스 스크립트
트레이딩뷰의 진정한 정신에 따라, 이 스크립트의 작성자는 이를 오픈소스로 공개하여 트레이더들이 기능을 검토하고 검증할 수 있도록 했습니다. 작성자에게 찬사를 보냅니다! 이 코드는 무료로 사용할 수 있지만, 코드를 재게시하는 경우 하우스 룰이 적용된다는 점을 기억하세요.

Join the Growing (Econophysics Trading) Community! ⚛️
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
오픈 소스 스크립트
트레이딩뷰의 진정한 정신에 따라, 이 스크립트의 작성자는 이를 오픈소스로 공개하여 트레이더들이 기능을 검토하고 검증할 수 있도록 했습니다. 작성자에게 찬사를 보냅니다! 이 코드는 무료로 사용할 수 있지만, 코드를 재게시하는 경우 하우스 룰이 적용된다는 점을 기억하세요.
Join the Growing (Econophysics Trading) Community! ⚛️
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
discord.com/invite/qb4RKFdwYJ
Trade the physics of price.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.