OPEN-SOURCE SCRIPT
NQ HMA Midday Strategy
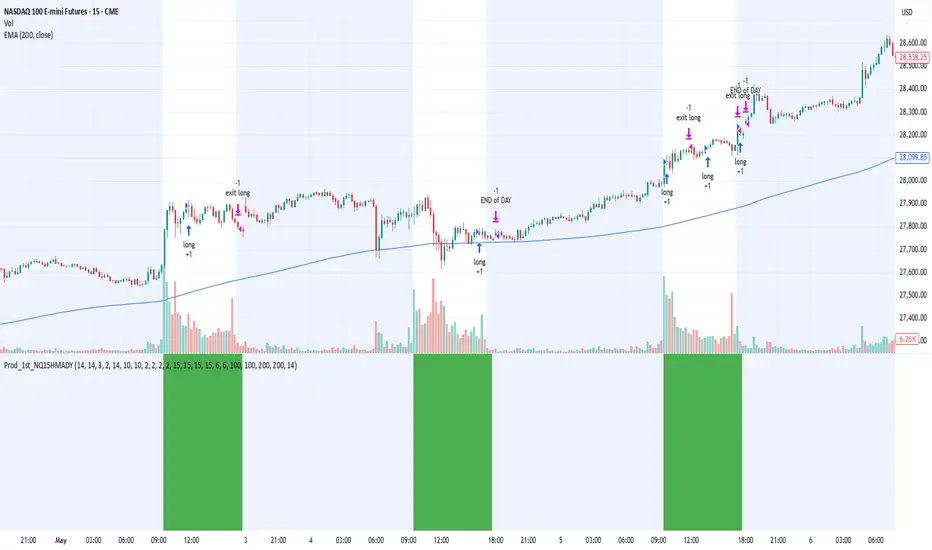
The Story Behind This Strategy
This strategy didn't come from a quick backtest or a weekend project. It's the result of months of systematic research across multiple strategy families (DVD, Zscore, HMA) on both NQ and ES futures.
My Research Process:
I started with six strategy families and ran extensive backtests spanning from 2019 through April 2025, followed by recent validation from 2025 through April 2026. My goal wasn't to maximize historical PnL - it was to identify robust strategies with better drawdown behavior, stronger profit factors, and more stable portfolio-level risk/reward.
After evaluating hundreds of parameter combinations and multiple objective functions, I narrowed down to two core NQ candidates. This HMA Midday strategy emerged as one of them because it showed:
Strong recent performance (2025-2026: $16,865 profit, 1.53 profit factor)
Reasonable drawdown characteristics ($8,940 max drawdown)
Clean portfolio behavior when combined with other strategies
Better risk-adjusted returns than the baseline HMA version
What This Strategy Actually Does:
It's a momentum-based system using Hull Moving Averages, EMAs, and Rate of Change to identify trade setups during specific time windows (11:00-15:45 ET trading, 10:30-13:00 ET entries). I added the one-trade-per-day limit after observing that multiple daily entries often degraded risk-adjusted returns.
The Honest Truth:
This is still a research strategy, not a live-trading system
I have a Python version with walk-forward optimization that I use to tune parameters when market regimes change
Parameters should be re-optimized periodically - they're not set-and-forget
The strategy works best as part of a portfolio, not in isolation
Past performance (2019-2026) doesn't guarantee future results
Why I'm Publishing It:
To share the methodology and code structure with the community. The approach - combining trend indicators with momentum filters, time windows, and ATR-based risk management - is worth studying even if you don't trade this exact configuration.
Developer: QuantByBoji
Status: Research candidate, not live-trading recommendation
오픈 소스 스크립트
트레이딩뷰의 진정한 정신에 따라, 이 스크립트의 작성자는 이를 오픈소스로 공개하여 트레이더들이 기능을 검토하고 검증할 수 있도록 했습니다. 작성자에게 찬사를 보냅니다! 이 코드는 무료로 사용할 수 있지만, 코드를 재게시하는 경우 하우스 룰이 적용된다는 점을 기억하세요.

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
오픈 소스 스크립트
트레이딩뷰의 진정한 정신에 따라, 이 스크립트의 작성자는 이를 오픈소스로 공개하여 트레이더들이 기능을 검토하고 검증할 수 있도록 했습니다. 작성자에게 찬사를 보냅니다! 이 코드는 무료로 사용할 수 있지만, 코드를 재게시하는 경우 하우스 룰이 적용된다는 점을 기억하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.