[BCT] Identify BULL / BEAR regimes - Laguerre Filter
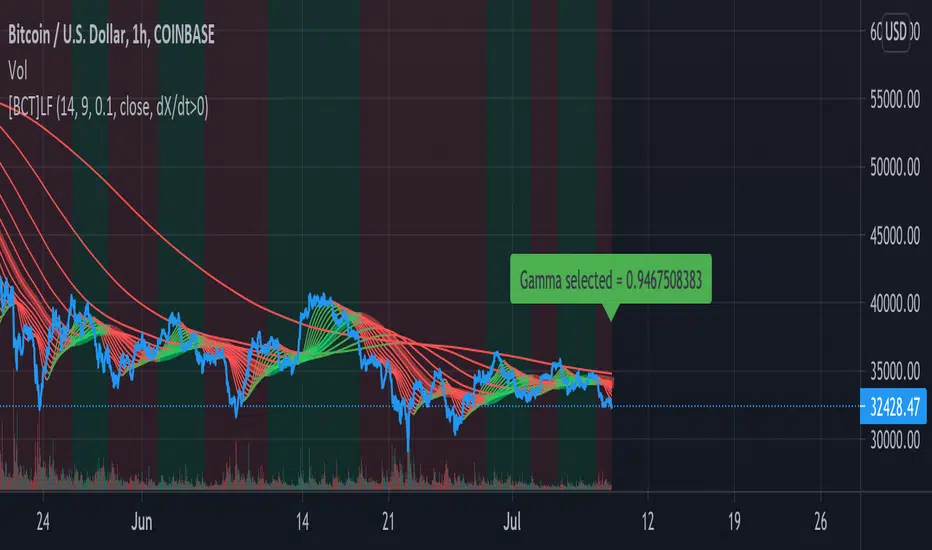
The Adaptive Laguerre is based on the Laguerre filter, described by John Ehlers in his paper “Time Warp – Without Space Travel”
forex-station.com/download/file.php?id=3326725
MAs obtained using a Laguerre filter tend to have much lower lag than MAs obtained from an SMA or EMA.
Use cases:
- Identify market regime (BULL vs BEAR)
- Smooth out a noisy signal (e.g. apply to RSI, prices, log returns, variance, etc) without adding excessive lag
Highlight based on:
- Smoothed indicator > or < 0
- Derivative of the indicator ("speed") > or < 0
- Second derivative of the indicator ("acceleration" or "momentum") > or < 0
[BCT]
forex-station.com/download/file.php?id=3326725
MAs obtained using a Laguerre filter tend to have much lower lag than MAs obtained from an SMA or EMA.
Use cases:
- Identify market regime (BULL vs BEAR)
- Smooth out a noisy signal (e.g. apply to RSI, prices, log returns, variance, etc) without adding excessive lag
Highlight based on:
- Smoothed indicator > or < 0
- Derivative of the indicator ("speed") > or < 0
- Second derivative of the indicator ("acceleration" or "momentum") > or < 0
[BCT]

면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.
면책사항
해당 정보와 게시물은 금융, 투자, 트레이딩 또는 기타 유형의 조언이나 권장 사항으로 간주되지 않으며, 트레이딩뷰에서 제공하거나 보증하는 것이 아닙니다. 자세한 내용은 이용 약관을 참조하세요.